



Stablecoin Yield Rules Reshape Cross-Border Payment Options for E-Commerce Sellers
- Senate Banking Committee debates Section 404 provisions affecting payment settlement speeds and working capital financing for international sellers by spring 2026













概览
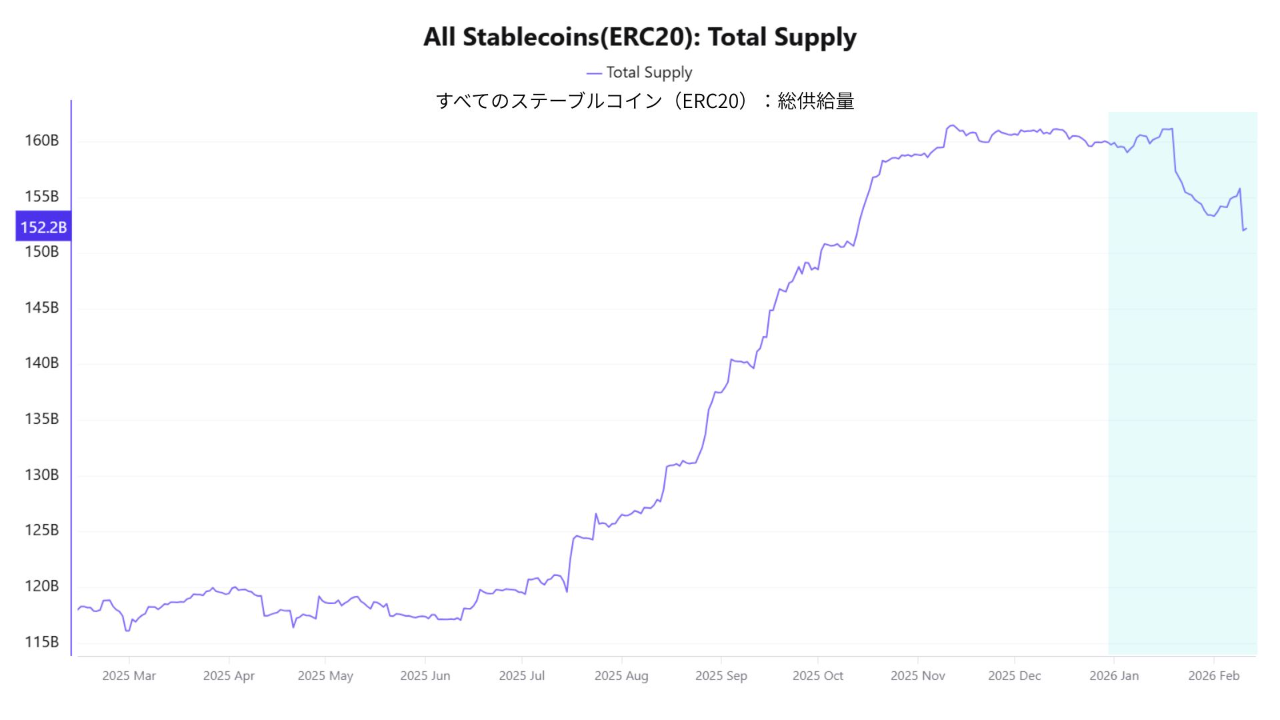
The U.S. Senate Banking Committee's negotiations over stablecoin yield regulations represent a critical inflection point for cross-border e-commerce payment infrastructure. On February 13-14, 2026, the Digital Chamber of Commerce released competing principles to Wall Street bankers' "Yield and Interest Prohibition Principles," creating a regulatory fork that directly impacts how sellers can optimize payment settlement and working capital management. The core dispute centers on Section 404 of the Digital Asset Market Clarity Act, which modifies the GENIUS Act's treatment of stablecoin rewards—specifically whether yields on transaction-tied rewards versus static holdings should be permitted.
For sellers accepting stablecoin payments, this regulatory outcome determines payment cost structures and cash flow timing. If the crypto industry's position prevails (preserving transaction-activity rewards), sellers gain access to yield-bearing stablecoin settlement accounts that could generate 3-5% annual returns on payment float—effectively reducing net payment processing costs by 40-60 basis points. Conversely, if banks succeed in banning all yields, stablecoin adoption as a payment method becomes less attractive versus traditional ACH or wire transfers, potentially increasing payment processing costs by $200-400 monthly for sellers processing $500K+ in monthly cross-border volume.
The political timeline creates immediate cash flow optimization opportunities. Treasury Secretary Scott Bessent's February 13 announcement that Congress should pass the Clarity Act by spring 2026 signals a compressed decision window. The Senate Agriculture Committee has already passed its commodities-focused version, but the Banking Committee's securities-focused version requires Democratic support for the 60-vote majority. If Democrats gain House control in November 2026 elections, the bipartisan coalition supporting any crypto regulation could collapse, leaving the status quo GENIUS Act framework in place—which currently permits stablecoin rewards as structured. This creates a 90-day window (February-April 2026) where sellers should evaluate stablecoin payment integration before regulatory clarity emerges.
Working capital implications are substantial for high-volume sellers. Stablecoin payment settlement typically clears in 1-2 hours versus 2-3 business days for traditional banking corridors. If yield-bearing stablecoin accounts remain legal, sellers can deploy payment float into yield-generating positions, unlocking $50-150K in annual working capital returns for sellers processing $5M+ annually. Invoice financing providers are already positioning stablecoin-backed factoring products targeting this regulatory outcome, offering 2-3% discounts on factoring fees for sellers willing to accept stablecoin settlement. The Digital Chamber's willingness to compromise on static holdings while preserving transaction rewards suggests the final rule will likely permit yield-bearing settlement accounts, making stablecoin payment infrastructure a material cost-saving opportunity.
问题 8
What are the FX arbitrage opportunities in stablecoin payment settlement?
Stablecoin payment settlement creates FX arbitrage opportunities for sellers managing multi-currency operations. USDC and USDT maintain tight pegs to USD (±0.1%), eliminating currency conversion slippage versus traditional forex corridors (0.5-1.5% spreads). For sellers receiving payments in EUR, GBP, or JPY, converting to stablecoins and then to USD avoids traditional banking spreads, saving 50-100 basis points on $1M+ monthly volume. Additionally, yield-bearing stablecoin accounts allow sellers to hold settlement float in high-yield positions (3-5% annual) while waiting for optimal forex conversion windows, effectively monetizing timing arbitrage. The regulatory outcome permitting transaction-activity rewards makes this strategy more attractive because settlement yields offset the cost of holding stablecoins during conversion delays. For sellers with $2M+ monthly cross-border volume, stablecoin payment integration could unlock $10-20K annually in FX arbitrage savings.
Which payment providers offer stablecoin settlement with yield benefits?
Circle, Stripe Crypto, and emerging DeFi payment platforms like Aave's payment integrations offer stablecoin settlement with yield-bearing account options. Circle's USDC settlement provides 1-2 hour clearing with optional yield accounts generating 2-4% annual returns. Stripe's crypto payment option integrates with Coinbase Commerce for settlement. Traditional payment processors like PayPal and Square have not yet launched stablecoin settlement, creating a competitive gap for sellers seeking faster cash conversion. Invoice factoring providers including Clearco and Uncapped are launching stablecoin-backed factoring products offering 2-3% fee discounts for sellers accepting stablecoin settlement. For sellers processing $500K+ monthly in cross-border volume, evaluating Circle or Stripe's stablecoin options provides immediate cost savings (40-60 basis points) while regulatory clarity emerges.