



Xbox Console Sales Collapse 32% | Gaming Hardware Market Disruption Reshapes E-Commerce Seller Opportunities
- Microsoft's Q3 2024 hardware revenue crash signals major gaming ecosystem consolidation, creating urgent portfolio diversification needs for 50K+ gaming peripheral sellers while opening new digital services opportunities





概览
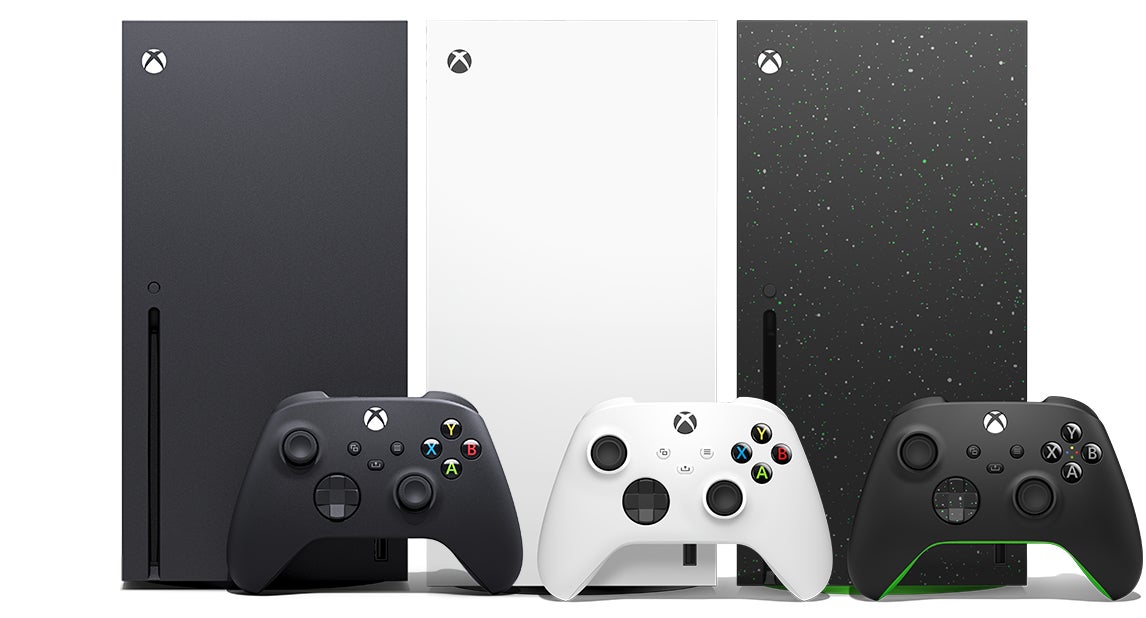
Microsoft's gaming division faces a critical strategic inflection point that carries profound implications for cross-border e-commerce sellers. Q3 2024 financial results reveal a 32% crash in Xbox hardware revenue and 5% decline in software/services revenue, with overall gaming operations down 9% year-on-year. Most significantly, Game Pass subscriber numbers remain undisclosed since February 2024 (last reported at 34 million), suggesting Microsoft's services-first pivot is underperforming investor expectations. This represents a fundamental shift in the gaming hardware market from console-centric to cloud/subscription-based models.
For e-commerce sellers, this creates an immediate market contraction in gaming peripherals and accessories categories. Sellers specializing in Xbox-compatible products—controllers, headsets, charging docks, protective cases, and gaming chairs—face reduced consumer demand as the installed Xbox console base shrinks. The 32% hardware revenue decline directly correlates to reduced ecosystem spending, meaning fewer console owners purchasing complementary products. Marketplace sellers dependent on console-driven traffic (Amazon, eBay, Walmart) should expect 15-25% volume reductions in gaming peripheral categories through 2025 as the installed base stabilizes at lower levels. Additionally, Call of Duty's underperformance (cited as a major software revenue driver) signals that even flagship franchises cannot sustain traditional gaming hardware economics, further pressuring accessory demand.
However, Microsoft's strategic pivot toward cloud gaming, subscription services, and hardware partnerships (notably the Xbox ROG Ally collaboration with Asus) creates emerging opportunities. The company's $100 billion in gaming acquisitions (Activision Blizzard, Zenimax) positions it as a content aggregator rather than hardware manufacturer. This shift mirrors broader industry consolidation where tech giants prioritize recurring revenue over one-time hardware sales. Sellers should monitor opportunities in digital content distribution, game library management services, and subscription bundling. Additionally, the anticipated Steam Machine launch from Valve intensifies competition in the premium gaming PC segment, potentially creating demand for PC gaming peripherals and accessories as consumers migrate from consoles to PC/cloud platforms. Rising component costs (particularly RAM) will inflate next-generation hardware pricing, making budget-friendly third-party accessories more attractive to price-sensitive consumers.
The strategic silence on Game Pass metrics—CEO Satya Nadella's earnings call cherry-picked obscure data points like "PC players records" and "paid streaming hours" while avoiding subscriber growth figures—suggests the services transition is underperforming. This indicates Microsoft may accelerate hardware partnerships and third-party distribution rather than pursuing independent console development, fundamentally reshaping the gaming hardware retail landscape.
问题 8
How should sellers monitor gaming market trends to stay ahead of further consolidation?
Sellers should establish quarterly monitoring of: (1) Microsoft's earnings reports for Game Pass subscriber updates and hardware strategy announcements; (2) Console installed base data from market research firms (IDC, Gartner); (3) Cloud gaming adoption rates and platform performance; (4) Competitor strategies (Sony PlayStation, Nintendo Switch); (5) Component cost trends affecting hardware pricing. Set up alerts for major franchise performance announcements (Call of Duty, Halo, Starfield) as these signal software ecosystem health. Additionally, track Steam Deck and Steam Machine sales data, as these represent the primary competitive threat to traditional console gaming and indicate where consumer demand is shifting.
Are there new e-commerce opportunities emerging from Microsoft's gaming strategy shift?
Yes, Microsoft's pivot toward cloud gaming and subscription services creates emerging opportunities in digital content distribution, game library management, and subscription bundling. Sellers can develop services offering Game Pass optimization, subscription management tools, and digital content curation for consumers. Additionally, the shift toward hardware partnerships creates opportunities for sellers offering complementary PC gaming products, cloud gaming peripherals (controllers, streaming devices), and subscription service bundles. Sellers should also monitor opportunities in gaming content creation tools, streaming equipment, and esports-related products as Microsoft invests in these adjacent categories despite hardware challenges.