
Programmatic Advertising Platform Volatility Signals Rising Customer Acquisition Costs for E-Commerce Sellers in 2025
- The Trade Desk stock collapse 67% YoY despite solid fundamentals; Kokai AI platform delivers 26% better CPA; sellers face tightening digital ad budgets and rising customer acquisition costs


















Overview
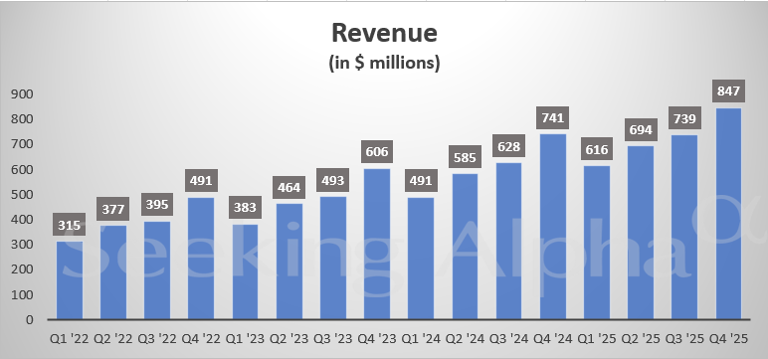
The Trade Desk (TTD), a major programmatic advertising platform serving e-commerce sellers globally, faces a critical inflection point in Q4 2025 despite meeting earnings expectations. The company reported Q4 revenue of $846.79 million (up 14.3% YoY from $741.01 million) with EPS of $0.59 matching consensus, marking the third earnings beat in four quarters. However, the stock has collapsed 67% over the past year and declined 34.3% since January 2025, driven by AI disruption concerns, CFO departure, and broader market uncertainty. This disconnect between operational performance and market valuation reveals critical dynamics affecting e-commerce sellers' advertising strategies.
The underlying business fundamentals remain resilient despite market panic. Q3 2025 revenue reached $739 million (18% YoY growth), customer retention exceeded 95%, and the company's Kokai AI-powered advertising platform achieved 85% adoption among clients. Kokai delivered measurable performance improvements: 26% better cost per acquisition (CPA) and 58% better cost per unique reach compared to the legacy platform. These metrics directly impact e-commerce sellers' marketing ROI. Management guided for Q4 revenue of at least $840 million with adjusted EBITDA of approximately $375 million, representing 17-18% YoY growth. Institutional investors including Bank of New York Mellon (41% stake increase) and Principal Financial Group (325% position growth in Q3) have quietly accumulated positions, with prediction markets assigning 77% probability that TTD reports non-GAAP EPS above the 58-cent consensus.
However, broader market headwinds signal tightening advertising budgets across digital channels. The Internet Services industry ranks in the bottom 30 of 250+ Zacks-ranked industries, with top-50 industries outperforming bottom-50 by a 2-to-1 factor. Analysts maintain unfavorable estimate revision trends, resulting in a Zacks Rank 4 (Sell) rating. Forward guidance shows consensus expectations of $0.35 EPS for Q1 2025 on $685.9 million in revenues, with full-year estimates of $2.10 EPS on $3.35 billion in revenues. For cross-border e-commerce sellers utilizing programmatic advertising, this creates a paradox: TTD's Kokai platform offers superior CPA efficiency (26% improvement), yet sector weakness may constrain overall advertising budgets. Sellers relying on digital advertising for customer acquisition face a critical decision: optimize spending through advanced AI platforms or diversify marketing channels. The stock's brutal repricing may reflect rational concerns about structural industry deceleration or panic-driven overreaction—tonight's earnings call will determine whether TTD can sustain growth momentum and validate its AI-powered platform strategy.
Questions 8
How can I calculate the impact of rising advertising costs on my product margins?
Use this framework: (1) Calculate current CAC by channel: Total advertising spend ÷ New customers acquired = CAC; (2) Determine CAC as percentage of product margin: CAC ÷ Product gross margin = CAC percentage; (3) Model 10-15% cost increase: Current CAC × 1.10 to 1.15 = New CAC; (4) Calculate margin impact: (New CAC - Current CAC) ÷ Product gross margin = Margin compression percentage. Example: $50 product with 40% margin ($20 gross profit), current CAC $8 (40% of margin), 12% increase = new CAC $8.96, reducing margin to 35.2%. For sellers with CAC exceeding 30% of margin, rising advertising costs become unsustainable—prioritize conversion optimization and owned channels immediately.
How should cross-border e-commerce sellers adjust marketing strategies given programmatic platform uncertainty?
Cross-border sellers should implement a three-tier diversification strategy: (1) **Tier 1 (40% budget)**: Maintain programmatic spend on TTD or Google DV360, focusing on high-ROI campaigns with proven CPA metrics. Use Kokai AI optimization if available. (2) **Tier 2 (35% budget)**: Shift to owned channels—Amazon Sponsored Ads (for Amazon sellers), Google Shopping, and marketplace native advertising. These channels offer lower volatility and direct platform control. (3) **Tier 3 (25% budget)**: Invest in organic growth—SEO, content marketing, email marketing, and social commerce. These channels build long-term brand equity independent of programmatic platform pricing. For sellers with $50K+ monthly ad spend, this diversification reduces exposure to any single platform's pricing increases or service disruptions. Monitor TTD's Q1 2025 earnings (April 2025) and adjust allocation based on guidance and analyst sentiment.