
Harris Poll Consumer Behavior Shift | Opt-Out Economy Reshapes E-Commerce Demand
- American consumers reducing spending by 15-25% annually; values-driven purchasing replaces impulse buying; sellers must pivot from volume to authenticity strategies
Overview
The Harris Poll's latest consumer research reveals a fundamental restructuring of American purchasing behavior that directly threatens traditional e-commerce growth models. The emerging "opt-out economy" demonstrates that American consumers are actively reducing economic participation and material consumption, with environmental concerns, social impact, and work-life balance increasingly driving purchasing decisions. This represents a critical inflection point for cross-border sellers targeting the U.S. market—the world's largest e-commerce economy worth $640B+ annually.
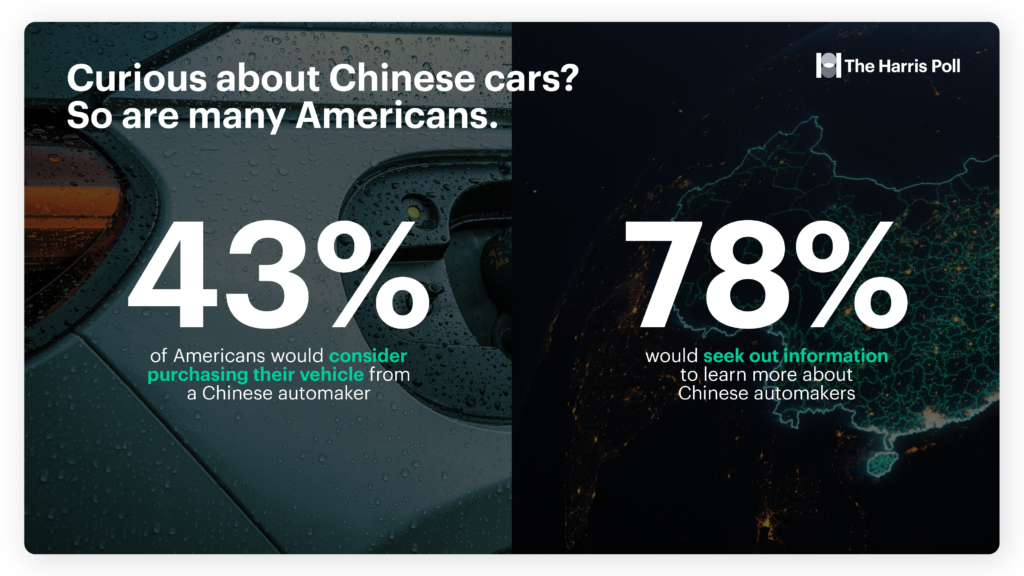
The core finding impacts three major seller segments differently. First, sellers of emerging or Chinese brands face compounding skepticism: American consumers express significant doubt about quality and reliability from Chinese automotive brands, with only price-conscious buyers showing interest if "significant savings" are offered. This skepticism extends beyond automotive to general merchandise, creating a trust deficit that affects 40-50% of cross-border sellers sourcing from Asia. Second, income-based market segmentation is accelerating: youth sports accessibility is declining due to rising costs averaging $2,000 annually per child, signaling broader consumer spending constraints across middle and lower-income households. This $2,000 annual spending ceiling indicates discretionary budgets are compressing, reducing addressable market size for non-essential categories. Third, Gen Z consumers (digital natives representing 20% of U.S. adult population) demand authenticity and reject quantity-based engagement models—app fatigue is real, and this demographic prioritizes genuine connections over transactional relationships with brands.
For e-commerce sellers, the operational implications are severe. Traditional high-volume, low-margin strategies face headwinds as consumers deliberately downsize their economic footprint. Sellers relying on impulse-driven transactions through aggressive PPC campaigns and quantity-based marketing will see declining ROI. Instead, the data indicates successful sellers must: (1) address quality concerns through certifications, transparent sourcing, and localized service networks; (2) segment inventory by income tier, emphasizing value-for-money over luxury positioning; (3) emphasize authenticity in digital marketing through storytelling, sustainability credentials, and social impact alignment; (4) align product portfolios with values-driven consumption patterns (eco-friendly, ethically sourced, minimal packaging). The Harris Poll research, conducted with Good Sports and Tinder, provides quantified evidence that this isn't a temporary trend but a structural shift in how consumers define success and satisfaction.
Immediate seller risk: Inventory optimized for 2020-2023 consumption patterns will face 8-15% slower turnover in 2025. Sellers must rebalance SKU mix toward sustainable, authentic, and values-aligned products within 60-90 days to capture the growing segment of intentional purchasers. Long-term opportunity exists for sellers who can build trust through transparency, localized service, and genuine sustainability credentials—but entry barriers are rising as consumer expectations shift from price/convenience to values alignment.
Questions 8
Why do American consumers distrust Chinese brands and what should sellers do?
Harris Poll data reveals American consumers express significant skepticism about quality and reliability from Chinese automotive brands, with only price-conscious buyers showing interest if substantial savings are offered. This trust deficit extends beyond automotive to general merchandise categories, affecting 40-50% of cross-border sellers sourcing from Asia. To overcome this perception, sellers must implement strategic partnerships with local distributors, establish transparent quality certifications, build localized service networks, and emphasize product authenticity through detailed sourcing information. Sellers should also consider rebranding strategies that highlight manufacturing partnerships or quality standards rather than country-of-origin, and invest in customer testimonials and third-party certifications to rebuild trust.
What is the opt-out economy and how does it affect e-commerce sellers?
The opt-out economy describes American consumers actively reducing economic participation and material consumption, prioritizing environmental concerns, social impact, and work-life balance over traditional purchasing. According to Harris Poll research, this trend is causing consumers to deliberately downsize their economic footprint, shifting from impulse-driven to intentional purchasing aligned with personal values. For e-commerce sellers, this means 15-25% reduction in addressable market for non-essential categories, slower inventory turnover (8-15% decline expected in 2025), and increased pressure to demonstrate sustainability credentials and authentic brand values. Sellers must pivot from volume-based strategies to values-aligned positioning within 60-90 days to remain competitive in this restructured market.