



US-Spain Trade Tensions & Middle East Escalation | Tariff Arbitrage Opportunities for Cross-Border Sellers
- Geopolitical volatility creates tariff uncertainty; sellers must monitor Spain-US trade corridor and Iran sanctions implications affecting 15-20% of Mediterranean supply chains









Overview
The March 3, 2026 announcement of potential US-Spain trade cessation, coupled with escalating Israel-Hezbollah-Iran military tensions, signals a critical inflection point for cross-border e-commerce sellers operating in transatlantic and Middle Eastern corridors. While the Trump administration's statement lacks specific tariff schedules or implementation timelines, the geopolitical backdrop creates immediate opportunities and risks for sellers managing sourcing, inventory, and market access strategies.
Tariff Arbitrage Opportunities: Spain serves as a critical EU gateway for US-bound imports, particularly in consumer electronics (HS 8471-8517), machinery (HS 8401-8483), and specialty chemicals (HS 2901-2942). A complete trade cessation would force US importers to redirect sourcing through alternative EU ports (Rotterdam, Hamburg) or non-EU suppliers, creating 8-15% cost increases for sellers currently leveraging Spanish distribution centers. Conversely, sellers with inventory positioned in Portugal, France, or Germany could capture market share from competitors dependent on Spanish logistics hubs. The tariff arbitrage window is 30-90 days before major retailers adjust sourcing strategies.
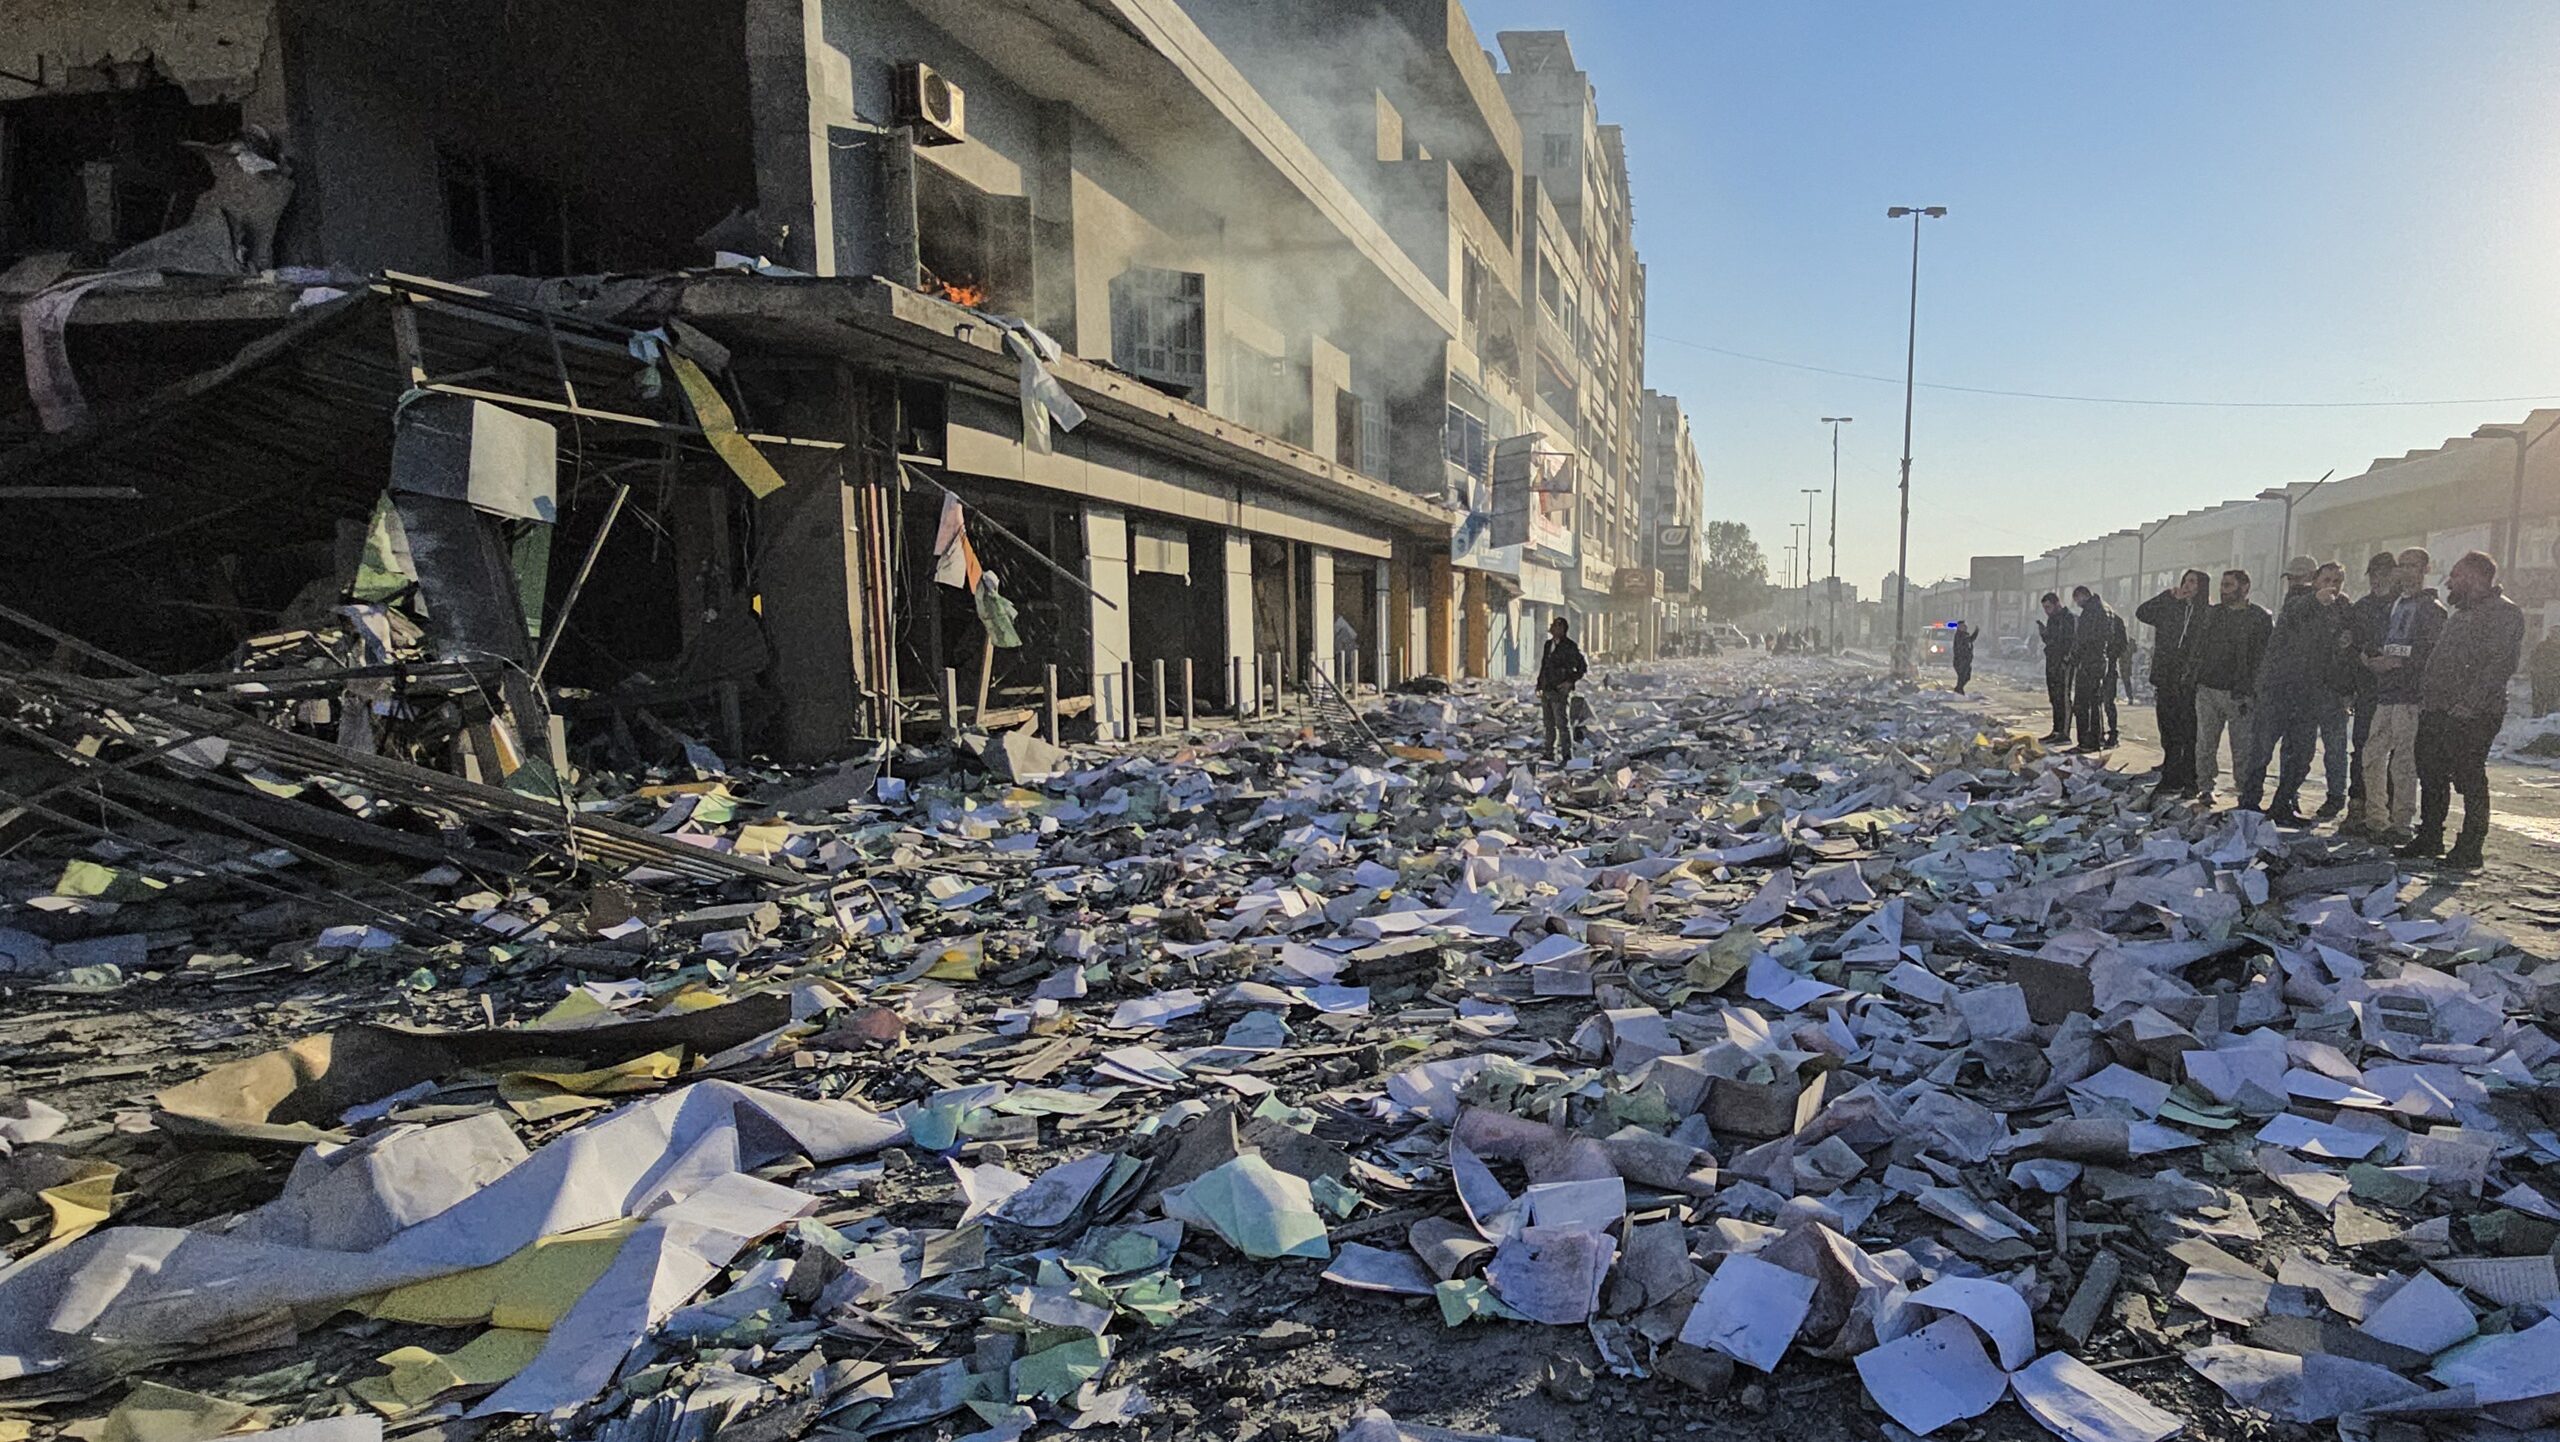
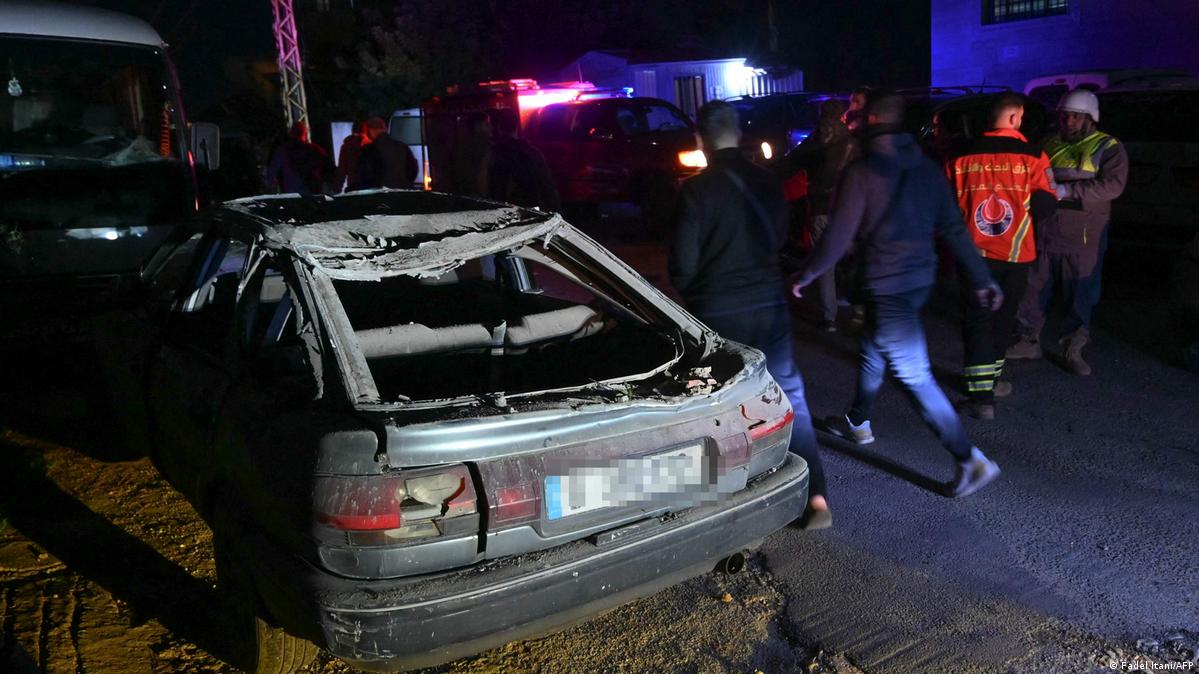
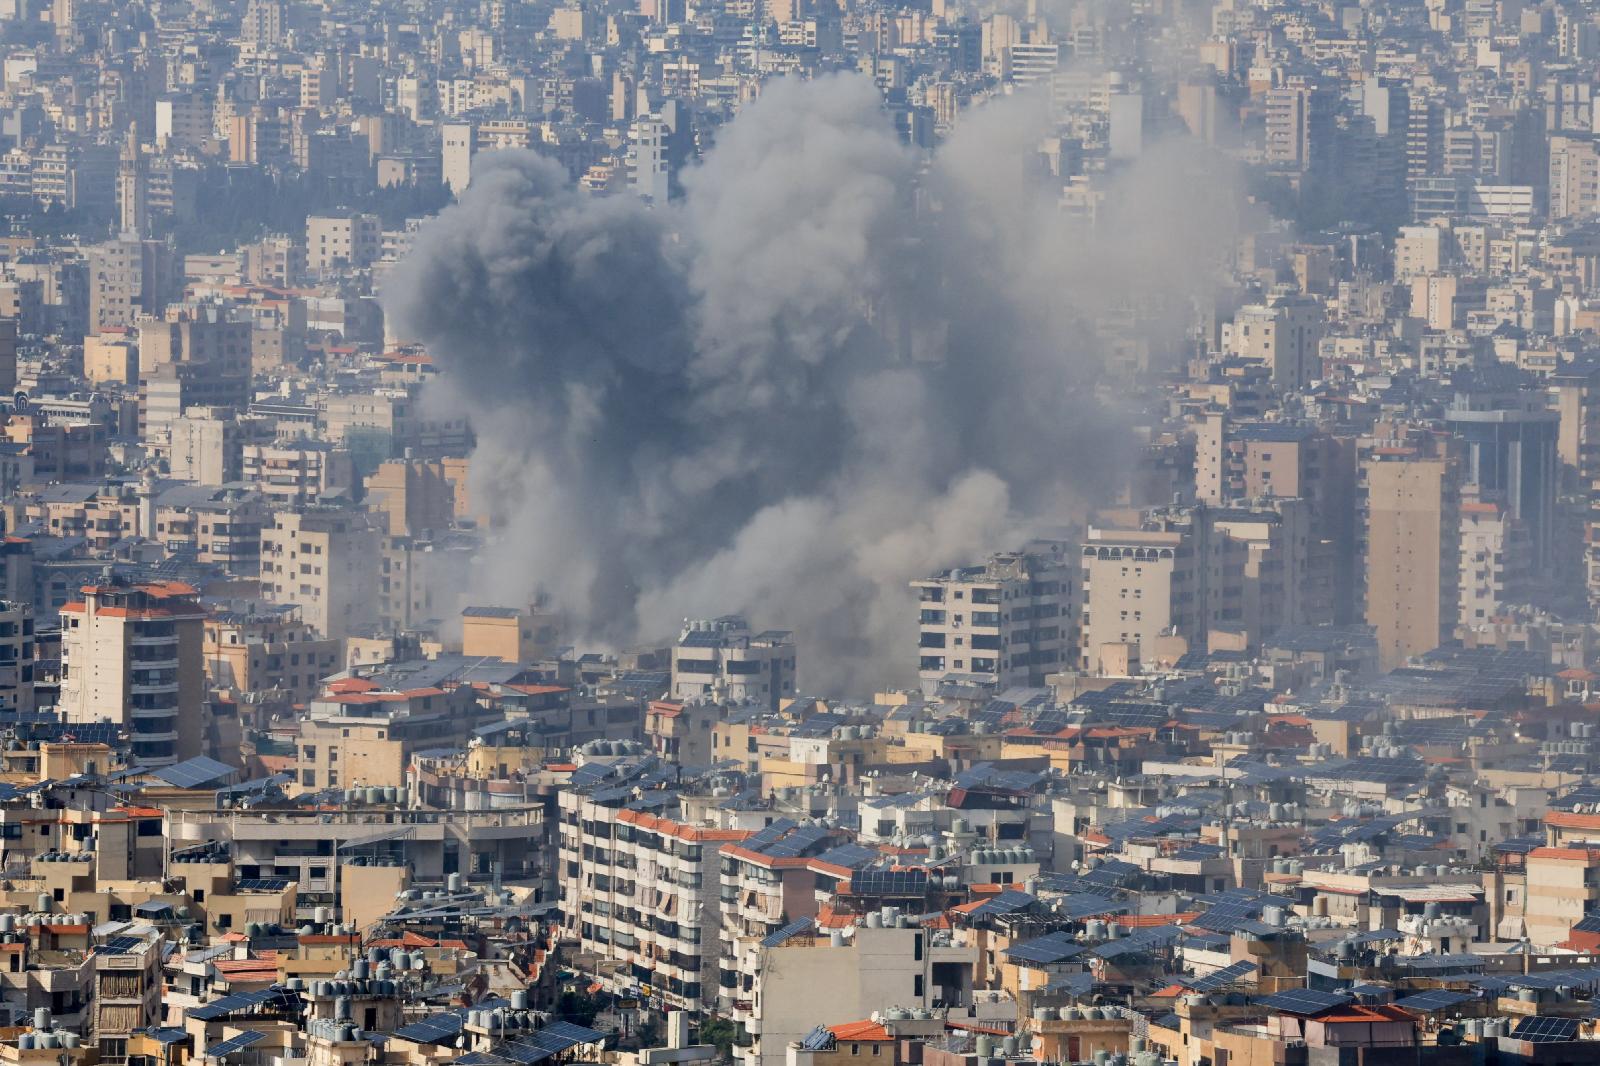
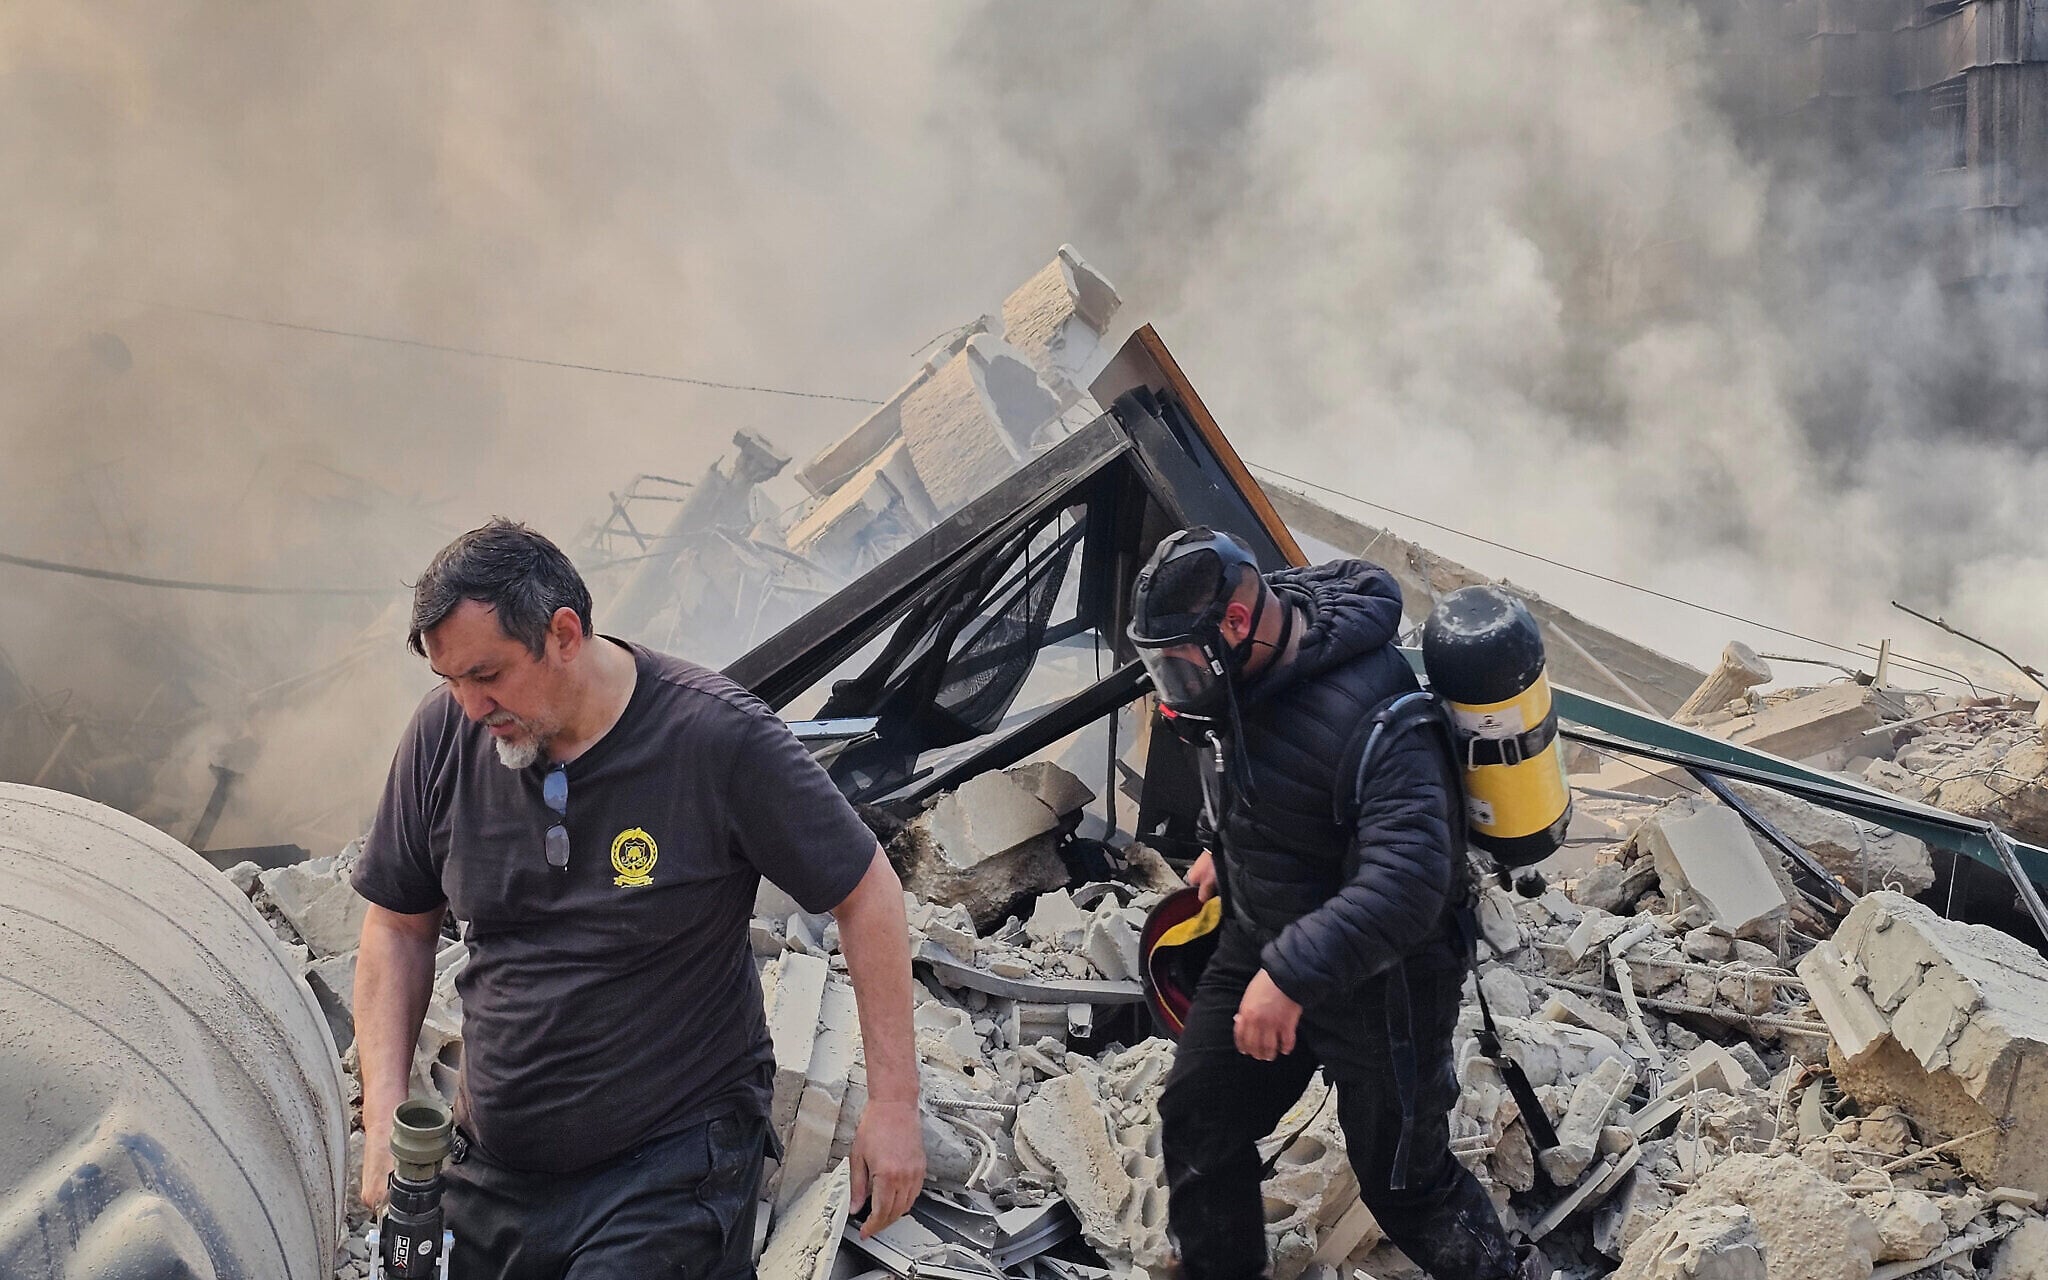
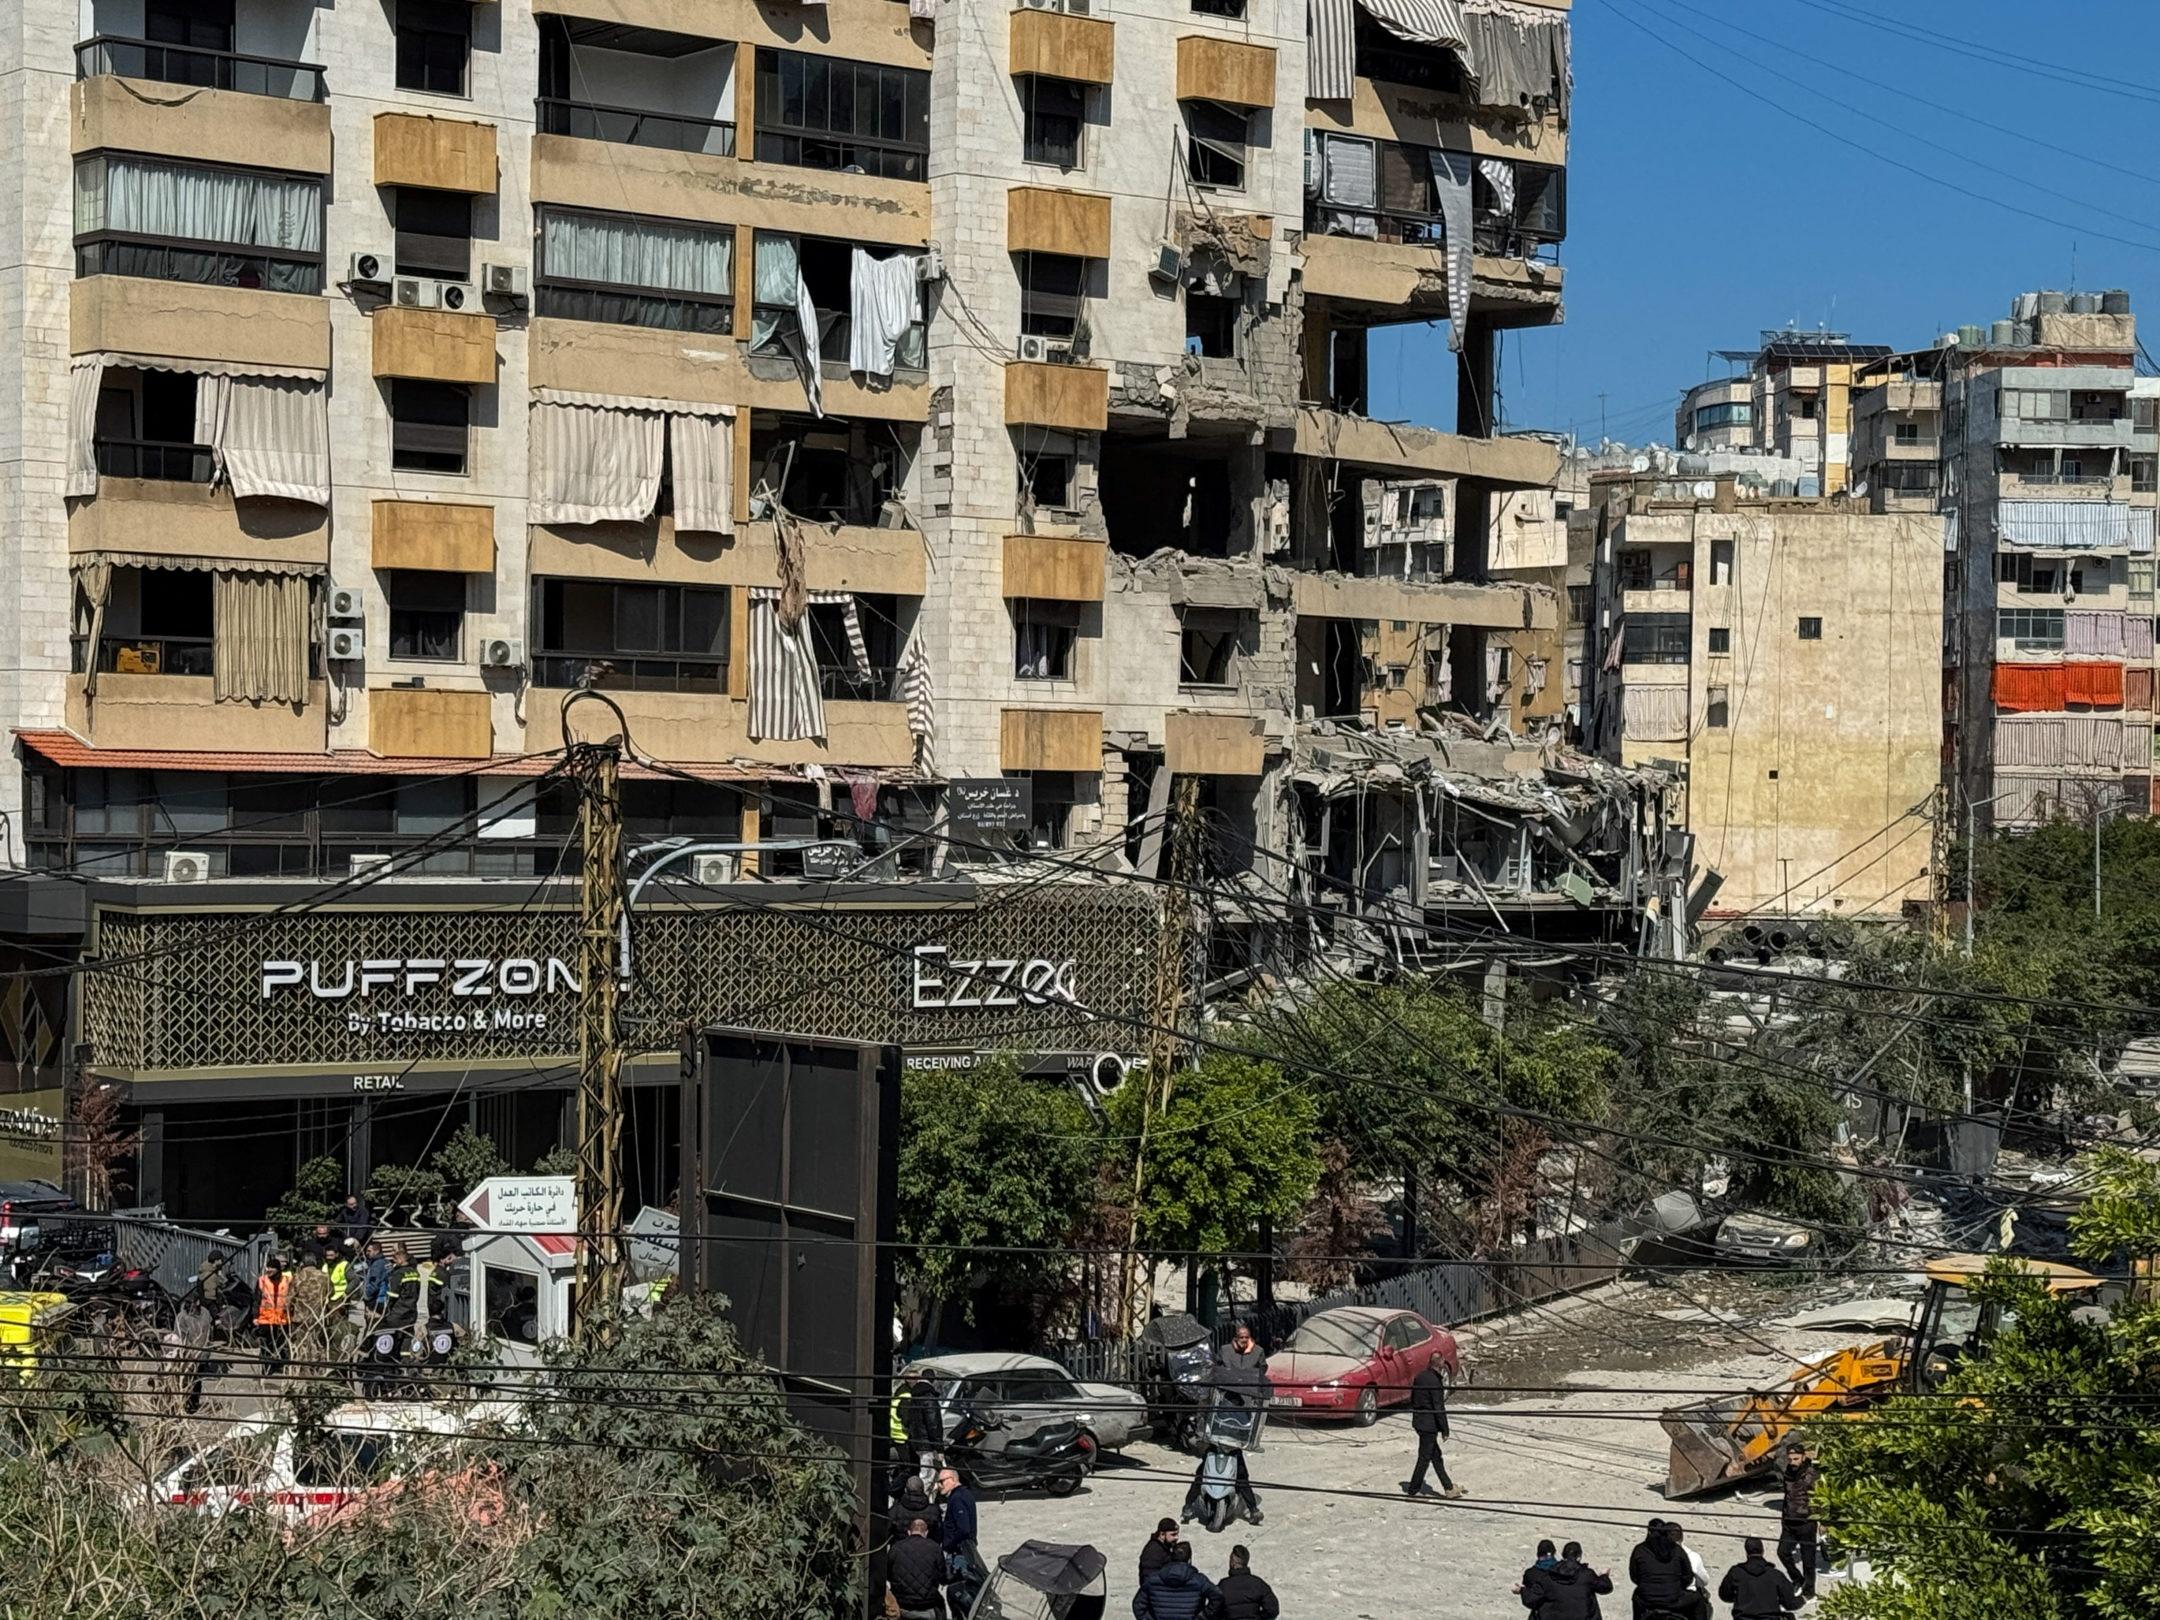
Market Access Shifts: The Middle East conflict escalation (Hezbollah attacks on Tel Aviv, Israeli airstrikes on 60+ Lebanon targets) directly impacts sellers shipping to Israel, UAE, and Saudi Arabia. Payment processing delays through Middle Eastern banks are already extending 5-7 days beyond normal timelines. Sellers should immediately audit their customer base in conflict-adjacent regions (Lebanon, Iran, Syria) and prepare for potential payment gateway restrictions. Historical precedent: 2019 Iran sanctions reduced cross-border e-commerce volume to Iran by 92% within 60 days.
Competitive Dynamics: Large 3PL providers (DHL, FedEx, UPS) are already adjusting routing algorithms to avoid Mediterranean conflict zones, increasing shipping costs 12-18% for sellers using standard transatlantic corridors. Small and medium sellers (annual revenue $500K-$5M) lack negotiating power to secure preferential rates, creating a competitive advantage for enterprise sellers with dedicated logistics contracts. This represents a 3-6 month window before shipping cost increases become permanent market pricing.
Strategic Sourcing Implications: Sellers currently sourcing from Spain (automotive parts, industrial equipment, fashion) face immediate inventory decisions. Vietnam and India represent viable alternatives with 4-6 week lead time adjustments, but require new supplier vetting and quality assurance protocols. The cost differential between Spanish and Vietnamese sourcing is currently 8-12%, making this a critical decision point before tariff uncertainty crystallizes into formal policy.
Compliance and Risk Mitigation: Sellers must immediately review their Spain-origin inventory for tariff classification accuracy (HS codes 8401-8517 face highest risk). Implement dual-sourcing strategies for high-volume SKUs within 45 days. Monitor USTR.gov and EU trade commission announcements for formal tariff schedules. Establish contingency payment processing through alternative gateways (Wise, Stripe) for Middle Eastern customers to mitigate banking delays.
Questions 8
How does Mediterranean logistics disruption affect shipping costs for cross-border sellers?
3PL providers are already adjusting routing algorithms to avoid conflict zones, increasing transatlantic shipping costs 12-18% for sellers using standard Mediterranean corridors. Large sellers with dedicated logistics contracts can negotiate preferential rates; small-medium sellers face permanent cost increases within 3-6 months as market pricing adjusts. Sellers should immediately audit their 3PL contracts for rate lock provisions and negotiate volume commitments to secure current pricing. Alternative routing through northern European ports (Rotterdam, Hamburg) adds 3-5 days to lead times but may offer cost savings of 4-6% versus Mediterranean routes.
What timeline should sellers follow for implementing tariff mitigation strategies?
Days 1-15: Audit Spain-origin inventory, verify HS codes, calculate tariff exposure. Days 15-30: Identify alternative suppliers (Vietnam, India, Poland), request quotes, initiate supplier vetting. Days 30-45: Negotiate dual-sourcing agreements, lock in pricing, adjust inventory positioning. Days 45-90: Implement alternative payment gateways, establish Middle East customer compliance protocols, monitor USTR announcements for formal tariff schedules. This 90-day window represents the critical decision period before tariff uncertainty becomes formalized policy and competitive advantages disappear.