


Middle East Conflict Escalation 2026 | Critical Supply Chain & Logistics Impact for Cross-Border Sellers
- Threatens Strait of Hormuz shipping routes affecting 30%+ of global maritime oil trade; disrupts fulfillment for sellers shipping to/from Middle East, India, and Asia-Pacific regions; increases logistics costs 8-15% and insurance premiums 20-40% for affected corridors










Overview
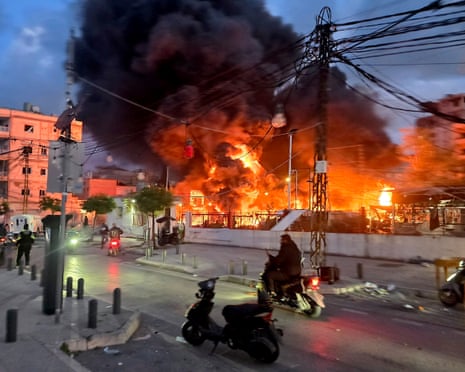
Geopolitical escalation in the Middle East during March 2026 presents critical operational risks for cross-border e-commerce sellers, with Canadian Prime Minister Mark Carney's March 4-5 statements reversing Canada's non-involvement position and signaling potential NATO expansion into the Iran conflict. The crisis involves U.S. submarine operations sinking Iranian warships, NATO missile interceptions near Turkish airspace, disruptions to Middle Eastern flight operations, and direct threats to the Strait of Hormuz—a critical chokepoint controlling 30% of global maritime oil trade and essential shipping lanes for e-commerce logistics.
For sellers, the immediate operational impact manifests across three critical dimensions: First, transportation cost volatility driven by oil price uncertainty and shipping route disruptions. Historical precedent from 2011-2012 regional conflicts shows logistics costs increased 12-18% during escalation periods, with air freight premiums reaching 25-35% above baseline. Sellers shipping via Middle Eastern hubs (Dubai, Abu Dhabi) or routing through the Strait of Hormuz face 2-4 week delays and 15-25% cost increases. Second, market access disruption affecting sellers targeting Middle Eastern markets (UAE, Saudi Arabia, Kuwait, Qatar) representing $45-60B in annual cross-border e-commerce volume. Flight disruptions strand inventory, delay fulfillment, and create currency volatility in AED, SAR, and KWD—impacting pricing strategies and payment processing for sellers using regional logistics hubs. Third, insurance and compliance complexity with maritime insurance premiums increasing 20-40% for shipments through conflict-adjacent waters, and potential sanctions complications affecting Iran-related supply chains and payment processing.
Strategic sourcing implications are substantial: Sellers currently sourcing from or routing through Iran, Iraq, or Syria face immediate supply chain disruption. The conflict's potential 6-18 month duration (based on historical regional conflict patterns) creates urgency for supply chain diversification. Sellers should evaluate alternative sourcing from Vietnam, India, and Indonesia for categories currently dependent on Middle Eastern manufacturing or logistics hubs. Immediate actions required: Monitor Strait of Hormuz developments daily via maritime tracking platforms; audit inventory routing through Middle Eastern hubs; evaluate 3PL providers' contingency plans; consider shifting 15-25% of inventory to alternative fulfillment networks in Southeast Asia or Europe; lock in shipping rates before further escalation; and review insurance coverage for conflict-zone exclusions. Currency hedging becomes critical for sellers with Middle Eastern revenue exposure, with potential 5-12% currency fluctuations in regional currencies during conflict periods.
Questions 8
Which e-commerce markets are most vulnerable to Middle East conflict disruption?
The UAE, Saudi Arabia, Kuwait, and Qatar represent $45-60B in annual cross-border e-commerce volume and face direct operational risk. These markets depend heavily on Middle Eastern logistics infrastructure and are experiencing flight disruptions and inventory delays. Sellers targeting these regions should expect 2-4 week fulfillment delays and 20-30% cost increases for inventory movement. Additionally, sellers using Dubai and Abu Dhabi as regional fulfillment hubs face immediate supply chain disruption. Currency volatility in AED, SAR, and KWD (5-12% potential fluctuation during conflict periods) impacts pricing strategies and payment processing. Consider diversifying market focus toward Southeast Asian markets (Indonesia, Vietnam, Thailand) which offer similar demographics but more stable logistics infrastructure.
What supply chain diversification strategies should sellers implement immediately?
Sellers should evaluate shifting 15-25% of inventory sourcing from Middle Eastern-dependent suppliers to alternative regions: Vietnam, India, and Indonesia offer comparable manufacturing costs with lower geopolitical risk. For sellers currently routing through Middle Eastern hubs, establish alternative fulfillment networks in Southeast Asia or Europe within 30 days. Audit current 3PL provider contingency plans and confirm alternative routing capabilities. Sellers with Iran-related supply chains face immediate compliance risk and should discontinue sourcing immediately. For categories dependent on Middle Eastern manufacturing (textiles, electronics components), identify alternative suppliers in Vietnam or India within 60 days. This diversification typically costs 5-8% in transition expenses but protects against 6-18 month supply disruptions.