


Iran Conflict Reverses "Sell America, Buy Asia" Strategy | Shipping Costs Rise 3-8% for Cross-Border Sellers
- MSCI Asia Pacific Index drops 6% while US dollar strengthens; Wizz Air profit warning signals 8.62% capacity constraints; oil prices surge 2.33-3.08%; sellers face $200-400/month increased logistics costs













Overview
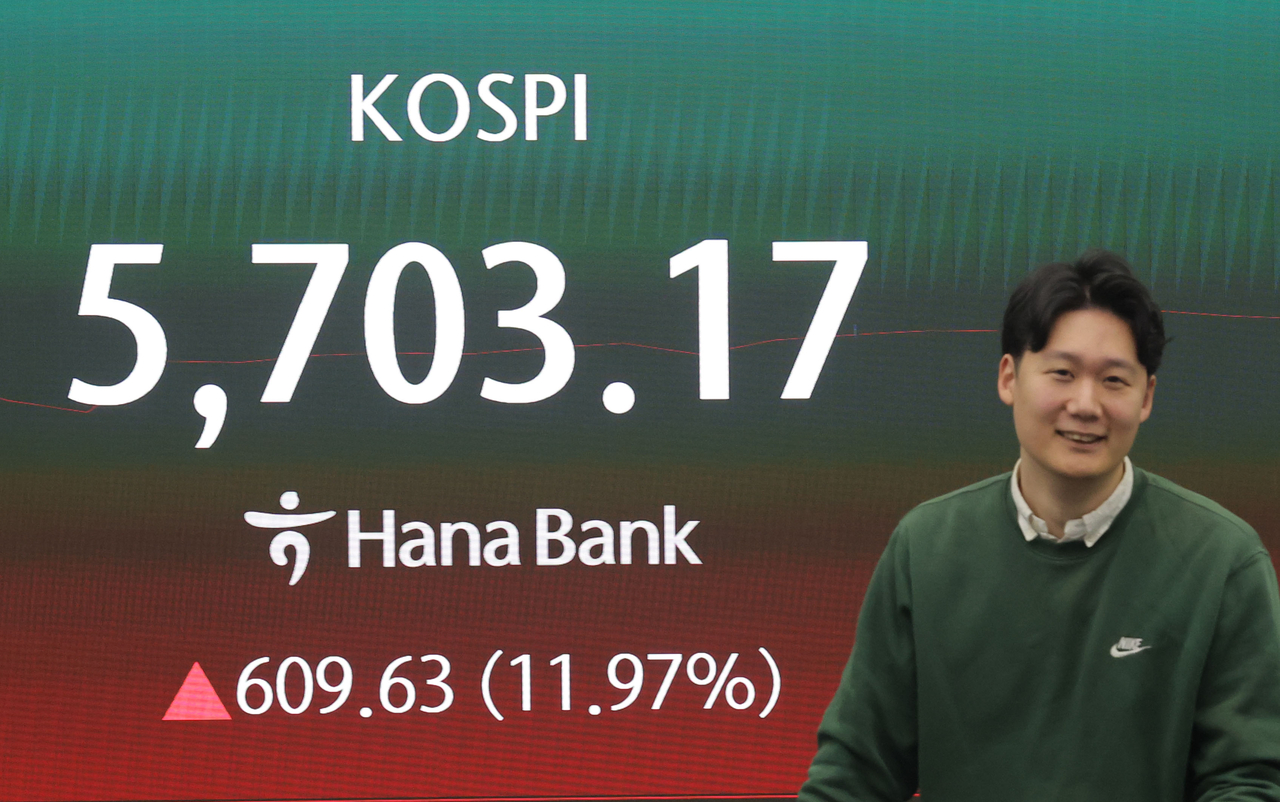
The Iran-Israel conflict is fundamentally reshaping global capital flows and e-commerce supply chain economics. As of March 5, 2026, Bloomberg reported that geopolitical tensions have triggered a dramatic reversal of the "Sell America, Buy Asia" investment strategy that dominated institutional capital allocation for years. The MSCI Asia Pacific Index declined 6% during the week while the S&P 500 fell only 0.1%, signaling a massive flight-to-safety rotation. This capital reallocation, combined with a strengthening US dollar and rising energy costs, creates a critical inflection point for cross-border e-commerce sellers operating across multiple regions.
For US-based sellers importing from Asia, the operational impact is immediate and severe. The strengthening dollar increases import costs by 3-5% for goods sourced from China, Vietnam, and India—the primary sourcing regions for electronics, apparel, and consumer goods categories. Simultaneously, Wizz Air's 8.62% stock decline and profit warning signal tightening capacity in European air freight networks, with logistics providers implementing fuel surcharges as crude oil prices advanced 3.08% and Brent crude gained 2.33%. Sellers relying on expedited air freight to European fulfillment centers face cost increases of $200-400 monthly for standard shipment volumes (500-1000 units). The Strait of Hormuz remains a critical chokepoint, with ongoing vessel strike reports threatening maritime shipping routes that handle 30% of global seaborne trade.
The capital reallocation away from Asian markets creates secondary supply chain disruptions. Reduced institutional investment in Asian e-commerce infrastructure and logistics networks signals potential underinvestment in port capacity, warehouse automation, and last-mile delivery systems. This translates to longer lead times (estimated 2-4 weeks additional delay for ocean freight) and reduced shipping frequency on Asia-to-US and Asia-to-Europe corridors. Sellers with heavy inventory exposure in Asian warehouses face potential storage cost increases as logistics providers optimize for reduced volume. Currency volatility compounds these challenges—EURUSD moved to 1.1630 and USDJPY to 157.20—creating pricing friction for sellers managing multi-currency inventory and pricing strategies across Amazon, eBay, and Shopify storefronts.
Strategic sourcing shifts are already underway. Sellers previously dependent on China-based manufacturing are accelerating diversification to Vietnam, India, and Mexico to reduce single-country geopolitical risk. This creates temporary cost premiums (5-12% higher unit costs during transition) but offers long-term supply chain resilience. Categories most affected include electronics (HS 8471-8517), apparel (HS 6204-6209), and consumer goods (HS 9406-9406), which collectively represent $180B+ in annual cross-border e-commerce volume. The timing window for supply chain repositioning is critical—sellers who delay face compounding logistics costs and potential stockouts during Q2-Q3 peak selling seasons.
Questions 8
What is the timeline for supply chain repositioning away from China?
The optimal repositioning window is 60-90 days before peak Q2-Q3 selling seasons (April-August). Sellers who delay face compounding logistics costs and potential stockouts. Vietnam and India offer 5-12% higher unit costs during transition but provide long-term geopolitical risk reduction. Mexico offers nearshoring advantages for US sellers with 2-3 week lead times versus 6-8 weeks from Asia. Sellers should initiate supplier qualification immediately, with target completion by April 15, 2026, to allow 4-6 weeks for production ramp-up before peak season.
How should sellers adjust pricing strategies amid currency volatility?
EURUSD moved to 1.1630 and USDJPY to 157.20, creating pricing friction across Amazon, eBay, and Shopify storefronts. Sellers should implement dynamic pricing strategies that adjust for real-time currency fluctuations rather than static monthly updates. For Amazon sellers, this means reviewing pricing rules in Seller Central to account for 2-3% daily currency swings. Sellers exporting to Europe benefit from the weaker dollar (higher EUR revenue), while US importers face margin compression. Consider implementing currency hedging through forward contracts for 30-60% of projected monthly imports.