




Oil Price Surge Crushes E-Commerce Margins | Sellers Face 8-12% Shipping Cost Increases Through Q1 2025
- Strait of Hormuz closure triggers $63-$94 barrel spike; shipping costs rise 2-3% per $10 barrel increase; demand contraction expected for non-essential categories through 2026








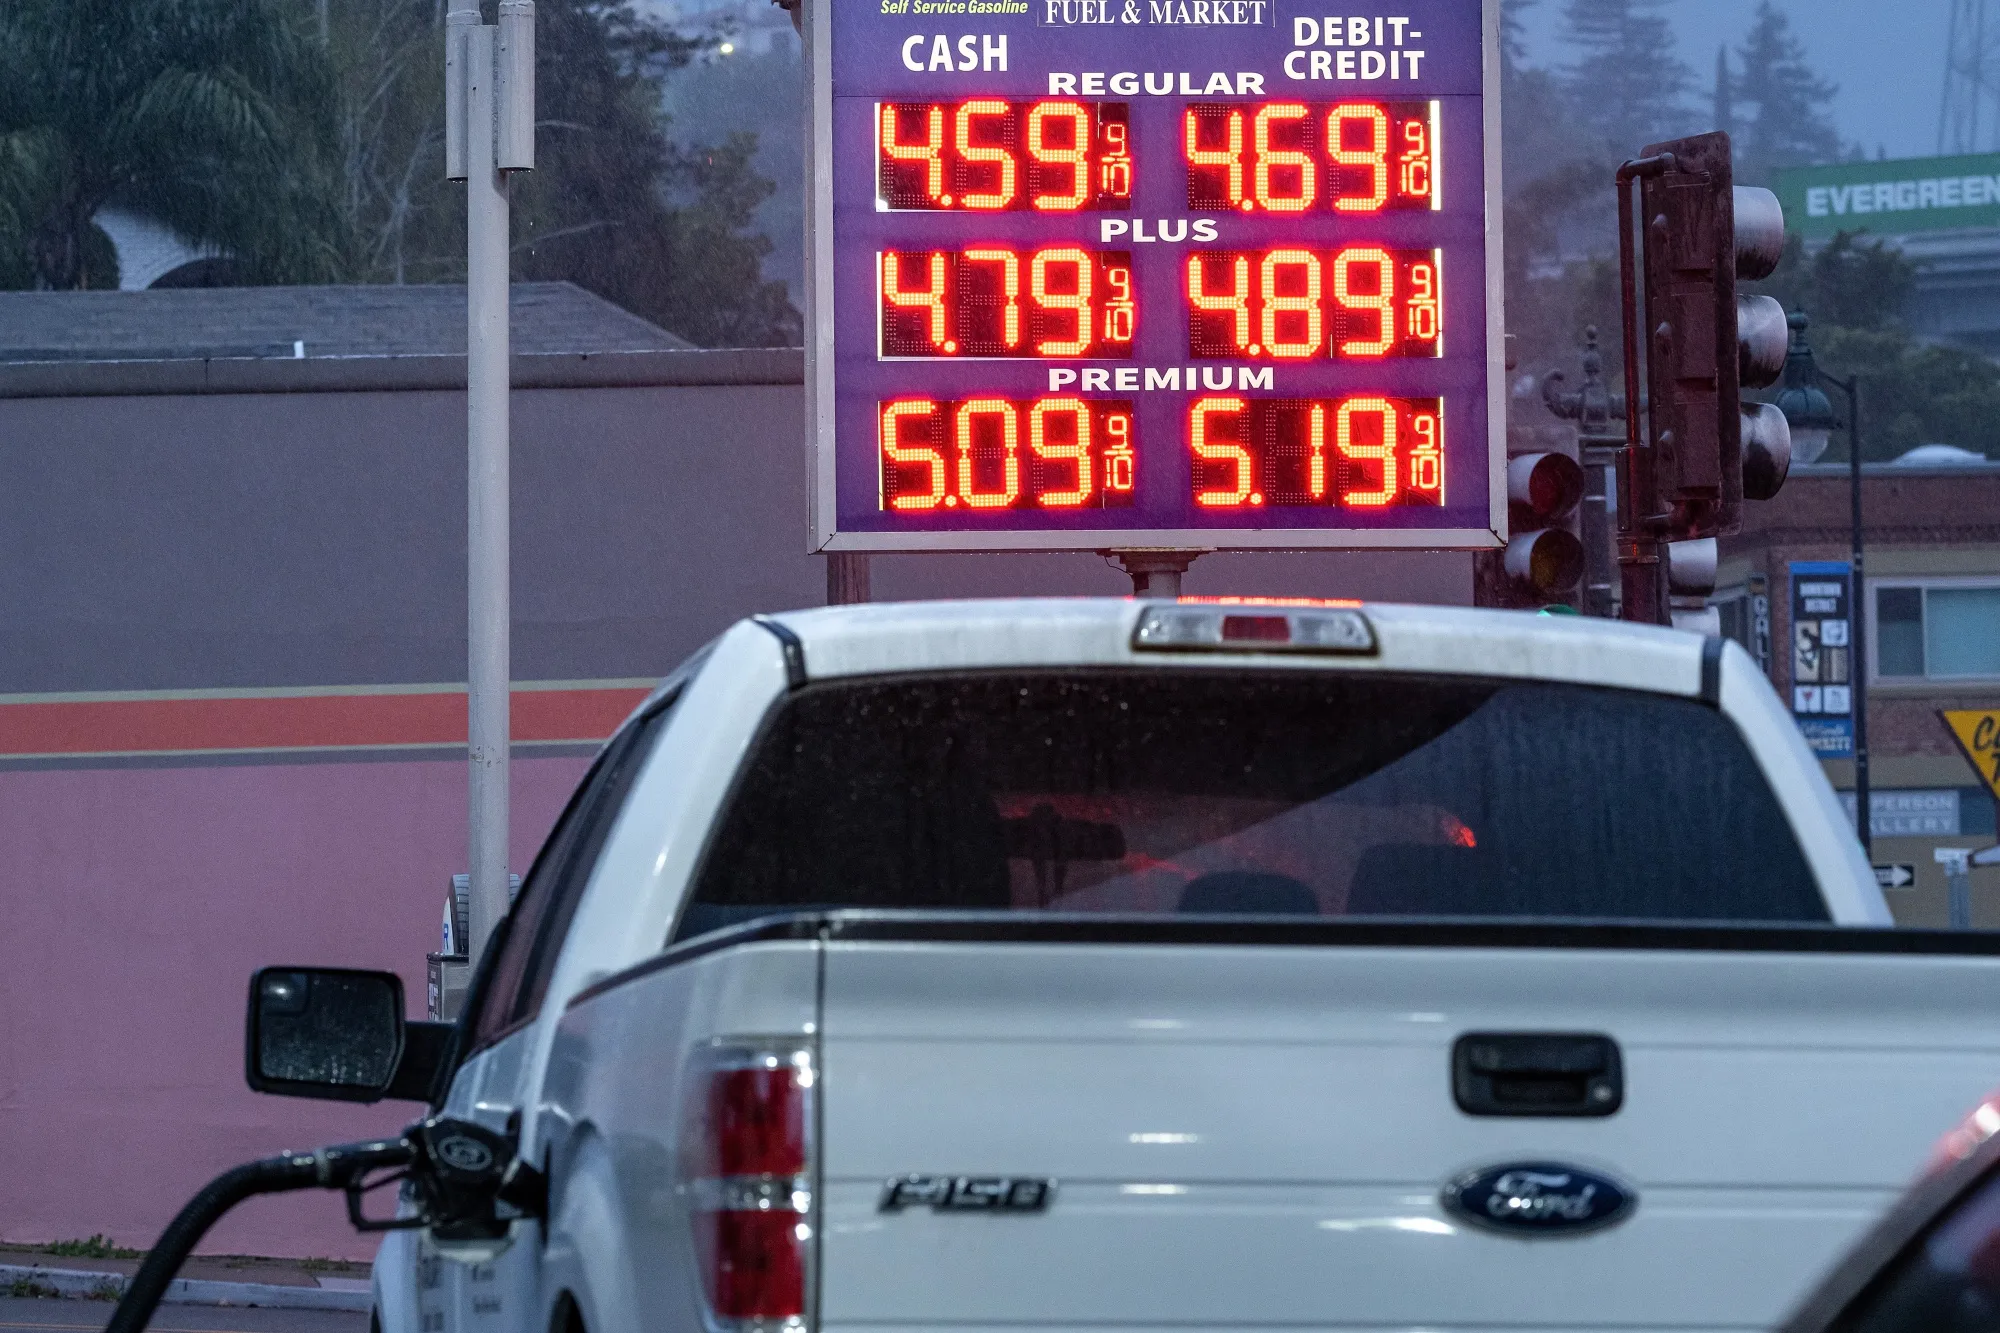
Overview
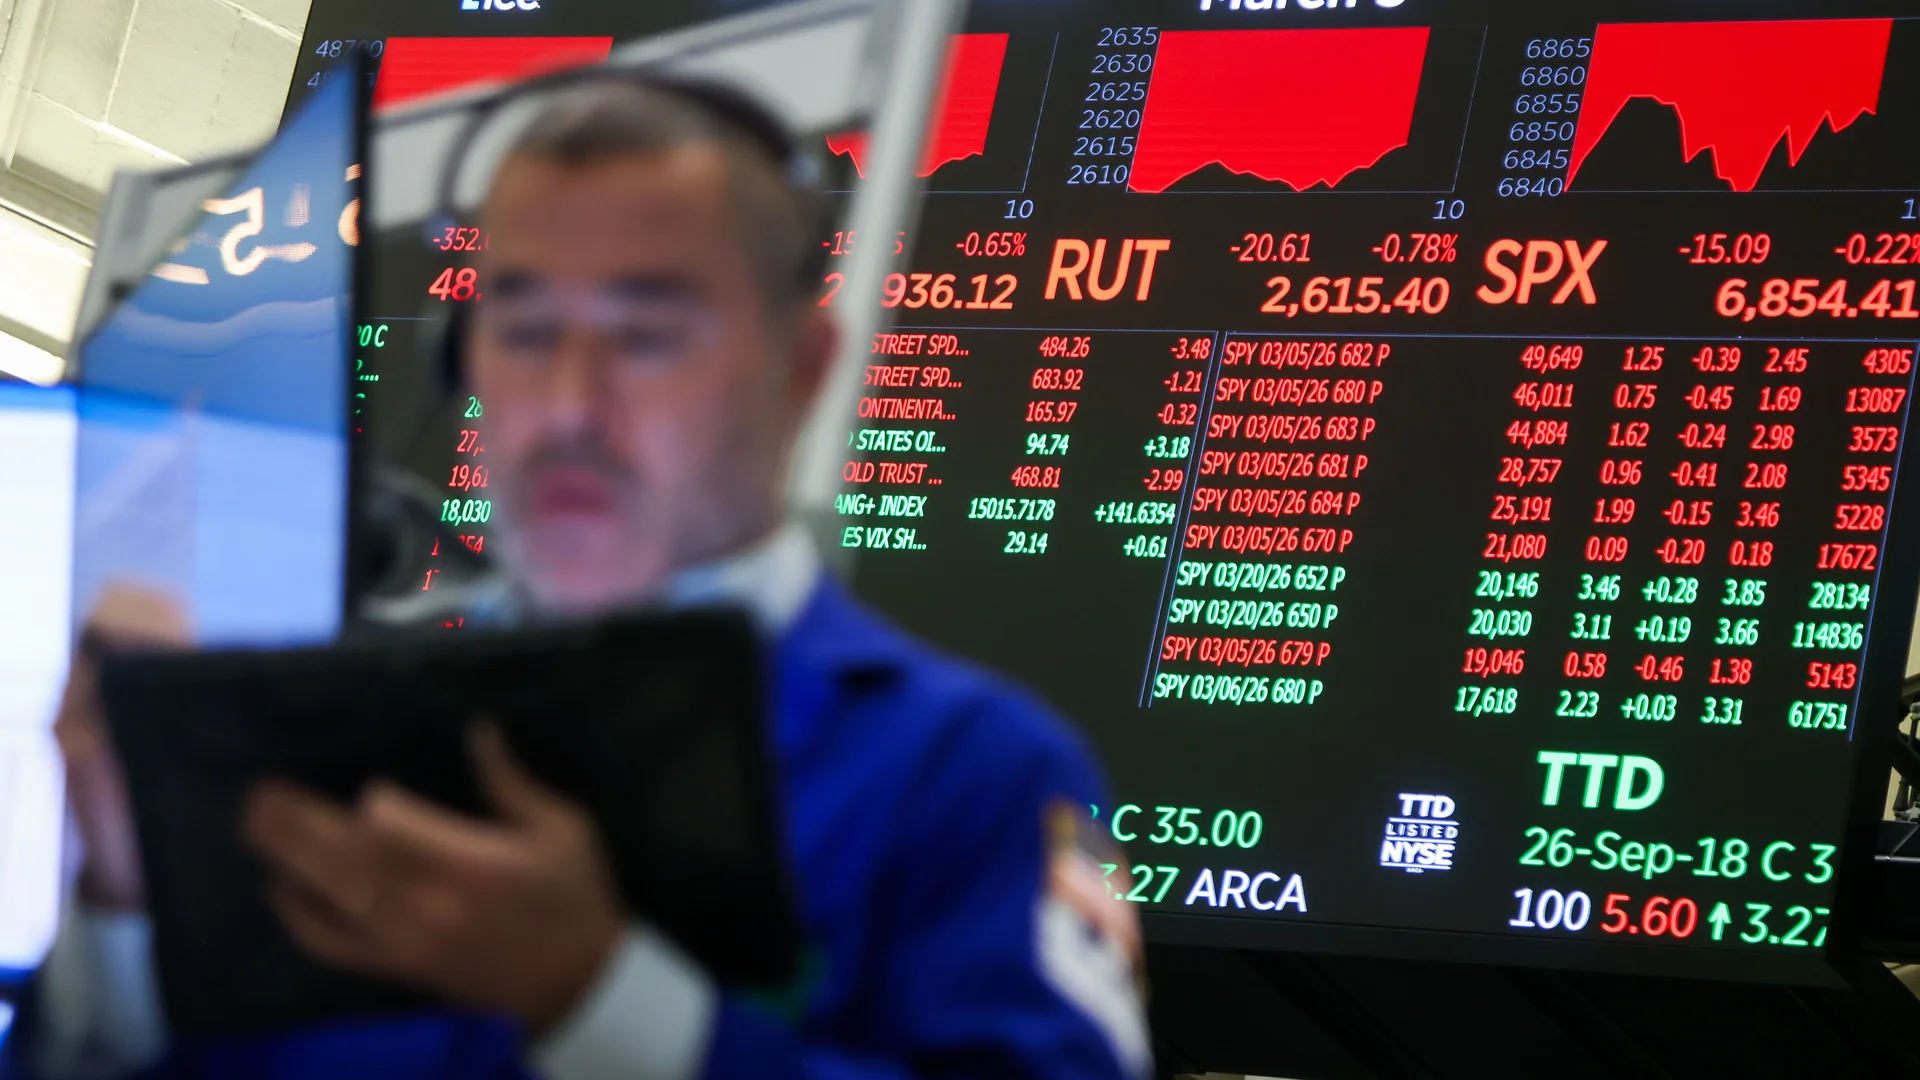
The Middle Eastern geopolitical crisis has created a dual-shock scenario for cross-border e-commerce sellers: immediate cost pressures colliding with predicted demand destruction. Within one week, crude oil prices surged from $63 to $94 per barrel following the closure of the Strait of Hormuz—which handles 21% of global petroleum trade—while UK natural gas costs nearly doubled from 74 pence to 1.35 per therm. This represents the most severe energy shock since September 2023. Economist David Rosenberg's March 7, 2026 analysis predicts inflation will "come crashing down by year-end" as elevated oil prices compress consumer purchasing power, triggering demand reduction that ultimately drives deflation. However, this creates a margin-squeeze trap for sellers: wholesale costs remain elevated while retail prices decline, particularly affecting non-essential categories.
For logistics-dependent sellers, the immediate impact is quantifiable and severe. A $10 increase in barrel prices translates to 2-3% increases in freight costs within weeks, affecting fulfillment expenses, last-mile delivery charges, and overall supply chain economics. Sellers shipping 1,000+ units monthly face $200-400 monthly cost increases. UK government bond yields (gilt rates) increased from 4.4% to 4.6%, approaching 4.7%, signaling delayed interest rate cuts and increased borrowing costs for sellers seeking working capital. The pattern of attacks on regional infrastructure—from Bahrain's oil facilities to Qatar's gas processing and Dubai port operations—suggests sustained rather than temporary disruption, with Trump's indication of weeks-to-months conflict duration suggesting these pressures persist through Q1 2025.
The demand-side risk is equally critical but less immediately visible. Real wage growth has declined to roughly 1% annually (halved from prior-year levels), while real GDP growth slowed to 1.4% annualized in Q4. M2 money supply growth stagnated at approximately 4% annually, indicating limited inflationary pressure. This combination signals consumer retrenchment: mortgage holders will delay discretionary spending as the Bank of England pauses interest rate cuts, reducing demand for non-essential goods that many cross-border sellers depend upon. Historical precedent supports this thesis—the 2022 Ukraine invasion oil spike preceded rapid inflation cooling as consumers retrenched, and the 2008 oil surge to $150 coincided with headline inflation dropping from 7.9% to 2.6% within one quarter. Sellers with fixed pricing models face margin compression from both directions: rising input costs and falling retail prices.
Questions 8
How should I adjust my inventory strategy given demand contraction predictions?
Reassess inventory levels immediately given reduced consumer spending expectations. Real wage growth has declined to 1% annually, and the Bank of England's anticipated pause on interest rate cuts means mortgage holders will delay discretionary spending. Reduce exposure to non-essential categories and increase inventory turnover velocity to minimize working capital tied up in slow-moving stock. Implement just-in-time inventory practices where feasible to reduce carrying costs during the inflationary period. Monitor your Inventory Performance Index (IPI) score closely—Amazon penalizes excess inventory with storage fees that will increase due to elevated warehouse operating costs. Consider shifting 20-30% of inventory to 3PL providers with better cost structures, and focus on fast-moving essential categories with predictable demand patterns.
What borrowing costs should I expect if I need working capital during this period?
UK government bond yields (gilt rates) increased from 4.4% to 4.6%, approaching 4.7%, signaling market expectations of prolonged inflation and delayed interest rate cuts from the Bank of England. This directly impacts cross-border sellers through increased borrowing costs for working capital. If you typically borrow at prime rate + 2-3%, expect your effective borrowing costs to increase by 20-40 basis points (0.2-0.4%) in the near term. For a $100,000 working capital line, this translates to $200-400 additional annual interest expense. Evaluate alternative financing options: supplier payment terms, invoice factoring, or equity financing may be more cost-effective than traditional bank borrowing during this period. Prioritize cash flow management and reduce working capital requirements through faster inventory turnover.