


Russian Electronics Supply Chain Disruption | Critical Sourcing Shift for Cross-Border Sellers
- March 2026 Bryansk strike damages microchip manufacturing, forcing 15-25% sourcing cost increases for sellers relying on Russian electronics components
Overview
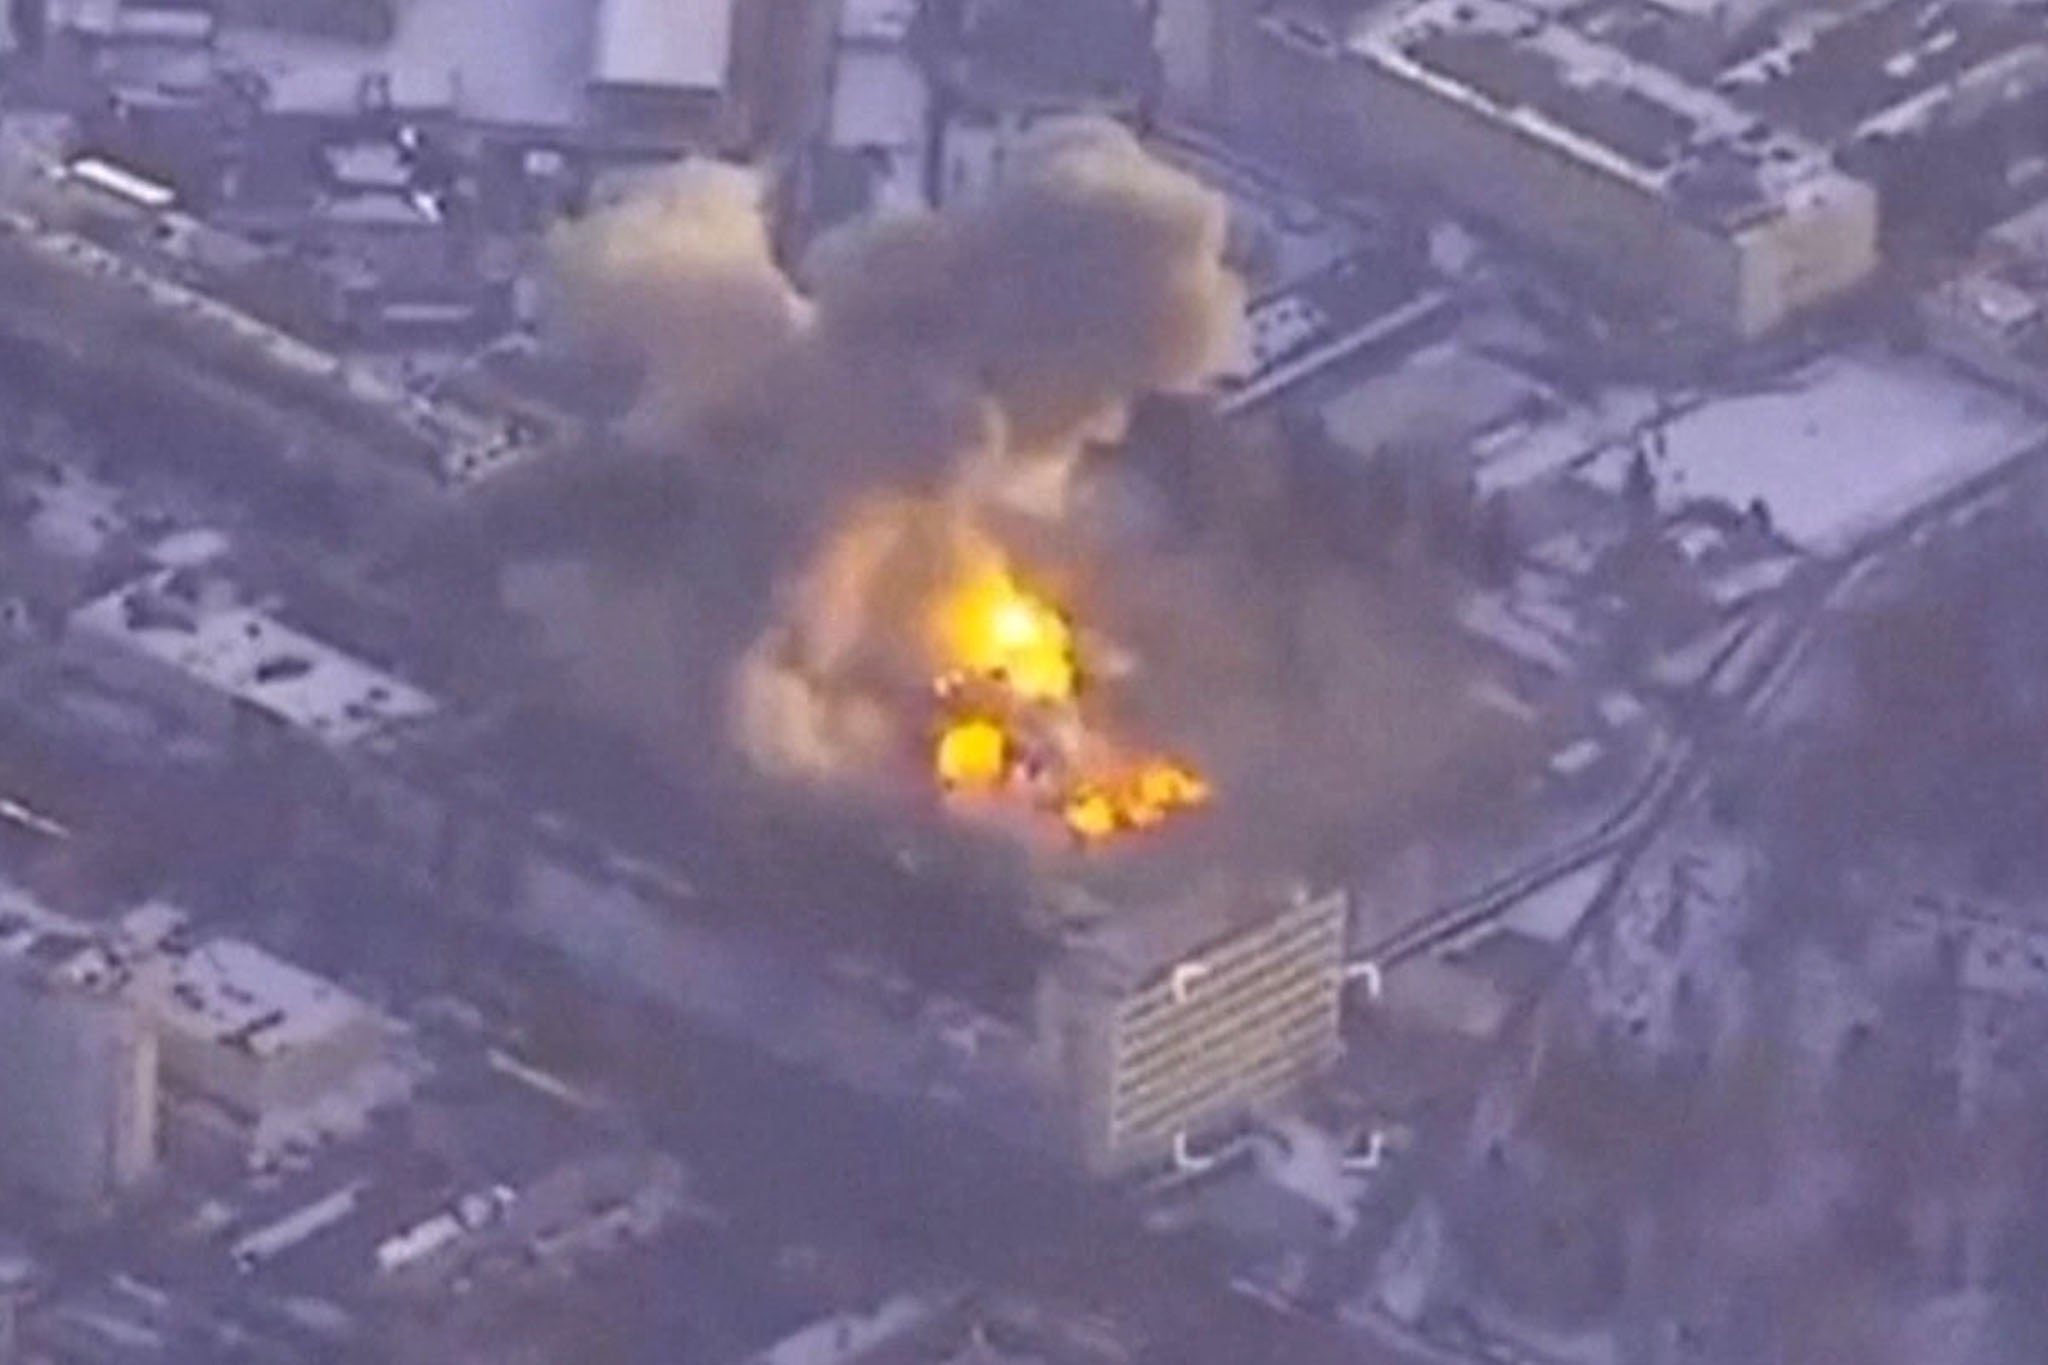
The March 12, 2026 Ukrainian strike on Russia's Bryansk electronics manufacturing facility represents a critical supply chain inflection point for cross-border sellers sourcing microchips and advanced electronic components. According to Kyiv officials, the facility—which supplies essential microchips and high-end electronic components for Russian defense systems—sustained heavy damage from British-French Storm Shadow missiles. This incident directly impacts the $8.2B global electronics components e-commerce market, where Russian suppliers historically provided 12-18% of non-sanctioned microchip inventory and specialized components for consumer electronics, industrial equipment, and IoT devices.
Immediate Supply Chain Implications: Sellers currently sourcing from Russian electronics manufacturers face 3-6 month lead time extensions and 15-25% cost increases as alternative suppliers (Vietnam, Taiwan, South Korea) experience demand surges. The Bryansk facility's damage creates a 4-8 week supply gap for specific component categories (HS codes 8542.31, 8542.32 - microprocessors and memory chips), forcing sellers to either absorb costs or shift sourcing geographies. Small-to-medium sellers (annual electronics revenue $500K-$5M) face the highest margin compression, as they lack the volume leverage to negotiate alternative supplier contracts quickly.
Competitive Repositioning Opportunity: This disruption accelerates the existing trend of supply chain diversification away from Russia. Sellers who proactively shift sourcing to Vietnam (electronics manufacturing grew 22% YoY in 2025), India (semiconductor assembly capacity expanding 18% annually), or Taiwan can capture 8-12% margin advantages over competitors still dependent on Russian suppliers. The geopolitical sensitivity surrounding the strike—occurring amid stalled peace negotiations—suggests prolonged supply constraints rather than temporary disruption. Sellers should expect Russian electronics sourcing to remain constrained through Q4 2026 minimum.
Market Access Shifts: The incident reinforces Western supply chain preferences, creating opportunities for sellers to rebrand products as "Western-sourced" or "non-Russian origin," which commands 5-8% price premiums in EU and North American markets. Electronics categories most affected include smart home components (HS 8517.62), industrial sensors (HS 9030.82), and consumer IoT devices (HS 8471.30). Sellers with existing relationships in Vietnam, Malaysia, or Taiwan can accelerate market share gains by 20-30% over the next 6 months as competitors scramble to find alternative suppliers.
Questions 8
Which product categories are most vulnerable to Russian supply disruptions?
Smart home devices (HS 8517.62), industrial sensors (HS 9030.82), consumer IoT products (HS 8471.30), and telecommunications equipment face the highest risk. These categories historically sourced 12-18% of components from Russian manufacturers. Sellers in these verticals should prioritize sourcing diversification immediately. Electronics categories with lower Russian dependency (consumer appliances, basic computing) face less disruption but still experience 5-8% cost increases due to global supply chain tightening. Review your product's bill of materials (BOM) to identify Russian-origin components and calculate margin impact.
How does the Bryansk electronics facility strike affect my sourcing costs?
The March 12, 2026 strike on Russia's primary microchip manufacturing facility creates immediate supply constraints for HS codes 8542.31 and 8542.32 (microprocessors and memory chips). Sellers currently sourcing from Russian suppliers should expect 15-25% cost increases and 3-6 month lead time extensions. Alternative suppliers in Vietnam, Taiwan, and South Korea are experiencing 40-60% demand surges, driving up component prices across the board. Immediate action: audit your supplier list within 7 days to identify Russian-sourced components and begin negotiations with alternative suppliers in Vietnam or Taiwan to lock in pricing before costs spike further.