


High-Value Asset Liquidation & Investor Dispute Resolution | Seller Compliance Lessons
- Tommy Thompson's $50M treasure sale and 10-year legal battle reveal critical lessons for sellers managing high-value inventory, investor agreements, and cross-border asset transfers worth $2.5M+ in disputed goods












Overview
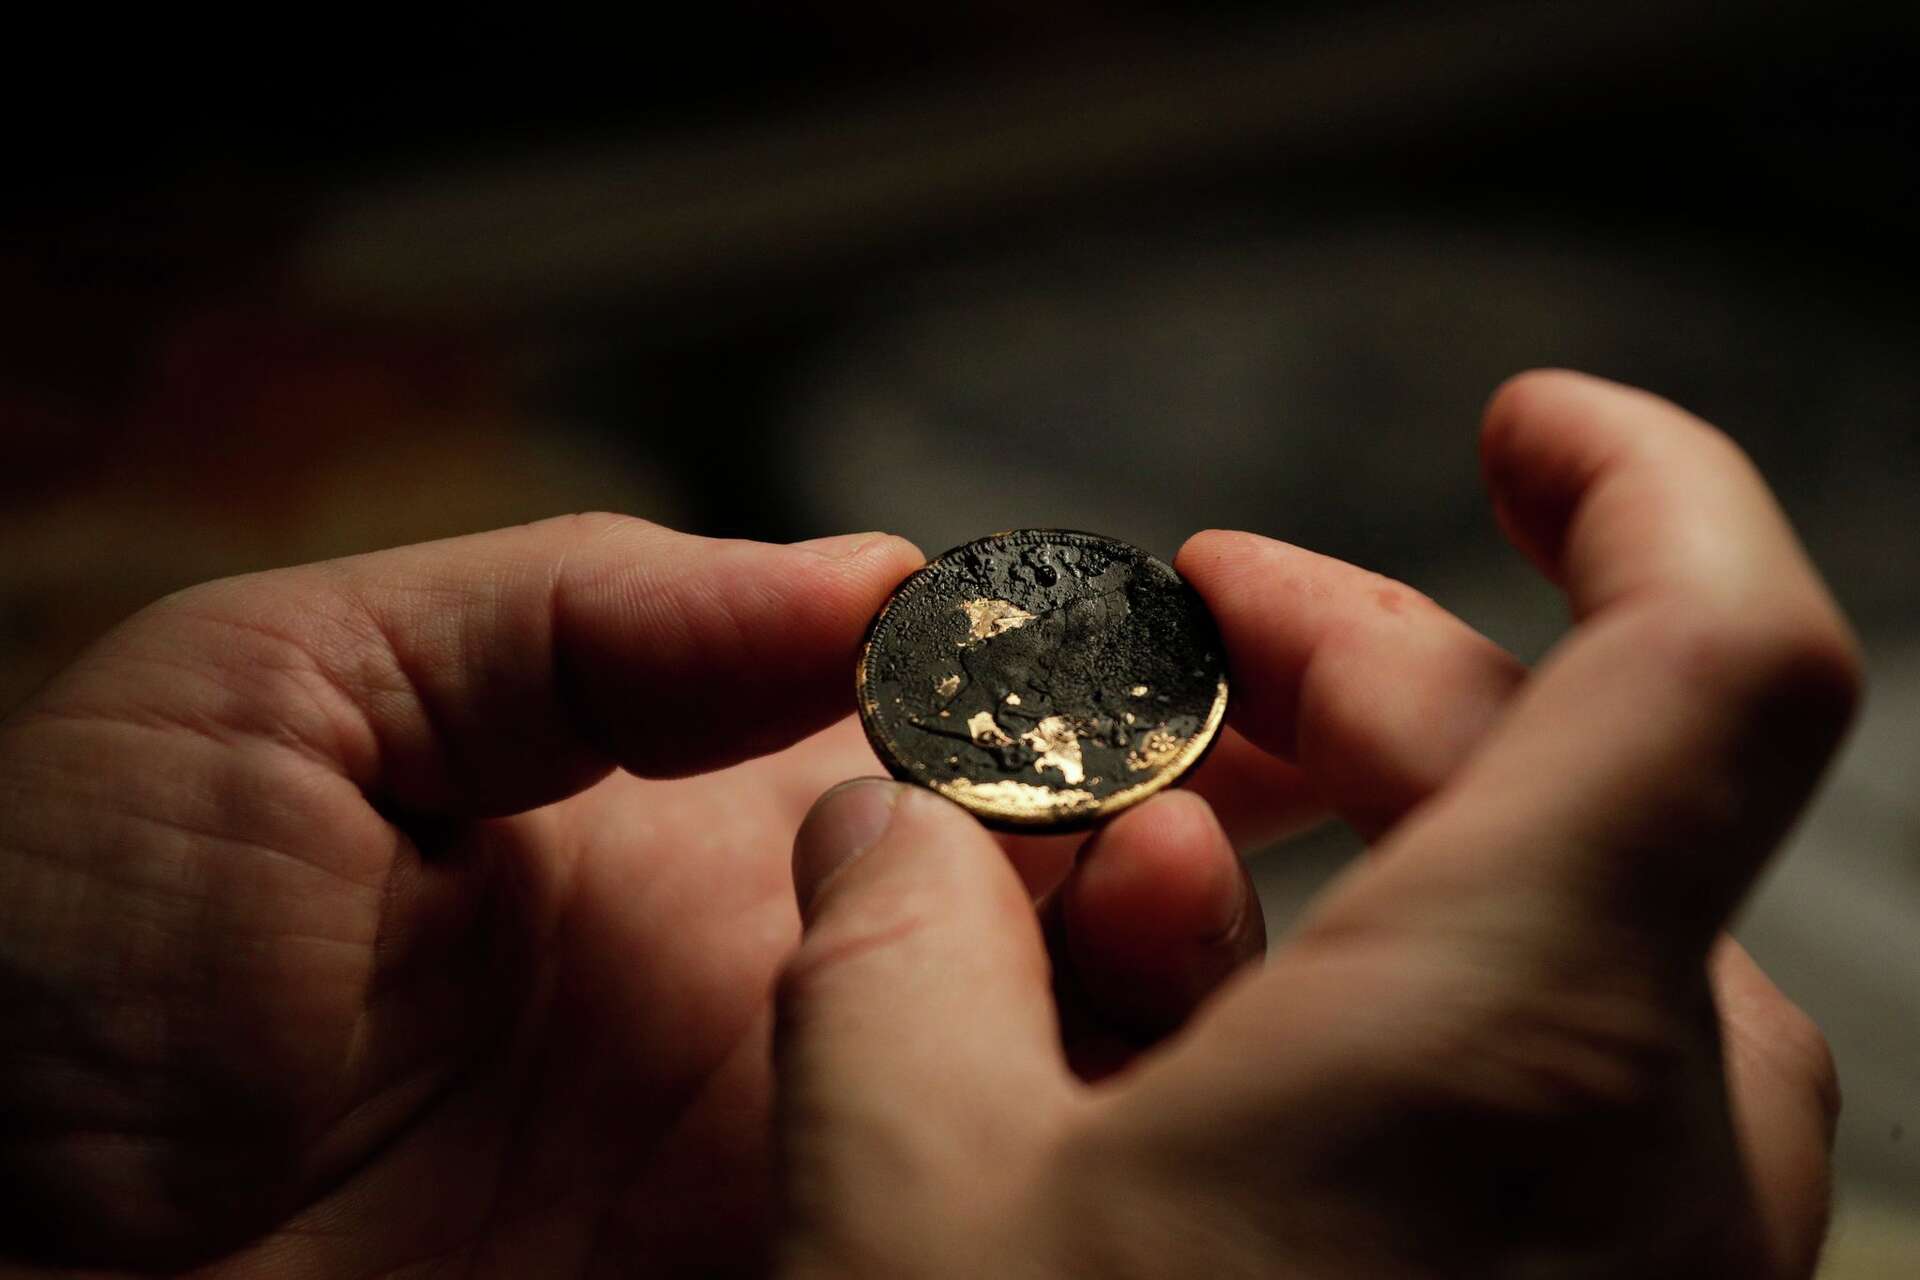
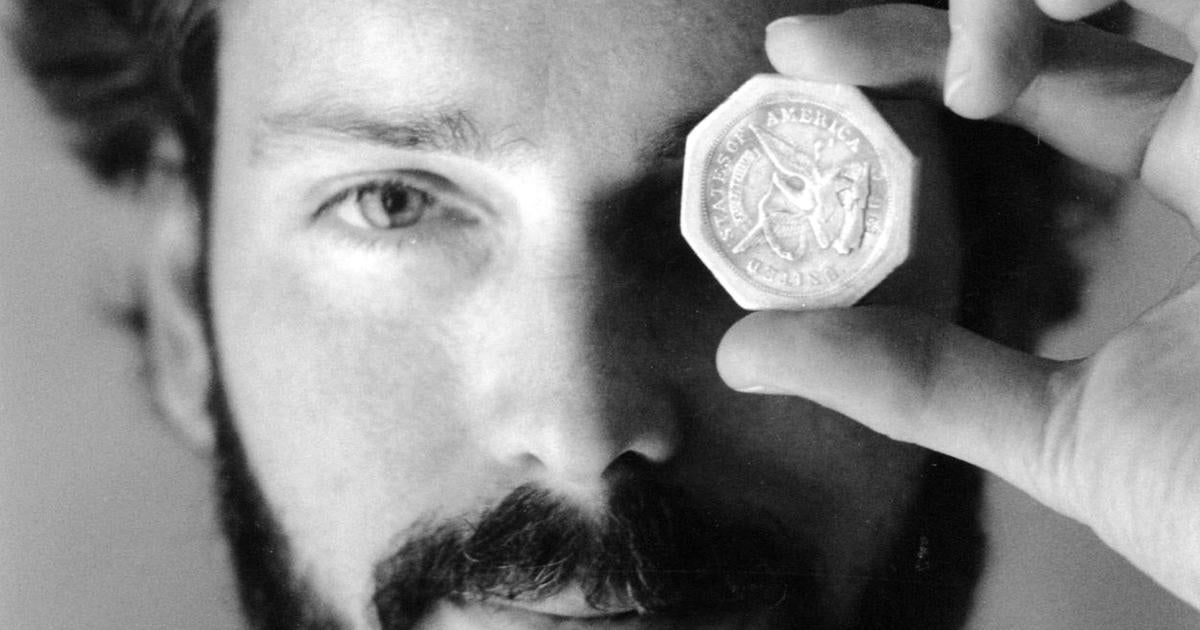
The release of 73-year-old treasure hunter Tommy Thompson after a decade-long imprisonment for contempt of court presents a compelling case study in asset disclosure obligations, investor protection frameworks, and cross-border financial compliance that directly parallels challenges facing high-volume e-commerce sellers managing significant inventory values and investor relationships. Thompson's case—involving a $50 million treasure sale from the S.S. Central America shipwreck discovered in 1988, with 500 commemorative gold coins valued at $2.5 million remaining in dispute—demonstrates the legal and financial consequences of inadequate transparency in high-value transactions.
The core issue mirrors e-commerce seller challenges: Thompson sold approximately $50 million in recovered gold without proper accounting or distribution to 160 Ohio-based investors who funded his expedition, leading to a 2005 lawsuit and his 2015 imprisonment for refusing to disclose the location of missing coins. This parallels situations where Amazon FBA sellers, eBay merchants, and Shopify store owners manage inventory financed by investors, venture capital, or crowdfunding but fail to maintain transparent accounting systems. Thompson's claim that coins were transferred to a Belize trustee around 2009—and his subsequent assertion of memory loss—reflects the exact documentation failures that trigger regulatory scrutiny for cross-border sellers.
Financial penalties underscore compliance costs: Thompson faced $3.335 million in civil contempt fines, $250,000 in criminal contempt penalties, and $1,000 daily imprisonment fees, totaling over $4 million in legal exposure. For e-commerce sellers managing inventory valued at $1-50 million across multiple jurisdictions, this case illustrates why proper accounting, investor reporting, and asset tracking systems are non-negotiable. Sellers using third-party logistics (3PL) providers, particularly those with international warehousing in Belize, Panama, or other offshore jurisdictions, must maintain detailed inventory records accessible to stakeholders. The case also highlights risks of offshore asset transfers—Thompson's Belize trust arrangement became a liability rather than a protection, suggesting sellers should avoid jurisdictional complexity unless properly documented.
Operational implications for high-value sellers: The 10-year legal battle (2015-2026) demonstrates how asset disclosure disputes can paralyze business operations. Sellers managing inventory financed by multiple investors or venture capital must implement quarterly financial reporting, third-party audits, and transparent inventory management systems compatible with Amazon Seller Central, eBay Seller Hub, or Shopify accounting integrations. Thompson's case also reveals the importance of clear investor agreements specifying asset ownership, distribution timelines, and dispute resolution mechanisms—elements often overlooked by sellers scaling rapidly through external funding.
Questions 7
How should sellers structure investor agreements to avoid asset disclosure disputes?
Thompson's 10-year legal battle (2005-2026) stemmed from ambiguous investor agreements lacking clear asset ownership, distribution mechanisms, and dispute resolution procedures. Sellers should establish written agreements specifying: (1) investor equity percentages, (2) quarterly reporting requirements, (3) asset location transparency, (4) distribution timelines, and (5) third-party audit rights. The case shows that offshore asset transfers—like Thompson's Belize trust arrangement—become liabilities without proper documentation. Sellers managing inventory across multiple jurisdictions should use **transparent 3PL tracking systems** integrated with investor dashboards, avoiding jurisdictional complexity unless explicitly documented in investor agreements. Legal review of investor agreements before accepting capital is essential.
What are the key compliance risks for sellers managing high-value inventory financed by multiple investors?
The Thompson case demonstrates that sellers managing $1M+ inventory financed by investors face severe penalties—up to $3.335 million in civil fines plus daily imprisonment fees—if they fail to maintain transparent accounting and asset disclosure. Sellers using **Amazon FBA, eBay, or Shopify** must implement quarterly financial reporting systems, maintain detailed inventory records accessible to stakeholders, and establish clear investor agreements specifying asset ownership and distribution timelines. Failure to disclose asset locations or maintain proper documentation can trigger contempt of court charges, business paralysis, and multi-year legal disputes. Sellers should integrate third-party audit capabilities and use accounting software that tracks inventory by investor stake.