



Alibaba's 67% Profit Collapse Signals Platform Restructuring | Cross-Border Seller Impact
- Profitability plummets amid food delivery losses; cloud pricing rises 34%; 128K employees remain after 34% workforce cut; AI investment accelerates with 100B yuan revenue target





















Overview
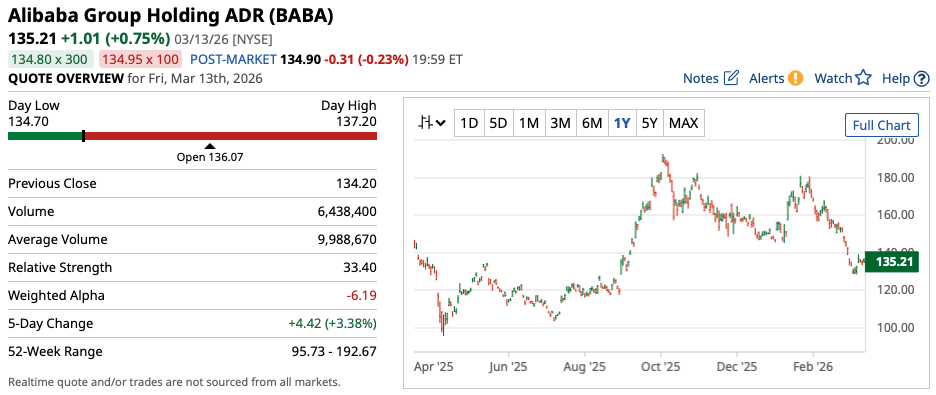
Alibaba's fiscal Q3 2025 earnings reveal a critical inflection point for the Chinese e-commerce giant and its 10+ million cross-border sellers. The company reported a devastating 67% year-over-year profit decline to 16.32 billion yuan, with adjusted earnings per ADR plummeting from 11.51 yuan (forecast) to 7.09 yuan—a 38% miss on analyst expectations. Revenue reached 284.8 billion yuan ($41.4 billion), marginally below the 285.9 billion yuan estimate, indicating core e-commerce market saturation with traditional revenue sources growing only 1% to 18.8 billion yuan.
The profitability crisis stems directly from Alibaba's aggressive food delivery and quick commerce expansion, where the company competes intensely with JD.com and Meituan through heavy discounting strategies. Quick commerce revenue surged 56% to 2.98 billion yuan—the fastest-growing segment—but this growth comes at massive margin compression. This strategic pivot has forced Alibaba to simultaneously restructure its workforce by 34% (from 194,320 to 128,197 employees) through divestment of labor-intensive offline retail operations, including the sale of Sun Art retail group and exit from Intime department stores.
For cross-border sellers, the immediate operational impact is severe: Alibaba increased cloud and storage service prices by up to 34%, directly affecting sellers relying on the platform's infrastructure for inventory management, data analytics, and business operations. This pricing increase, justified by "rising demand and supply chain costs," represents a significant cost burden for sellers managing multi-SKU operations across Alibaba's ecosystem. Simultaneously, the company's reduced profitability may constrain investment in seller support services, platform infrastructure upgrades, and international expansion initiatives—areas critical for cross-border commerce growth.
However, Alibaba's AI strategy presents a counterbalancing opportunity. The cloud and AI business unit demonstrated triple-digit growth, with cloud revenue accelerating 36% year-over-year to 43.3 billion yuan ($6.3 billion). CEO Eddie Wu announced an ambitious five-year target to surpass 100 billion yuan in combined cloud and AI external revenue, with the company committing 53 billion yuan over three years for AI infrastructure development. The launch of Wukong, an agentic AI service for business applications, signals incoming platform enhancements in product recommendations, demand forecasting, and customer service automation—tools that could significantly enhance seller productivity if properly integrated.
The competitive landscape is shifting dramatically. While Alibaba struggles with profitability, Tencent posted earnings beats with double-digit growth while ramping up AI efforts, demonstrating that AI investment is becoming table-stakes for major platforms. This competitive pressure suggests Alibaba's AI focus is essential for maintaining market relevance. For sellers, this means the platform is likely to prioritize AI-driven seller tools over traditional support services in the near term, requiring adaptation to new pricing models and technological requirements.
Questions 8
Will Alibaba reduce seller support services due to profitability pressures?
Alibaba's 67% profit decline and 34% workforce reduction signal potential constraints on seller support investment. The company's strategic focus is shifting toward AI-driven solutions rather than traditional seller services. While the company maintains strong liquidity and cash generation capabilities (per CFO Toby Xu), reduced profitability may influence investment levels in seller support services, platform infrastructure upgrades, and international expansion initiatives. Sellers should expect slower response times from seller support teams and reduced investment in non-AI seller tools. However, the company's commitment to AI development suggests future enhancements in automated seller analytics, product recommendations, and customer service automation—tools that could offset reduced human support.
How does Alibaba's 34% cloud pricing increase affect cross-border sellers?
Alibaba increased cloud and storage service prices by up to 34%, directly impacting sellers relying on the platform for inventory management, data analytics, and business operations. For a mid-sized seller managing 10,000+ SKUs with monthly cloud storage of 500GB, this could translate to $150-300 additional monthly costs. The pricing increase, justified by rising demand and supply chain costs, represents a significant margin compression for sellers already facing competitive pressure. Sellers should audit their cloud usage immediately and consider cost optimization strategies or alternative infrastructure providers. This pricing action reflects Alibaba's shift toward profitability in high-margin cloud services as core e-commerce growth slows to 1% annually.