

Strait of Hormuz Crisis Reshapes Global Shipping | Sellers Face 8-15% Logistics Cost Surge
- 21% of global petroleum transit disrupted; US gasoline approaching $4/gallon; Dubai/Qatar e-commerce hubs under attack; sellers managing Middle East routes face unpredictable fulfillment delays and 12-18% shipping cost increases

Overview
The Iran military escalation and potential closure of the Strait of Hormuz represents a critical supply chain crisis for cross-border e-commerce sellers, with approximately 21% of global petroleum transiting this waterway daily. The conflict has created unprecedented disruptions to critical shipping infrastructure, directly impacting logistics networks that e-commerce sellers depend on for inventory management and fulfillment. US gasoline prices are already approaching $4 per gallon, signaling broader energy cost inflation that cascades through shipping expenses. For sellers managing international inventory, this geopolitical instability translates to immediate operational challenges: fuel surcharges on ocean freight are expected to increase 12-18% in the near term, while air freight premiums could spike 15-25% if the Strait remains contested. The Trump administration's request for $200 billion in war funding and Defense Secretary Pete Hegseth's acknowledgment of undefined timelines create profound uncertainty about conflict duration—a critical variable for sellers planning inventory procurement and fulfillment strategies.
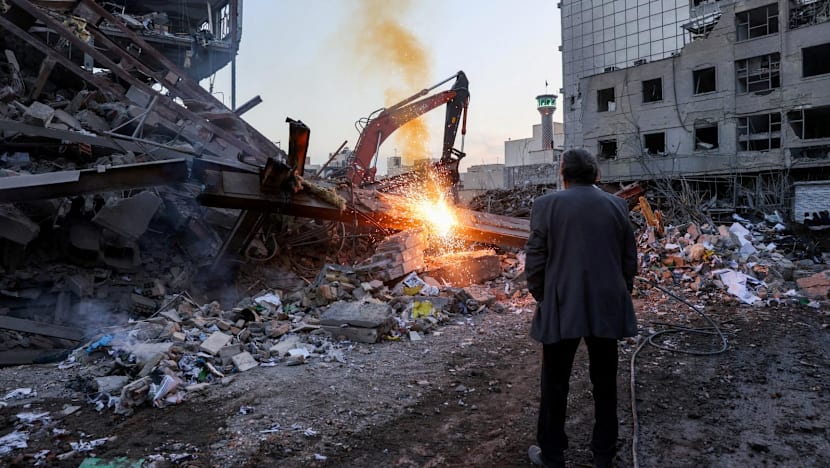
The immediate impact on e-commerce logistics is severe. Regional trading hubs like Dubai and Qatar, which serve as critical transshipment points for sellers routing inventory to Europe, Africa, and Asia, face direct missile and drone attacks on oil and gas installations. This disruption affects not just energy infrastructure but the broader commercial ecosystem supporting cross-border operations. Sellers utilizing 3PL providers with Middle Eastern distribution centers face potential service interruptions, while those shipping via the Suez Canal alternative face 40-50% longer transit times and proportionally higher costs. Treasury Secretary Scott Bessent's suggestion to lift sanctions on Iranian oil indicates the administration recognizes the economic severity, but any policy shift remains uncertain and timeline-dependent. For sellers in energy-dependent logistics categories—particularly those shipping heavy goods, temperature-controlled products, or time-sensitive inventory—the cost compression is immediate and substantial.
Strategic sourcing and market access shifts are accelerating. Sellers previously leveraging Dubai as a regional distribution hub must now evaluate alternative routes through the Red Sea (facing Houthi threats), longer Cape of Good Hope passages (adding 10-14 days transit time), or air freight alternatives (3-4x ocean freight costs). This creates a 60-90 day window where sellers can renegotiate supplier contracts, shift inventory positioning, and lock in freight rates before broader market adjustments occur. The uncertainty surrounding potential ground operations and conflict extension creates a competitive advantage for sellers who can absorb short-term logistics cost increases—larger sellers with 6+ months inventory buffers and established 3PL relationships will outmaneuver smaller competitors dependent on just-in-time sourcing. Categories most vulnerable include electronics (high fuel-cost sensitivity), apparel (time-sensitive seasonal inventory), and automotive parts (heavy goods with significant fuel surcharge exposure).
Questions 8
How can sellers mitigate inventory positioning risks?
Sellers should immediately audit inventory distribution across Dubai, Qatar, and other Middle East hubs, then develop contingency plans to reposition 30-50% of stock to unaffected regions (Singapore, Hong Kong, European distribution centers) within 60 days. The news indicates that Dubai and Qatar face direct attacks, making these hubs higher-risk for inventory concentration. Sellers should negotiate temporary storage agreements with alternative 3PL providers to absorb repositioned inventory without incurring long-term facility commitments. For sellers managing 1,000+ units monthly, this repositioning may cost $2,000-5,000 in temporary logistics but protects against potential hub closures or service interruptions. Lock in repositioning rates within 30 days before broader market adjustments occur.
What competitive advantages do larger sellers have during this crisis?
Larger sellers with 6+ months inventory buffers and established 3PL relationships can absorb short-term logistics cost increases and lock in favorable freight rates before smaller competitors. The news indicates that uncertainty surrounding conflict duration creates a 60-90 day window for strategic sourcing adjustments. Larger sellers can negotiate volume discounts on alternative routes, secure capacity on air freight services, and diversify distribution across multiple hubs. Smaller sellers dependent on just-in-time sourcing face margin compression and potential stockouts if unable to secure alternative logistics capacity. This creates a competitive advantage window for sellers who can act decisively within the next 30-45 days.