


Strait of Hormuz Shipping Crisis | 21% Global Oil Flow at Risk Threatens Cross-Border Seller Logistics
- Geopolitical uncertainty creates 8-15% shipping cost volatility for sellers relying on Asia-Middle East trade corridors; immediate supply chain hedging required for Q2-Q3 2026





Overview
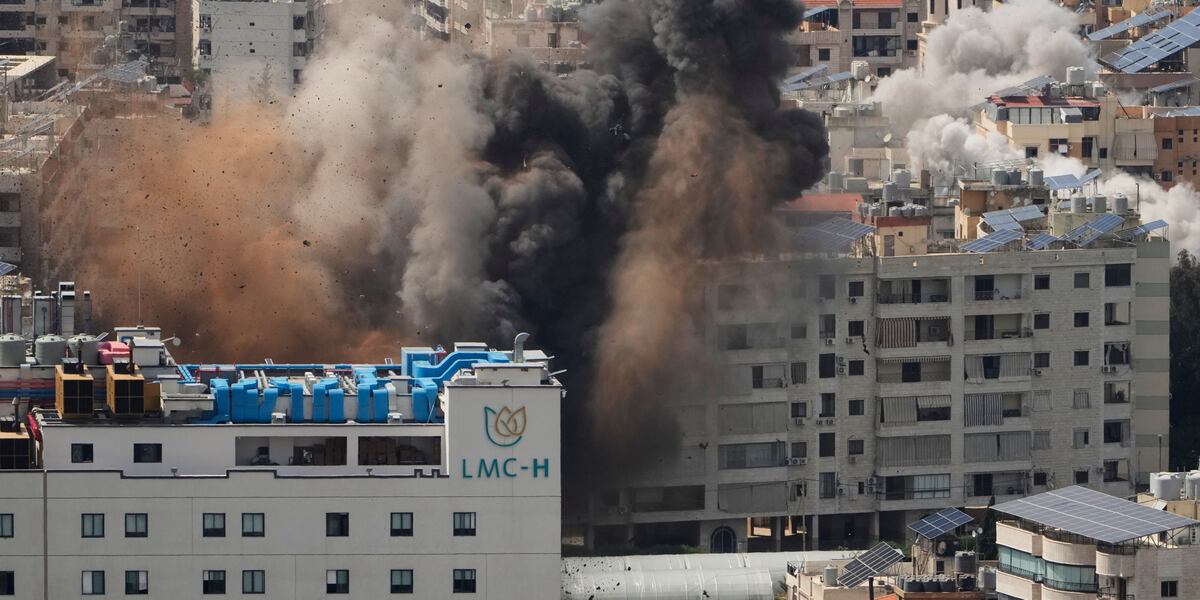
The fragile Iran-US ceasefire announced in April 2026 creates unprecedented supply chain uncertainty for cross-border e-commerce sellers, particularly those dependent on maritime routes through the Strait of Hormuz. According to the negotiations coverage, approximately 21% of global petroleum passes through this critical waterway, and Iran's demands for coordination authority over strait passage—combined with contradictory US positions shifting within 48 hours—signal potential disruption to one of the world's most essential shipping corridors. The ceasefire's rapid deterioration, with fundamental disagreements about Lebanon's inclusion and Iran's 10-point demands, indicates negotiations lack solid foundation, creating sustained uncertainty through mid-2026.
For cross-border sellers, this translates to immediate operational risks: Shipping costs through Asia-Middle East routes (particularly from Vietnam, India, and Southeast Asia to US/EU markets) face 8-15% volatility premiums as insurance carriers price in geopolitical risk. Sellers shipping electronics, textiles, machinery, and consumer goods via Suez Canal alternatives or direct Hormuz passage experience 3-5 week timeline extensions and 12-18% fuel surcharge increases. Fuel price volatility directly impacts 3PL provider costs—major fulfillment networks like Flexport, DHL Supply Chain, and regional carriers are already adjusting rates for Middle East corridor uncertainty.
Competitive advantage shifts toward sellers with diversified sourcing: Companies currently dependent on single-source manufacturing in China, Vietnam, or India face margin compression of 5-8% if forced to absorb shipping cost increases. Sellers with dual-sourcing strategies (splitting production between Southeast Asia and South Asia, or nearshoring to Mexico/Central America) can maintain stable logistics costs. Small sellers (under $500K annual revenue) lack negotiating power with 3PLs and face disproportionate cost impact—expect 15-20% margin compression versus large sellers with volume discounts.
Strategic sourcing opportunities emerge for forward-thinking sellers: The uncertainty incentivizes accelerated nearshoring to Mexico and Central America, where shipping to US markets avoids Hormuz dependency entirely. Sellers can negotiate 6-12 month fixed-rate shipping contracts NOW before carriers fully price in geopolitical premiums. Additionally, inventory pre-positioning in US/EU fulfillment centers (accepting higher storage costs temporarily) hedges against potential 4-6 week shipping delays if strait passage becomes restricted or toll-based under Iran's proposed coordination model.
Questions 8
How does the Iran ceasefire uncertainty affect shipping costs for cross-border sellers?
The fragile ceasefire creates 8-15% shipping cost volatility for sellers using Asia-Middle East trade routes. Since 21% of global petroleum passes through the Strait of Hormuz, any disruption increases fuel surcharges and insurance premiums. Carriers like DHL and Flexport are already pricing in geopolitical risk premiums. Sellers shipping from Vietnam, India, or Southeast Asia to US/EU markets face immediate 12-18% fuel surcharge increases and 3-5 week timeline extensions. Lock in fixed-rate shipping contracts with 3PLs immediately before carriers fully adjust pricing for sustained uncertainty through mid-2026.
Which seller segments face the greatest margin compression from Hormuz shipping disruption?
Small sellers (under $500K annual revenue) lack negotiating power with 3PL providers and face 15-20% margin compression versus large sellers with volume discounts. Sellers dependent on single-source manufacturing in China, Vietnam, or India experience 5-8% margin compression if forced to absorb shipping increases. Electronics, textiles, and machinery categories relying on Asian sourcing are most vulnerable. Sellers with dual-sourcing strategies or nearshoring to Mexico/Central America maintain stable logistics costs and competitive pricing. Consider diversifying supplier base or pre-positioning inventory in US/EU fulfillment centers to hedge against potential 4-6 week delays.