

U.S. Energy Export Surge Drives Logistics Cost Inflation | Cross-Border Seller Impact
- Record 12.9M barrels/day exports elevate fuel surcharges 8-15% for international sellers; heavy goods and perishables most vulnerable



Overview
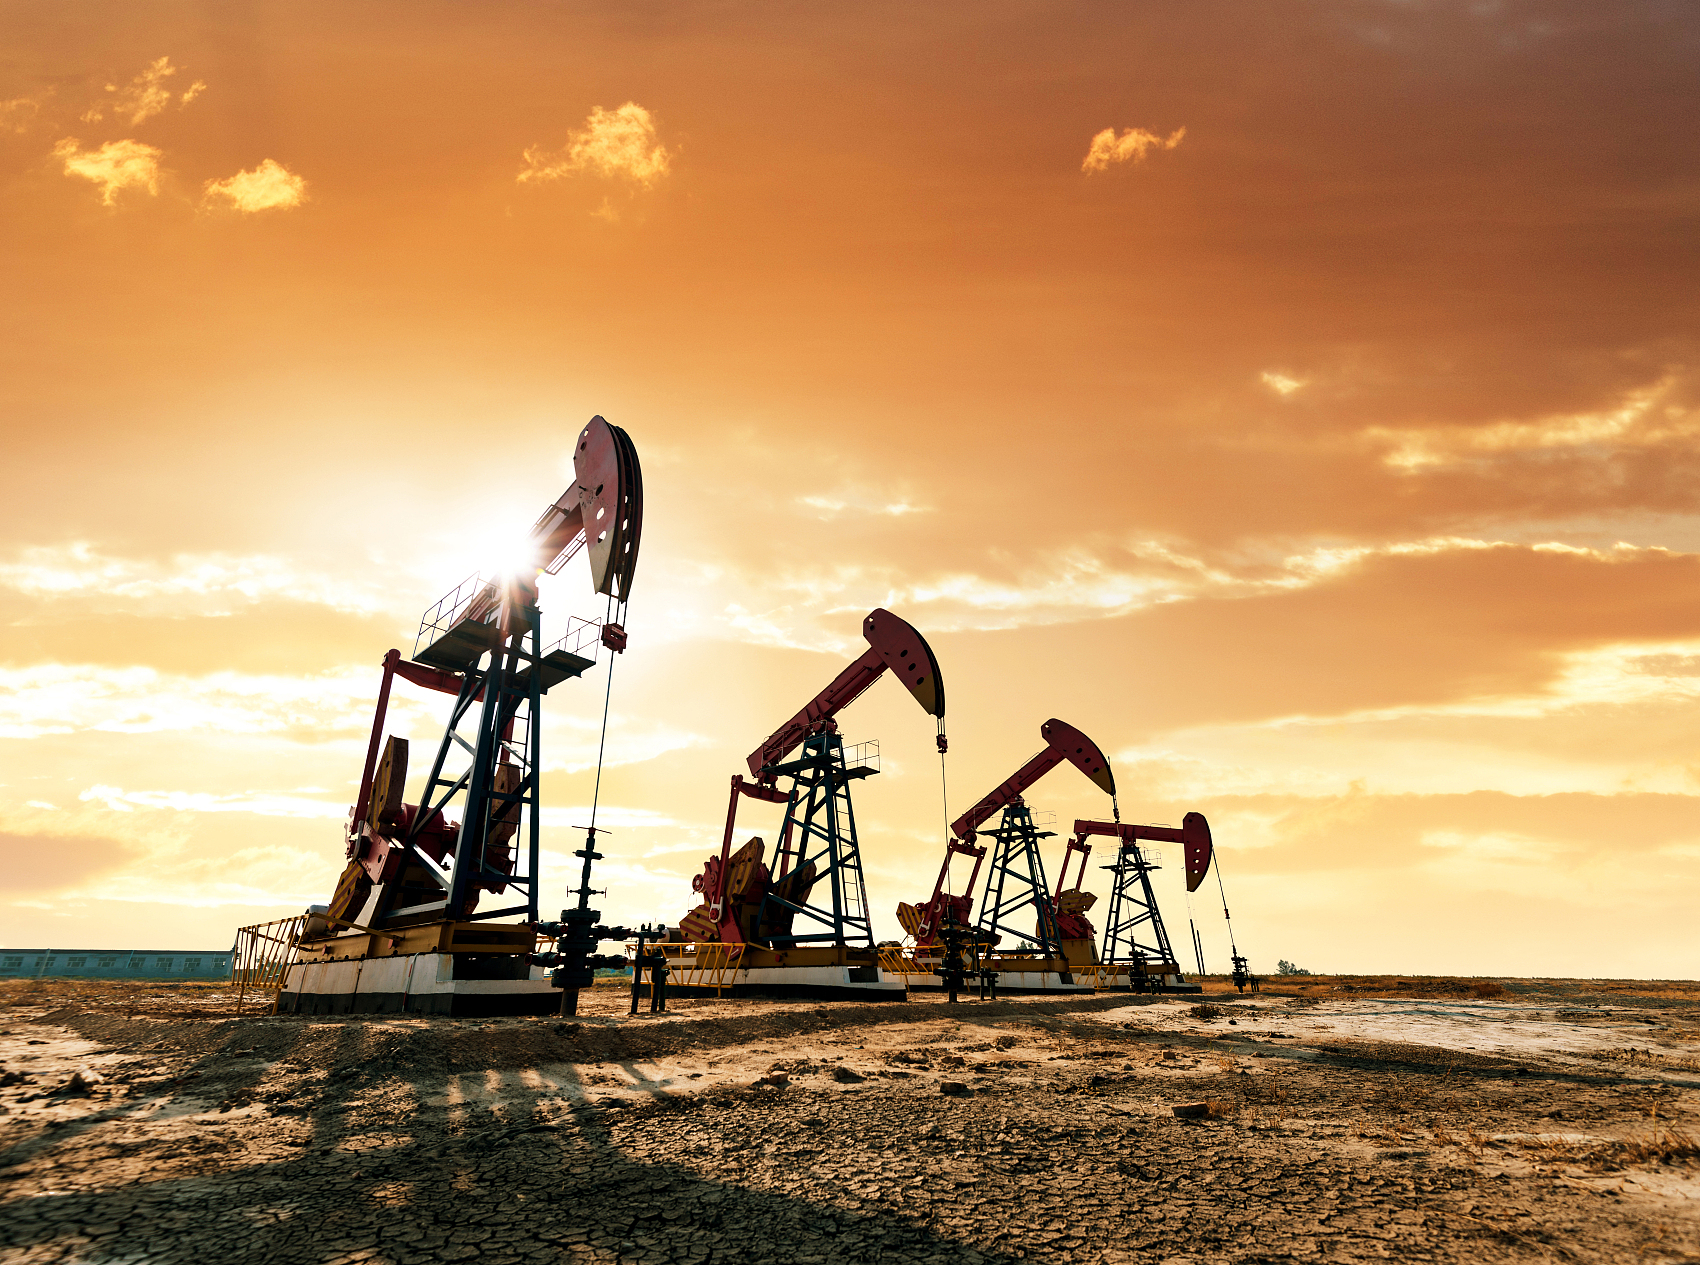
The U.S. Energy Information Administration reports record energy exports of 12.9 million barrels per day, driven by geopolitical tensions in the Strait of Hormuz and global demand for alternative energy sources. This unprecedented surge in American crude oil, natural gas, and refined petroleum products creates a critical operational challenge for cross-border e-commerce sellers: sustained elevated logistics costs that directly compress profit margins across all shipping corridors.
Immediate Logistics Cost Impact: The record energy export levels translate directly into higher fuel surcharges on ocean freight, air cargo, and ground transportation. International sellers shipping goods from Asia to North America or Europe face fuel surcharges typically ranging 8-15% above baseline rates, with some freight forwarders implementing temporary peak-season premiums. For a seller shipping 500 units monthly via ocean freight at $2,000 base cost, this represents an additional $160-300 monthly expense. Air cargo surcharges are even steeper—currently 12-18% above standard rates—making expedited shipping prohibitively expensive for margin-sensitive categories like apparel, electronics accessories, and home goods.
Seller Segment Vulnerability Analysis: Heavy goods sellers (furniture, sporting equipment, industrial supplies with HS codes 9406, 9401-9403) face the most severe margin compression, as freight costs represent 25-40% of total landed costs. Perishable goods sellers (food, supplements, cosmetics) experience compounded pressure from elevated cold chain logistics costs, warehouse energy expenses, and temperature-controlled transportation premiums. Small-to-medium sellers (SMBs) with monthly shipments under 2,000 units lack negotiating power with 3PL providers and absorb full surcharge costs, while large sellers (10,000+ monthly units) can negotiate fixed-rate contracts or shift to alternative sourcing regions. U.S.-based sellers benefit from domestic energy independence, enjoying relatively stable domestic shipping costs, while international sellers face variable freight expenses tied to global energy market fluctuations.
Strategic Sourcing Implications: The sustained high energy environment incentivizes sellers to evaluate nearshoring strategies. Vietnam, Mexico, and India-based suppliers offer 15-25% logistics cost advantages over China-sourced goods when shipping to North American markets, particularly for categories where tariff rates are comparable (HS codes 6204, 6205 for apparel; 8471-8517 for electronics). Sellers should model total landed costs including elevated freight premiums when evaluating sourcing country switches. The geopolitical situation underscores broader supply chain vulnerabilities—sellers dependent on single-source manufacturing face compounded risk from both tariff exposure and energy-driven logistics inflation.
Pricing and Inventory Strategy: Sellers must immediately recalibrate pricing models to reflect sustained fuel surcharges. Categories with price elasticity below 1.0 (essential goods, consumables) can absorb 5-8% price increases without significant demand destruction. Discretionary categories (home décor, fashion, electronics) require more cautious pricing, potentially accepting 2-4% margin compression rather than risking conversion rate decline. Inventory planning should shift toward higher-velocity SKUs with faster turnover to minimize warehouse energy costs and reduce exposure to prolonged storage during high-energy-cost periods.
Questions 8
Which product categories are most vulnerable to logistics cost inflation?
Heavy goods (furniture, sporting equipment, industrial supplies) are most vulnerable because freight costs represent 25-40% of total landed costs. Perishable goods (food, supplements, cosmetics) face compounded pressure from elevated cold chain logistics and warehouse energy expenses. Electronics accessories and home goods with lower per-unit margins also struggle to absorb surcharges. Conversely, high-value, low-weight items (jewelry, electronics, luxury goods) can better absorb freight cost increases. Sellers should prioritize inventory optimization for heavy categories and consider nearshoring from Mexico or Vietnam, which offer 15-25% logistics advantages over China-sourced goods.
How much will fuel surcharges increase my shipping costs as a cross-border seller?
Fuel surcharges are currently adding 8-15% to ocean freight costs and 12-18% to air cargo rates due to record U.S. energy exports and elevated global fuel prices. For a seller shipping 500 units monthly via ocean freight at $2,000 base cost, expect an additional $160-300 monthly expense. Air cargo premiums make expedited shipping significantly more expensive. The EIA reports 12.9 million barrels per day in U.S. exports, indicating sustained high energy prices that will likely persist through Q2 2025. Review your freight forwarding contracts immediately to lock in rates before further increases occur.