


Big Tech's $700B AI Spending Threatens Seller Platform Stability | 2026 Impact
- Amazon's free cash flow collapsed 95% YoY; Meta raising $20-25B debt; platform fee increases likely within 12 months
















Overview
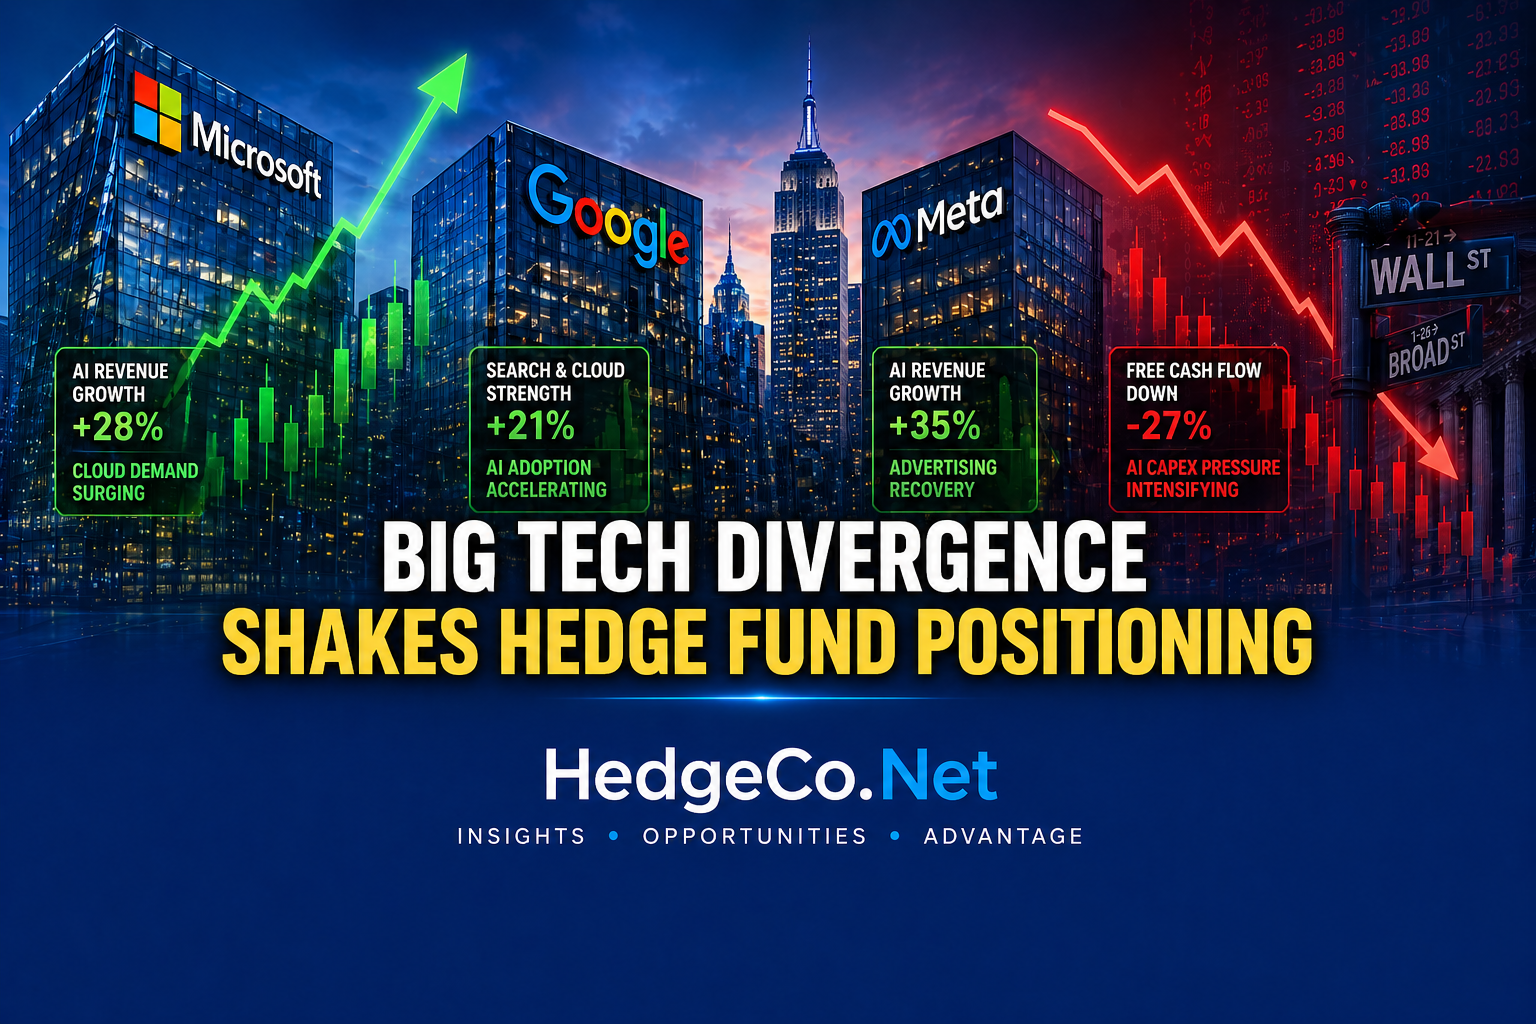
Big Tech companies are escalating AI capital expenditures to $700 billion in 2026—up from $650 billion—while simultaneously experiencing severe cash flow deterioration that threatens platform stability and seller economics. Amazon's first-quarter free cash flow plummeted 95% year-over-year to just $1.2 billion, while Alphabet's dropped 47% to $10.1 billion. This capital intensity is forcing massive debt issuances: Meta announced $20-25 billion in bonds (its second major raise following a $30 billion issuance in October 2025), and Amazon launched a $42 billion bond offering. The financial disconnect is stark—none of the four hyperscalers currently generate substantial profits from AI operations, yet they're committing unprecedented resources to commoditized large language models without established monetization pathways.
For cross-border e-commerce sellers, this creates immediate operational and financial risks. The cash flow crisis directly impacts platform investment priorities and fee structures. When platforms face liquidity pressure, they typically increase seller fees, reduce advertising credits, and tighten fulfillment cost structures to offset capital spending. Amazon's 95% free cash flow decline signals the company is prioritizing AI infrastructure over seller-facing tools and logistics improvements. Sellers should expect: (1) FBA fee increases of 8-15% within 12 months as Amazon monetizes infrastructure costs, (2) reduced advertising budget efficiency as Meta and Google redirect resources to AI R&D, (3) slower rollout of seller-beneficial features like inventory management AI tools, and (4) potential policy shifts favoring first-party Amazon products over third-party sellers.
The investor skepticism is particularly revealing for sellers. AI researcher Gary Marcus characterized the spending as "the greatest capital misallocation in history," and JPMorgan downgraded Meta to neutral, citing its lack of a public cloud platform to monetize AI investments (unlike Amazon and Alphabet, which can rent computing capacity to enterprise customers). This means Meta must extract AI ROI through advertising—directly competing with seller advertising budgets. As platforms struggle to justify AI spending to investors, they'll increasingly pressure seller margins through fee increases and reduced promotional support. The earnings opacity noted in Financial Times reporting means sellers cannot reliably predict platform financial health or policy changes, creating strategic uncertainty for inventory planning and marketing budget allocation. Sellers operating on Amazon, Meta advertising, and Google Shopping should immediately stress-test their unit economics assuming 10-15% margin compression from fee increases and reduced advertising efficiency over the next 18 months.
Questions 7
How can sellers use AI tools to offset platform fee increases?
Sellers should immediately adopt AI-powered tools to improve unit economics and offset fee pressure: (1) Dynamic pricing AI (Repricing tools like Keepa, Helium 10) to optimize margins despite fee increases—can improve profitability 8-12% through real-time price optimization. (2) Inventory forecasting AI to reduce storage fees by 15-20% through better turnover prediction. (3) AI-powered product research to identify high-margin categories less exposed to fee increases. (4) Automated listing optimization (AI copywriting tools) to improve conversion rates 10-15%, offsetting advertising cost inflation. (5) Demand forecasting AI to reduce overstock and dead inventory. These tools cost $50-300/month but can generate $500-2000/month in margin recovery. ROI is typically 2-4 months. Implement immediately—the 12-18 month window before major fee increases is critical for establishing efficiency gains that offset platform monetization pressure.
How will Big Tech's AI spending crisis affect Amazon FBA fees for sellers?
Amazon's 95% free cash flow collapse signals urgent need to monetize infrastructure investments through seller fees. Expect FBA fulfillment fees to increase 8-15% within 12 months, with storage fees rising 10-20% as Amazon offsets $200 billion AI capital expenditure. The company has historically raised fees during cash flow pressure periods—2022 saw 5-10% increases when AWS growth slowed. Sellers should immediately audit inventory turnover and consider 3PL alternatives for slow-moving SKUs to mitigate fee impact. Monitor Amazon Seller Central announcements monthly for fee schedule changes, particularly in Q2-Q3 2026 when capital spending peaks.