
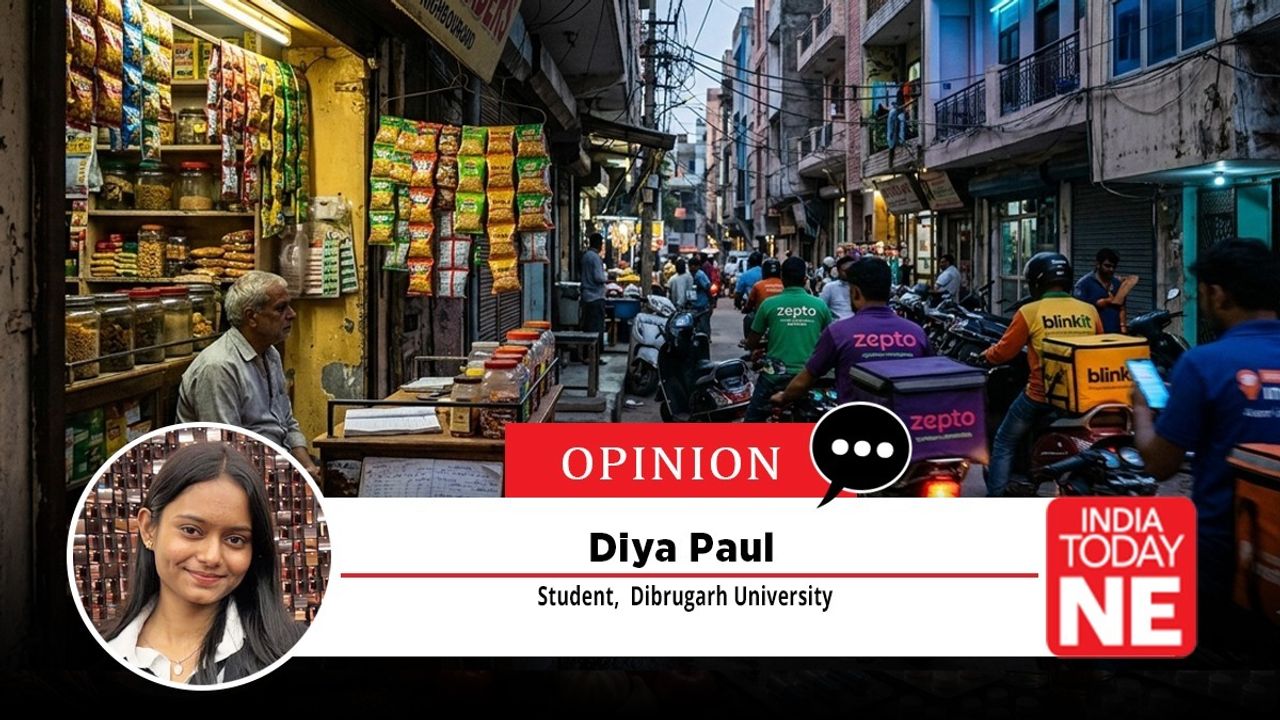
India Quick Commerce Boom | $5.5B Market Reshapes Seller Opportunities
- 10-minute delivery platforms (Zepto, Blinkit, Swiggy Instamart) expand to Tier-2/3 towns; regulatory scrutiny creates fulfillment partnership opportunities for 2M+ Kirana sellers
Overview
India's quick commerce sector has exploded to a $5.5 billion market with aggressive expansion from metro cities into Tier-2 and Tier-3 towns through hyper-local dark stores, fundamentally reshaping the e-commerce fulfillment landscape. Zepto, Blinkit, and Swiggy Instamart have revolutionized consumer expectations with 10-minute delivery models, but this rapid growth has triggered significant regulatory backlash. In April 2024, the All India Consumer Products Distributors Federation (AICPDF) filed a formal complaint with India's Competition Commission of India (CCI) alleging predatory pricing practices—selling goods below wholesale acquisition costs to systematically eliminate traditional Kirana competitors. This regulatory intervention creates a critical inflection point for cross-border sellers and platform strategists.
The regulatory environment is fundamentally shifting fulfillment models. Rather than replacing Kirana stores entirely, industry stakeholders and regulators are advocating for integration models where traditional retailers become fulfillment partners within quick commerce supply chains. This represents a $2-3 billion opportunity for sellers to leverage existing Kirana networks as last-mile fulfillment infrastructure, particularly for categories like FMCG, personal care, and household essentials where Kirana stores maintain strong community trust and credit relationships. Sellers can now position themselves as suppliers to quick commerce platforms' dark store networks while simultaneously maintaining relationships with traditional retailers—a dual-channel strategy that was previously competitive.
Platform dynamics are creating new seller segments and margin structures. The predatory pricing allegations suggest that current quick commerce unit economics are unsustainable without regulatory change. Sellers should anticipate margin compression in the 8-15% range for products sold through quick commerce channels versus traditional retail, but volume opportunities could offset this through 3-5x order frequency increases. The expansion into Tier-2 and Tier-3 towns (estimated 200+ new dark store locations annually) creates demand for local sourcing and regional product variants. Sellers with existing relationships in secondary Indian markets or those offering regional FMCG products (regional snacks, local beverages, regional personal care brands) have first-mover advantages before competition intensifies.
Regulatory outcomes will determine platform consolidation and seller concentration. If the CCI enforces fair competition rules limiting predatory pricing, quick commerce platforms will need to improve unit economics through operational efficiency rather than subsidies. This favors sellers with strong supply chain capabilities and those offering higher-margin categories (premium personal care, specialty foods, health supplements). Conversely, if platforms maintain aggressive pricing through FDI funding, sellers should focus on volume-based strategies and category expansion to capture market share before consolidation occurs. The timeline for regulatory decisions (typically 6-12 months for CCI investigations) creates a window for sellers to establish platform relationships and test product-market fit before margin structures stabilize.
Questions 8
What is India's quick commerce market size and growth trajectory?
India's quick commerce sector is valued at $5.5 billion with projections for significant expansion in coming years. The market is dominated by **Zepto, Blinkit, and Swiggy Instamart**, which have expanded from metro cities into Tier-2 and Tier-3 towns through hyper-local dark store networks. Industry analysts project the market could reach $15-20 billion by 2027-2028 based on current growth rates and geographic expansion. For sellers, this represents a 3-4x market expansion opportunity, particularly for FMCG and personal care categories where quick commerce penetration is still below 15% in secondary markets.
How are regulatory actions affecting quick commerce platform strategies?
In April 2024, the All India Consumer Products Distributors Federation (AICPDF) filed a formal complaint with India's Competition Commission of India (CCI) alleging predatory pricing—selling goods below wholesale acquisition costs to eliminate traditional competitors. The CCI investigation typically takes 6-12 months, creating uncertainty around platform pricing strategies. Rather than replacing Kirana stores, regulators are advocating for integration models where traditional retailers become fulfillment partners. This regulatory shift creates opportunities for sellers to develop dual-channel strategies serving both quick commerce platforms and traditional retail networks simultaneously.