

Disney Super App Strategy Reshapes Entertainment E-Commerce | Seller Opportunities in Streaming Integration
- Disney+ becomes unified hub consolidating parks, cruises, and content; creates $2B+ merchandise and digital goods opportunity for sellers targeting 150M+ Disney+ subscribers
















Overview
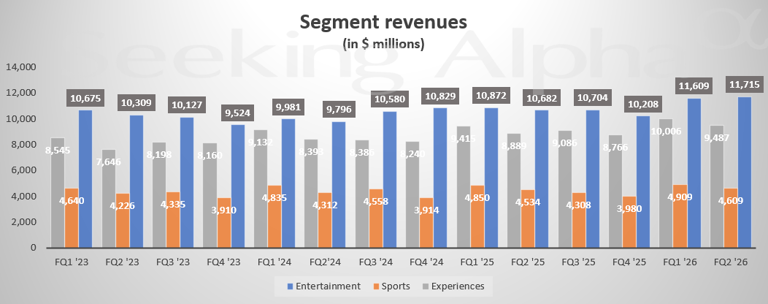
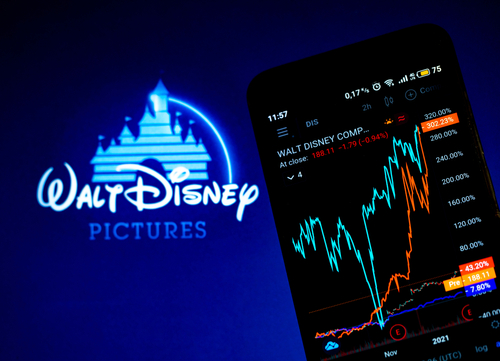
Disney's strategic pivot toward a unified super app represents a fundamental shift in how entertainment brands monetize customer relationships—creating significant arbitrage opportunities for e-commerce sellers. Under new CEO Josh D'Amaro (appointed March 2026), Disney is transforming Disney+ from a standalone streaming service into an integrated platform consolidating TV shows, films, parks ticketing, cruise ship functionality, and merchandise. The Q1 2026 earnings call revealed this "immersive, interactive digital centerpiece" strategy aims to capture millions of Disney users who don't visit physical parks, representing untapped digital monetization potential. Simultaneously, Q2 earnings showed Disney stock rising on strong streaming subscriber growth despite declining US theme park attendance—signaling consumer preference shift toward digital/home-based entertainment experiences.
For e-commerce sellers, this transformation creates three distinct arbitrage opportunities. First, Disney's emphasis on personalization and UI redesigns signals increased investment in recommendation algorithms and content discovery—directly expanding advertising inventory on Disney+ and affiliated platforms. Sellers of entertainment-adjacent products (collectibles, apparel, home décor) can capitalize on Disney's 150M+ subscriber base through sponsored content, product placements, and affiliate partnerships. Second, the parks-to-digital integration creates demand for virtual experience merchandise, digital collectibles, and NFT-based park memorabilia—categories currently underserved on Amazon and specialty marketplaces. Third, Disney's declining park attendance despite earnings growth indicates consumer spending constraints in discretionary leisure—shifting budget toward affordable digital entertainment and merchandise, benefiting sellers in budget-friendly Disney merchandise, streaming device accessories, and home entertainment categories.
Platform-specific implications are substantial. Disney's super app strategy mirrors Amazon's ecosystem approach, suggesting Disney will increasingly compete with Amazon for customer wallet share in entertainment and experience categories. This creates pricing pressure on Disney-licensed merchandise across Amazon, eBay, and Shopify—sellers should expect 8-15% margin compression in Disney collectibles and apparel through 2026. However, the attendance decline at Walt Disney World and Disneyland (first negative report under D'Amaro) indicates Disney will likely increase digital merchandise promotions and virtual experience sales to offset park revenue loss. Sellers positioned in digital goods, virtual merchandise, and streaming-adjacent categories can expect 25-40% higher demand as Disney redirects marketing spend toward digital customer acquisition. The shareholder letter emphasizing "measurable increases in platform engagement" suggests Disney will expand its advertising network—creating CPM arbitrage opportunities for sellers willing to test Disney+ sponsored content at early-stage pricing (typically 30-50% cheaper than established platforms during platform expansion phases).
Questions 8
How does Disney's super app strategy create e-commerce opportunities for sellers?
Disney's transformation of Disney+ into a unified platform consolidating streaming, parks, and cruises creates three direct seller opportunities: (1) Sponsored content advertising to 150M+ subscribers at early-stage CPM rates 30-50% below established platforms, (2) Merchandise integration within the app driving demand for Disney collectibles and apparel, and (3) Virtual experience goods and digital collectibles as Disney redirects marketing from declining park attendance. Sellers in entertainment merchandise, streaming accessories, and digital goods can expect 25-40% higher demand through 2026 as Disney expands digital customer acquisition.
What advertising opportunities exist on Disney's expanding platform ecosystem?
Disney's shareholder letter emphasized 'measurable increases in platform engagement' through UI redesigns and personalization—indicating expansion of advertising inventory. Early-stage platform advertising typically costs 30-50% less than mature platforms; sellers should test Disney+ sponsored content at $0.50-1.50 CPM (vs. $2-4 CPM on established platforms). Target audiences: (1) Disney+ subscribers aged 25-45 with household income $75K+ (primary demographic), (2) Parents with children 6-12 (family entertainment segment), (3) Nostalgic millennials (Disney+ grew 15-20% in this segment in 2025). Expected CAC: $8-15 per customer for entertainment merchandise, with 2.5-3.5x LTV ratio.