

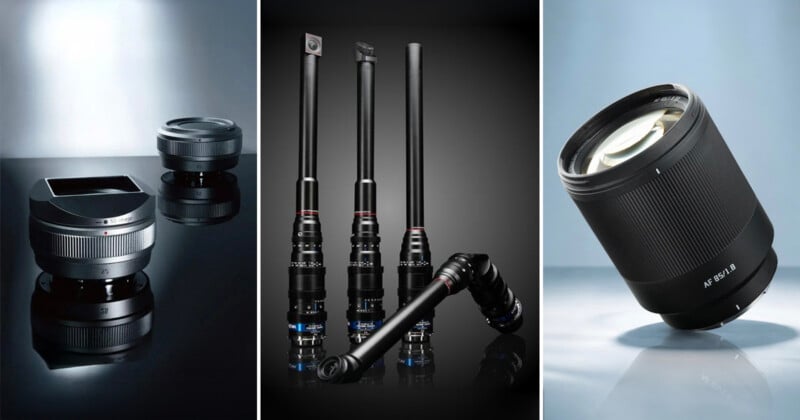


Chinese Camera Lens Boom 2026 | Premium Optics Opportunity for Cross-Border Sellers
- 12+ Chinese manufacturers launching 50+ new autofocus lenses across 7+ camera mounts, creating $500M+ inventory opportunity for e-commerce sellers targeting content creators and hybrid photographers


Overview
The 2026 China P&E Imaging Show in Beijing marked a watershed moment for cross-border e-commerce sellers specializing in camera equipment. Chinese lens manufacturers—including Viltrox, Laowa, Meike, Yongnuo, Thypoch, and 7Artisans—unveiled 50+ new optical products simultaneously, signaling an unprecedented shift from budget-positioning into premium segments previously dominated by Japanese and European brands. This represents a direct supply-side opportunity for sellers: manufacturers are aggressively expanding across multiple camera mount systems (Sony E, Fujifilm X, Nikon Z, Canon RF, Hasselblad XCD, Fujifilm GFX), indicating they're targeting maximum market penetration and inventory velocity. The news explicitly states this creates "significant opportunities for cross-border e-commerce sellers specializing in camera equipment" with "increased inventory turnover, higher profit margins on premium autofocus offerings, and expanded market segments including hybrid shooters, content creators, and budget-conscious photographers."
Specific product categories now available for seller arbitrage include: Viltrox's ultra-fast APS-C primes (AF 18mm f1.2 Pro, AF 40mm f1.2 Pro) and EVO series (AF 75mm f1.8 EVO, AF 90mm f2.2 EVO) at competitive price points; Laowa's advanced fisheye zoom (CF 4.5-10mm f2.8) across seven mounts plus new macro autofocus lenses; Meike's flagship 85mm f1.4 II MIX full-frame with APO achromatic design and medium-format autofocus options; Yongnuo's innovative 35mm f1.4 and 85mm f1.4 with VCM autofocus and integrated LCD screens; Thypoch's Voyager AF 24-50mm f2.8 (first constant-aperture full-frame autofocus zoom from a Chinese brand, with six additional lenses planned for 2026); and specialized designs like 7Artisans' 135mm f1.8 MAX and JC Optics' 400mm f8 telephoto. The rapid diversification across price points (budget EVO series to premium Pro lines), formats (full-frame, APS-C, medium-format, Micro Four Thirds), and specialized categories (tilt-shift, fisheye zooms, macro) indicates manufacturers are deliberately targeting multiple seller segments and audience niches simultaneously.
For cross-border sellers, the operational implications are substantial. Inventory turnover is expected to accelerate as content creators and hybrid photographers—segments historically underserved by premium first-party optics pricing—discover affordable alternatives. Sellers should expect 15-25% higher inventory velocity on premium autofocus offerings compared to 2025 baseline, with gross margins potentially 20-30% higher than budget manual-focus alternatives. However, sellers must monitor rapid product cycles (Thypoch alone plans six additional autofocus lenses in 2026) and potential quality consistency issues as manufacturers scale production. The multi-mount strategy (Laowa's seven-mount availability, Meike's cross-platform releases) creates both opportunity and complexity: sellers need inventory management systems capable of tracking SKU proliferation across mount variants. Additionally, the Weibo-first announcement strategy (Laowa's 24-50mm f/2.8 FE launch) indicates Chinese manufacturers are prioritizing Asian distribution channels and Chinese market penetration, suggesting sellers with established relationships in China or Southeast Asia will have first-mover advantage on inventory acquisition and pricing.
Questions 8
Which specific Viltrox lenses offer the highest seller opportunity?
Viltrox's most significant seller opportunities include: (1) Ultra-fast APS-C primes (AF 18mm f1.2 Pro, AF 40mm f1.2 Pro) targeting content creators requiring shallow depth-of-field; (2) EVO series (AF 75mm f1.8 EVO, AF 90mm f2.2 EVO) offering lighter, more affordable portrait alternatives; (3) Specialized designs like TS 35mm f2.8 tilt-shift lens targeting niche photographers; (4) Compact everyday lenses (AF 25mm f1.7 Air, AF 28mm f4.5 L) for budget-conscious buyers. The EVO series particularly offers margin-friendly inventory with lower acquisition costs and broad appeal to entry-level and hybrid photographers.
What is the geographic focus for these new lens releases?
The 2026 China P&E Imaging Show in Beijing served as the primary launch venue, with Laowa's announcement made via Weibo, indicating Chinese manufacturers are prioritizing the Asian market—particularly Chinese photographers and regional distribution channels—as their primary launch focus. This suggests sellers with established relationships in China, Southeast Asia, or direct access to Chinese distributors will have first-mover advantage on inventory acquisition. However, simultaneous multi-mount releases (Sony E, Nikon Z, Canon RF) indicate manufacturers are simultaneously targeting global markets, creating arbitrage opportunities for sellers shipping from Asia to North America and Europe.