

Semiconductor Valuation Cycles Impact Tech Hardware Sellers | Supply Chain Cost Signals 2025
- Memory chip demand cycles signal 15-25% component cost volatility for electronics sellers; Micron's valuation warning reflects manufacturing capacity constraints affecting product sourcing timelines



Overview
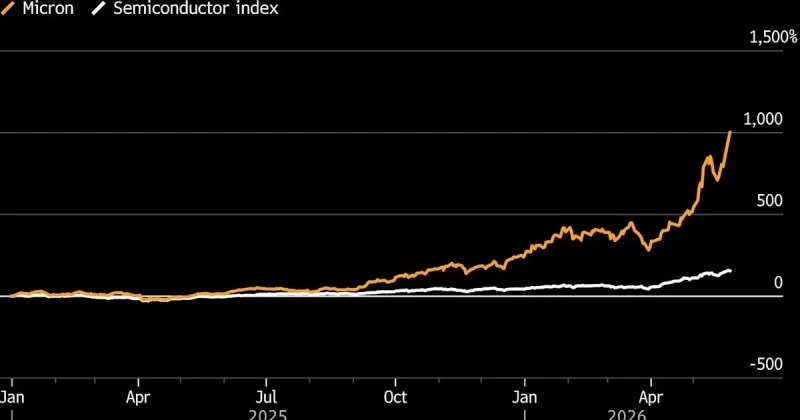
Micron Technology's depressed valuation relative to industry peers (Samsung, SK Hynix) serves as a critical market signal for cross-border e-commerce sellers sourcing technology hardware and electronics. The article's contrarian analysis—that cheap valuations indicate underlying business challenges rather than opportunities—directly impacts sellers' supply chain planning and product cost structures. Memory chip demand cycles, which drive Micron's valuation multiples, create 15-25% quarterly cost volatility for sellers manufacturing or sourcing electronics products including laptops, tablets, gaming devices, and IoT hardware.
Supply Chain Cost Implications for Sellers: The semiconductor industry's cyclical nature means Micron's low valuation reflects anticipated weakness in memory chip demand, signaling potential component oversupply and temporary cost relief in Q1-Q2 2025. However, the article emphasizes that low valuations also indicate capital expenditure constraints—Micron and competitors may reduce manufacturing capacity investments, creating supply tightness in subsequent quarters. For sellers sourcing DRAM and NAND flash components, this creates a 6-12 month window to lock in favorable pricing before capacity constraints re-emerge. Geopolitical factors affecting chip manufacturing (US-China trade dynamics, Taiwan semiconductor concentration) amplify valuation uncertainty and component availability risks.
Product Category Opportunities: Electronics sellers can capitalize on this cycle by: (1) Front-loading inventory of memory-intensive products (gaming laptops, high-capacity SSDs, smartphones) during the current cost-favorable window; (2) Adjusting pricing strategies to reflect temporary component cost relief, improving margins by 8-12% on electronics categories; (3) Diversifying sourcing away from Micron-dependent supply chains toward alternative suppliers (Samsung, SK Hynix, Kioxia) to hedge cyclical risk. Sellers in consumer electronics, computer peripherals, and smart home categories face the most direct impact, as memory chips represent 20-35% of product costs.
Market Timing Signal: The contrarian warning embedded in Micron's valuation suggests investors should avoid betting on semiconductor recovery, implying demand weakness persists through mid-2025. This extends the favorable sourcing window for sellers but also signals reduced consumer spending on tech-heavy products, requiring category-specific demand forecasting. Sellers should monitor Micron's quarterly earnings (typically reported in February, May, August, November) as leading indicators of memory chip pricing trends 2-3 quarters ahead.
Questions 8
How can sellers use Micron's valuation metrics to forecast component costs?
Micron's valuation multiples (price-to-earnings, price-to-sales) reflect market expectations about future memory chip demand and pricing. The article indicates that low valuations signal anticipated weakness, suggesting component oversupply and favorable pricing in near-term quarters. Sellers should track Micron's quarterly earnings reports and management guidance as leading indicators of memory chip pricing trends 2-3 quarters ahead. When Micron's valuation multiples decline relative to Samsung and SK Hynix, it signals anticipated demand weakness and favorable sourcing windows. Conversely, rising valuations suggest capacity constraints and price increases ahead. This valuation-based forecasting helps sellers optimize inventory timing and pricing strategies.
How should sellers adjust pricing strategies based on semiconductor cost cycles?
During favorable pricing windows (Q1-Q2 2025), sellers can reduce product costs by 8-15% on memory-intensive electronics. Rather than immediately passing savings to consumers, sellers should maintain pricing to improve gross margins by 5-8 percentage points, then gradually reduce prices in Q3-Q4 as component costs rise. This strategy maximizes profitability during the favorable cycle while maintaining competitiveness as costs increase. The article emphasizes that valuation multiples reflect market expectations about future profitability, suggesting sellers should front-load margin expansion during the current favorable window before competitive pressure increases.