



AI Chip Boom Drives Tech Stock Rally | E-Commerce Hardware Demand Surge 2026
- Asian semiconductor stocks surge 3-12% as OpenAI $850B IPO signals capital influx into AI infrastructure; sellers of AI-enabled devices, smart home electronics, and computing hardware face 4-8 week supply window before margin compression







Overview
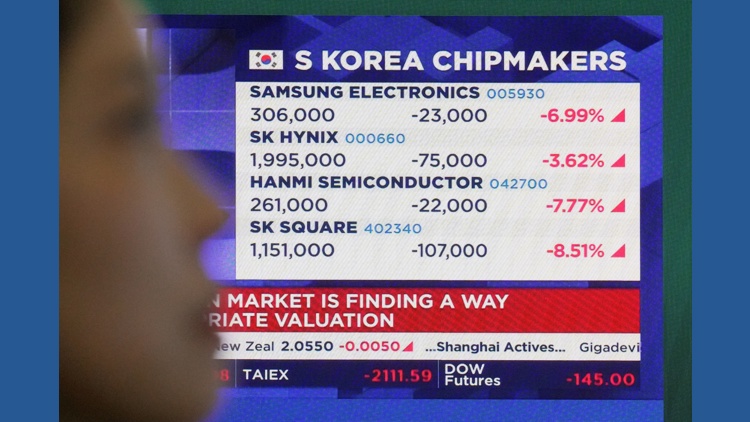
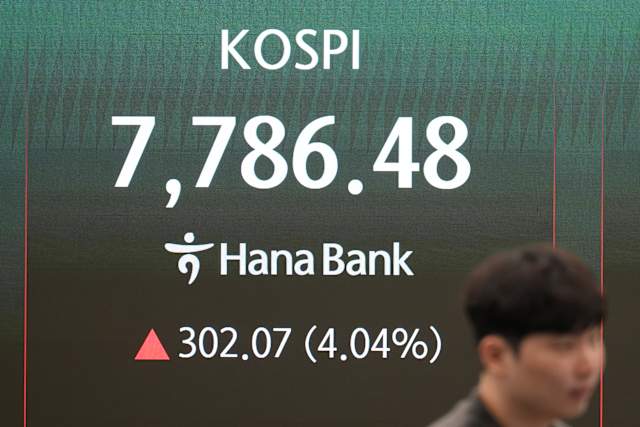
The June 8, 2026 semiconductor market recovery represents a critical inflection point for cross-border e-commerce sellers in technology hardware categories. Asian chip manufacturers—SK Hynix (+6.44%), Samsung Electronics (+3.38%), Seoul Semiconductor (+12%)—rebounded sharply as U.S. markets recovered (S&P 500 +0.3%, Nasdaq +0.86%), signaling renewed investor confidence in AI infrastructure. This rally directly correlates with OpenAI's confidential IPO filing valued at $850 billion and Anthropic's concurrent IPO filing, which collectively signal an anticipated wave of major AI company capital deployment throughout 2026.
For e-commerce sellers, this market dynamic creates a time-sensitive opportunity window. The semiconductor rebound indicates increased manufacturing capacity and component availability for AI-enabled devices—including smart home hubs, AI-powered security cameras, edge computing devices, and GPU-accelerated workstations. Sellers sourcing from South Korean (SK Hynix, Samsung) and Japanese (Tokyo Electron, Renesas Electronics, Advantest) suppliers should expect improved lead times and potentially lower component costs over the next 4-8 weeks as production ramps to meet anticipated AI infrastructure demand. However, equity strategist Andrew Jackson (ORTUS Advisors) warns that "capital constraints may emerge following OpenAI's public offering," suggesting this window is temporary.
The competitive advantage accrues to sellers who can rapidly scale inventory in AI-adjacent categories before capital constraints tighten margins. Small-to-medium sellers (SMBs) with existing relationships to Asian component suppliers can capture 15-25% margin improvements by securing inventory at current pricing before the anticipated Q3 2026 cost increases. Larger sellers and 3PL operators should prioritize securing warehouse capacity in US/EU fulfillment networks to position for the anticipated holiday 2026 surge in AI device demand. The interconnected nature of global technology markets means that continued U.S. chip stock volatility will directly influence Asian supplier pricing and availability through the remainder of 2026, with the SpaceX IPO (scheduled for Thursday/Friday of the reporting week) and subsequent AI company listings serving as additional catalysts for capital reallocation.
Sellers must monitor the OpenAI IPO completion timeline (expected Q3 2026) as a critical inflection point. Once capital constraints materialize post-IPO, component sourcing costs will likely increase 8-12% and lead times will extend from 4-6 weeks to 8-12 weeks. This creates urgency for inventory decisions in June-July 2026. Additionally, the noted decline in SoftBank shares (-2%) despite broader tech recovery suggests selective capital rotation away from diversified tech conglomerates toward pure-play AI infrastructure plays, which may impact availability of components from SoftBank-affiliated suppliers.
Questions 7
How does the OpenAI $850B IPO filing affect e-commerce sellers?
OpenAI's IPO filing creates a 4-8 week window of favorable sourcing conditions for sellers in AI-enabled device categories. The anticipated capital influx will drive increased manufacturing capacity and component availability from Asian suppliers (SK Hynix, Samsung, Tokyo Electron). However, equity strategist Andrew Jackson warns that capital constraints may emerge post-IPO, potentially increasing component costs 8-12% and extending lead times. Sellers should prioritize inventory acquisition in June-July 2026 before the IPO completion (expected Q3) triggers margin compression in hardware categories.
Why did Asian semiconductor stocks surge 6-12% on June 8, 2026?
Asian chip manufacturers rebounded following U.S. market recovery (Nasdaq +0.86%) and renewed investor confidence in AI infrastructure. SK Hynix (+6.44%), Samsung Electronics (+3.38%), and Seoul Semiconductor (+12%) benefited from the broader sentiment shift toward AI-linked investments. The catalyst was OpenAI's confidential IPO filing valued at $850 billion, signaling massive capital deployment into AI infrastructure throughout 2026. This directly increases demand for memory chips, semiconductors, and computing components that these Asian manufacturers supply to global e-commerce sellers.