


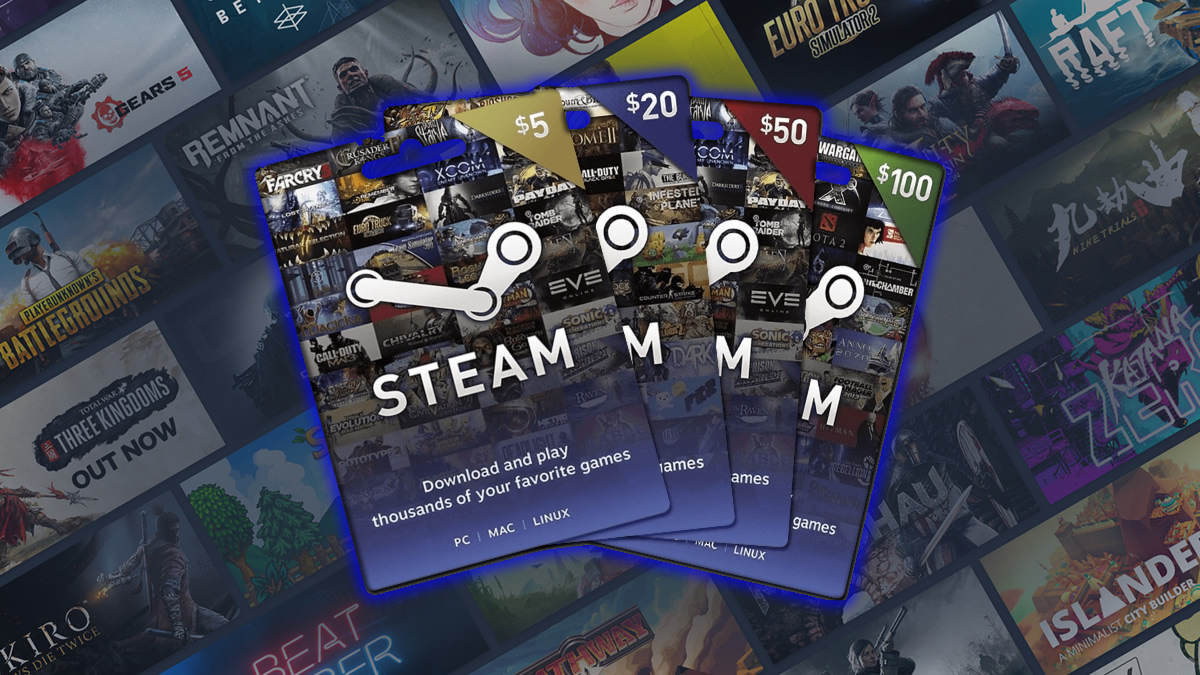

Digital Gift Card Shift Creates $2B+ Retail Opportunity | Gaming Payment Fraud Drives Platform Consolidation
- Valve ends physical Steam card production by end of 2026; signals broader retail payment consolidation affecting 50M+ gamers and reshaping $180B gaming merchandise market














Overview
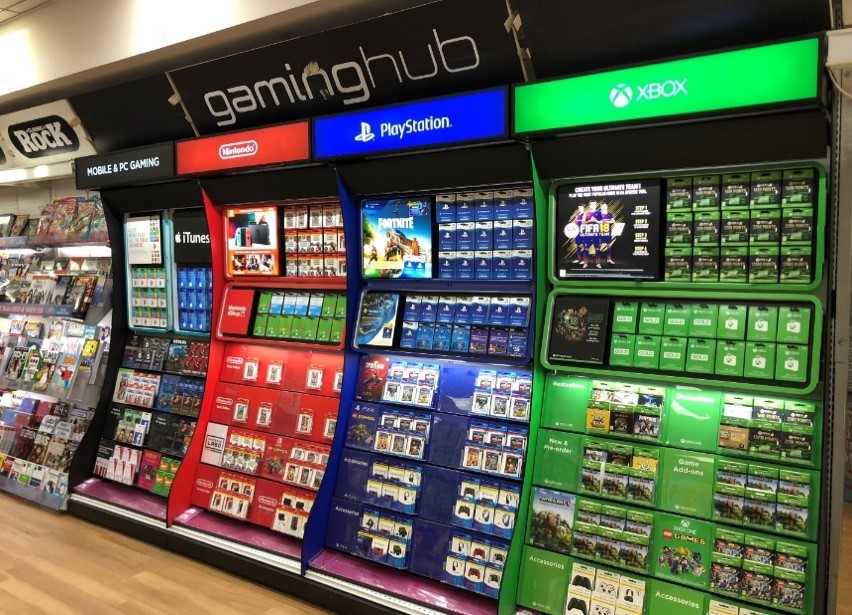
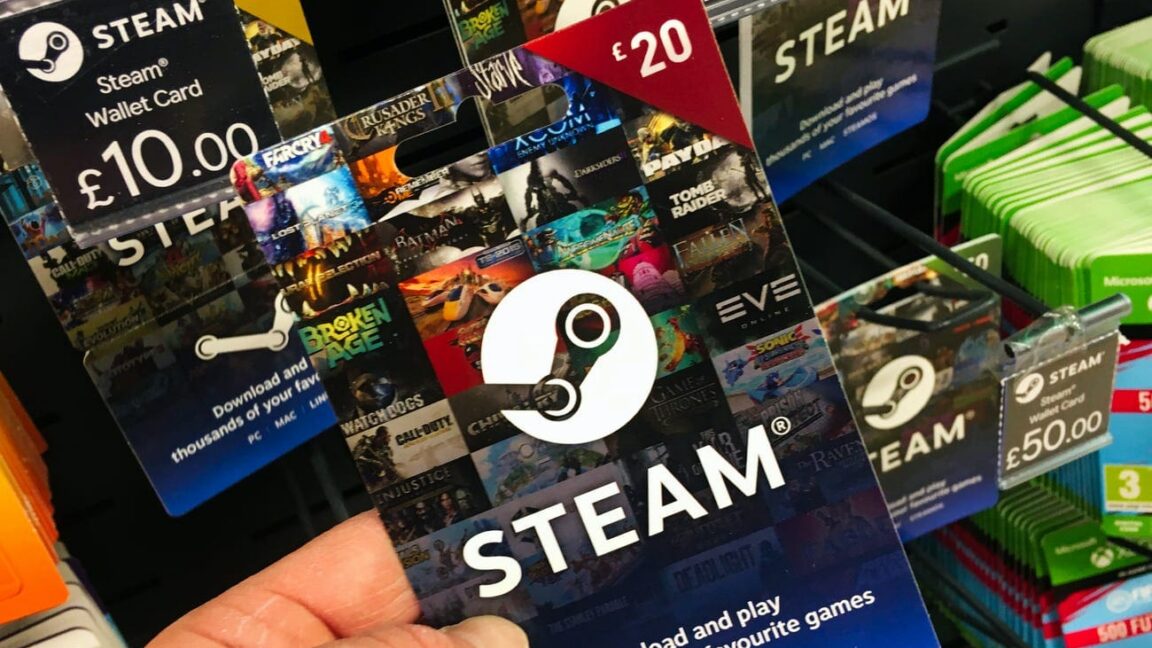
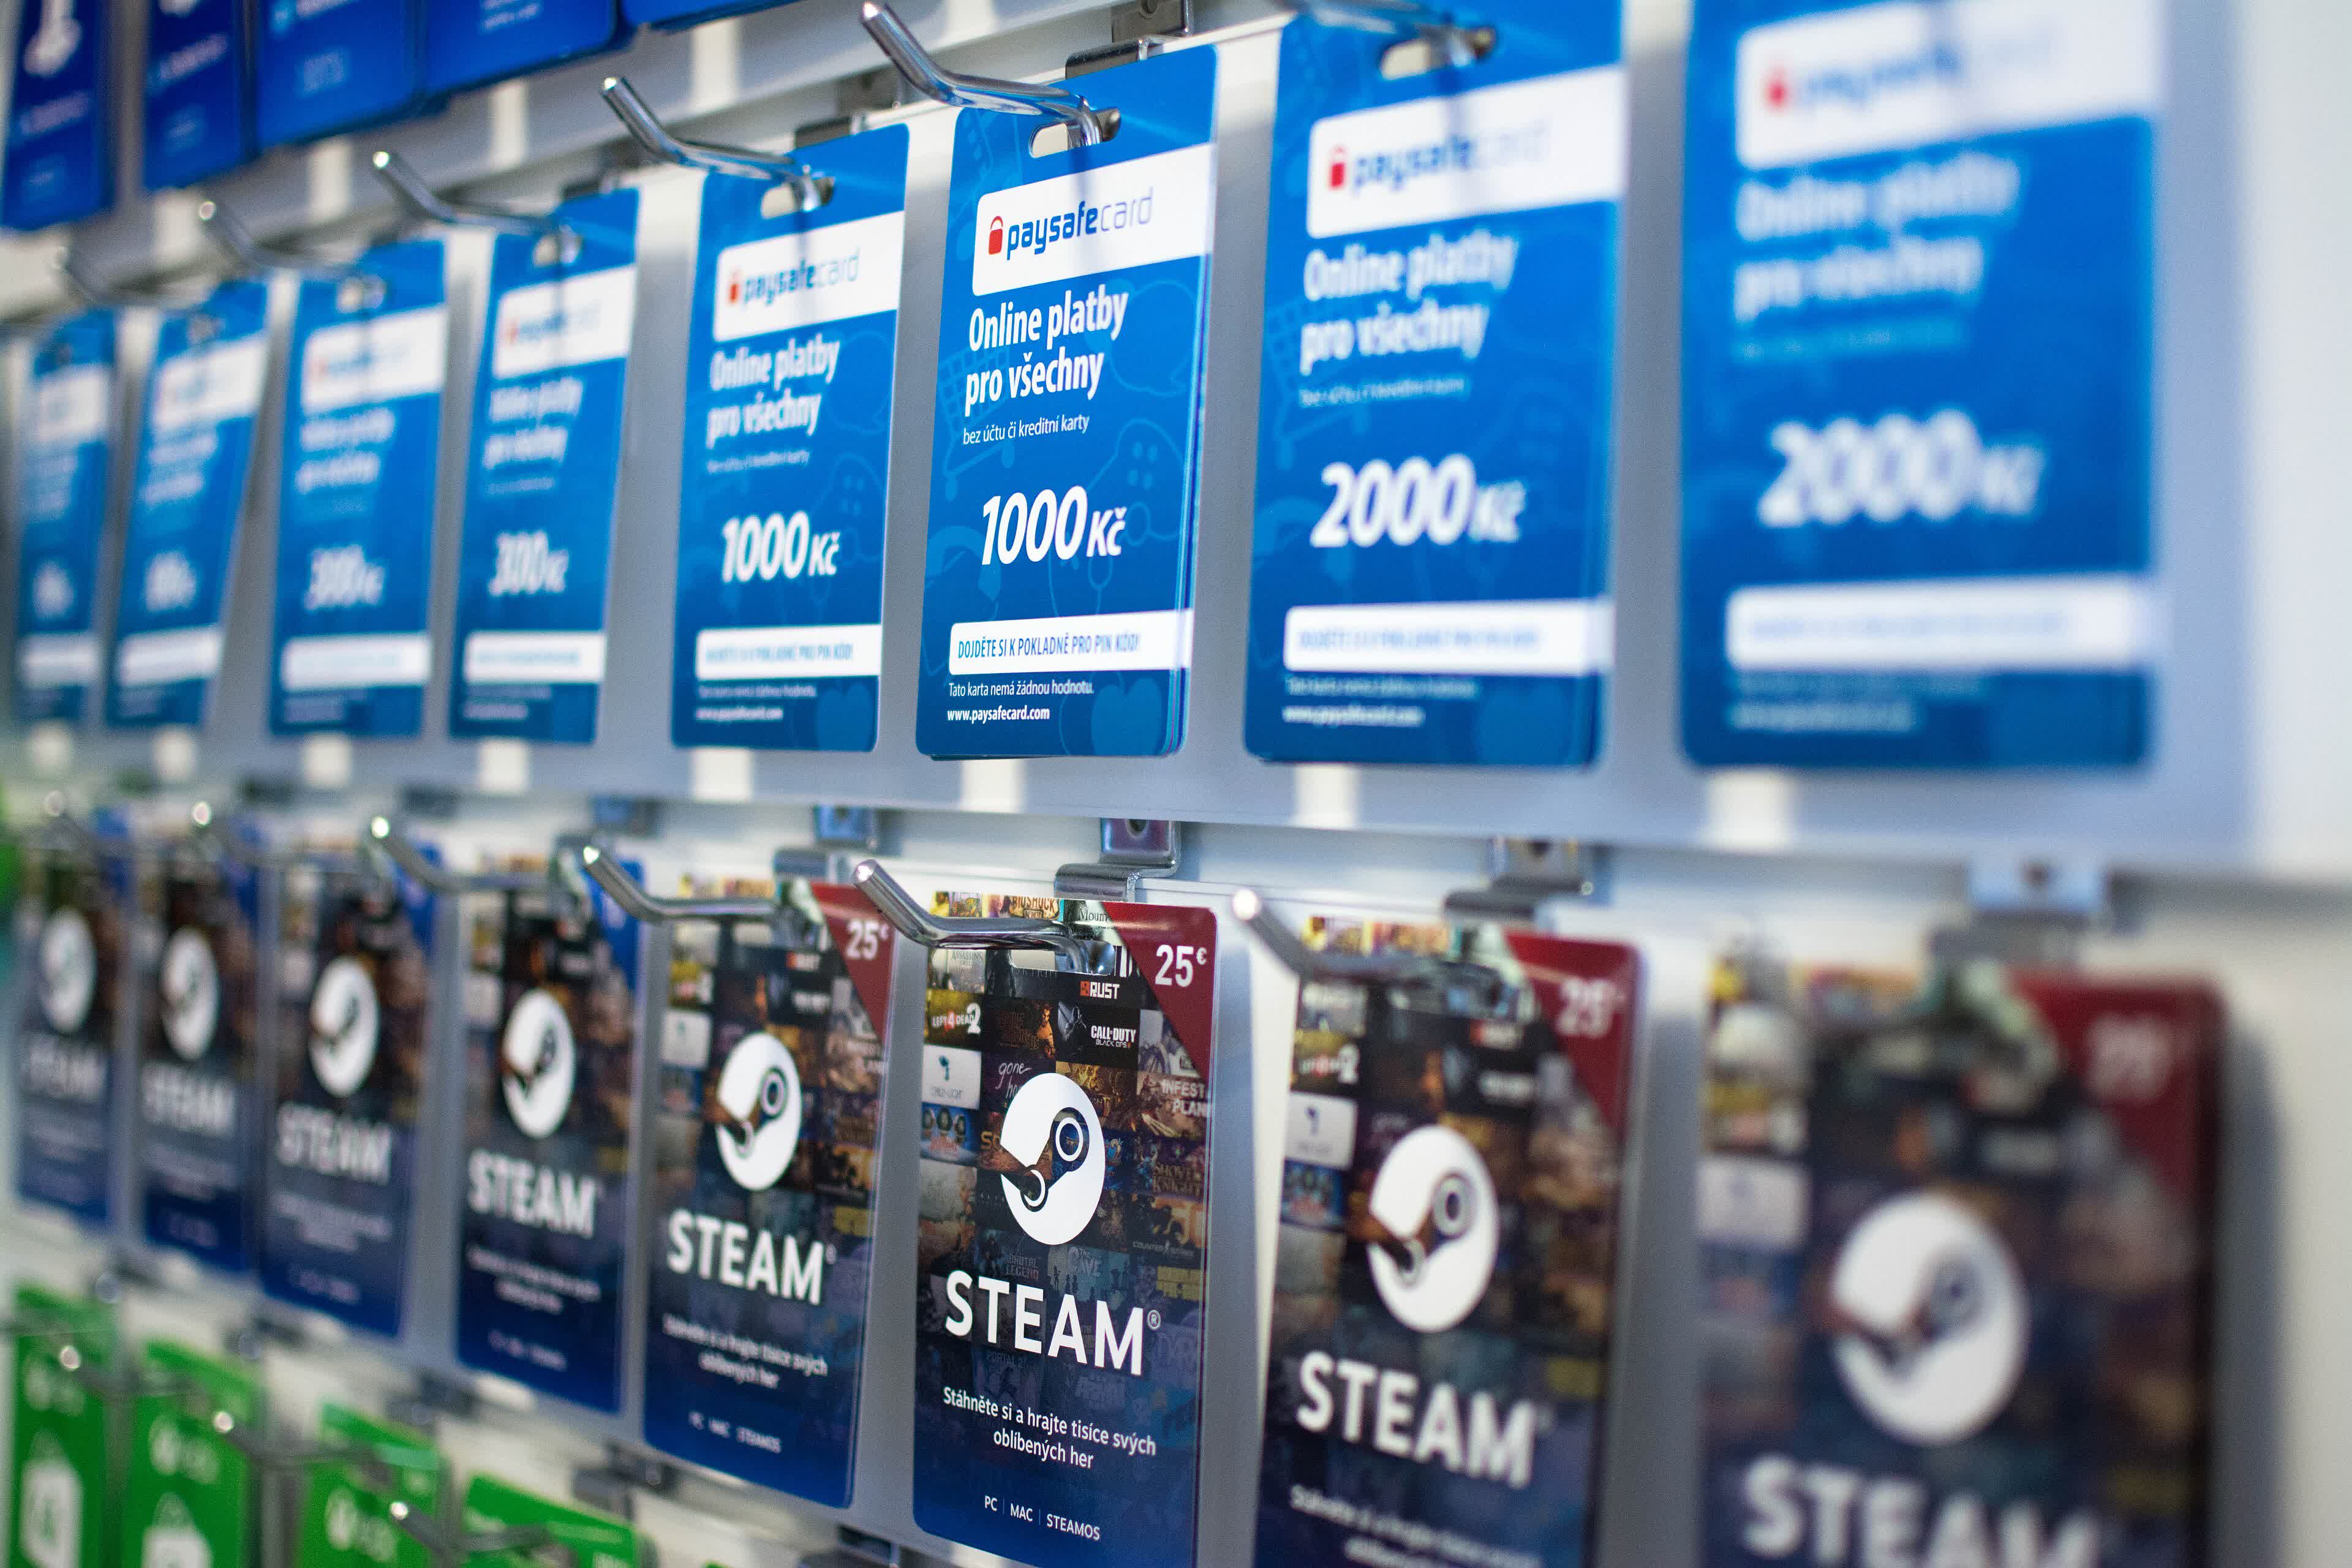
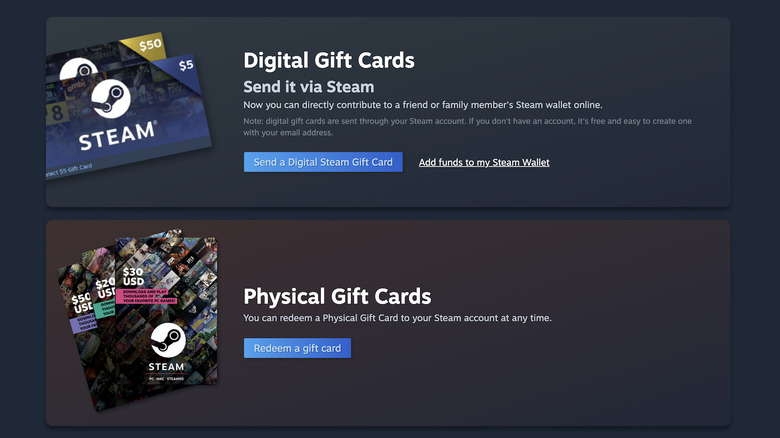
Valve's discontinuation of physical Steam gift cards by end of 2026 represents a watershed moment in digital commerce payment strategy, with direct implications for 200,000+ retailers globally and emerging opportunities for alternative payment solution providers. The company's decision, driven by persistent fraud exploiting physical card anonymity for money laundering and advance-fee scams, reflects a fundamental shift in how digital platforms balance security against accessibility. With existing stock depleting through 2026 and no restocking planned, retailers face immediate inventory management challenges while consumers lose a critical cash-based purchasing pathway—particularly impacting unbanked/underbanked demographics in emerging markets.
This creates three distinct seller opportunities: First, digital gift card fulfillment services represent an underserved niche. Platforms like Shopify, WooCommerce, and independent retailers currently lack robust white-label digital gift card solutions with fraud detection comparable to Steam's account-verification system. Sellers can capture market share by offering third-party digital gift card fulfillment with built-in anti-fraud monitoring, targeting the 15-20% of US consumers who prefer gift cards but lack credit cards. Second, gaming merchandise and collectibles will see demand acceleration as physical gift cards disappear. Sellers offering Steam-compatible gaming peripherals (controllers, headsets, gaming chairs), esports merchandise, and game-specific collectibles can position these as alternative gifting options. Historical data shows gaming merchandise categories grew 34% YoY during 2023-2024, with gift-giving occasions (holidays, birthdays) driving 40% of category volume. Third, payment infrastructure and fraud prevention tools targeting retailers represent a $500M+ addressable market. Sellers can develop or resell fraud-detection SaaS solutions, POS integration tools, and alternative payment gateways designed specifically for physical-to-digital payment transitions.
The broader market context reveals critical platform dynamics: Amazon, eBay, and Walmart have already reduced physical gift card inventory in favor of digital alternatives, signaling industry-wide consolidation. This creates a 12-18 month window for sellers to establish market position in digital payment solutions before major platforms (Apple, Google, Microsoft) potentially enter the retail gift card fulfillment space. Regional variations matter significantly—EU sellers face additional complexity due to GDPR compliance requirements for digital payment data, while Asia-Pacific sellers can capitalize on higher cash-payment adoption rates (60%+ in Southeast Asia) by offering localized digital alternatives. The fraud pattern Valve documented (scammers instructing victims to purchase cards, then reselling on gray markets) mirrors tactics used in Amazon gift card scams, suggesting platform-agnostic demand for fraud-resistant payment solutions.
Questions 8
Which seller categories benefit most from the shift to digital-only gifting?
Three categories see immediate opportunity: (1) Digital gift card fulfillment services—sellers can offer white-label solutions with fraud detection for retailers lacking in-house capabilities; (2) Gaming merchandise and collectibles—as physical gift cards disappear, gaming peripherals, esports merchandise, and game-specific collectibles become alternative gifting options, with gaming merchandise growing 34% YoY; (3) Payment infrastructure tools—fraud-detection SaaS, POS integration, and alternative payment gateways targeting retailers managing the physical-to-digital transition. Gaming merchandise sellers on Amazon, eBay, and Shopify should prioritize gift-friendly packaging and seasonal marketing during Q4 2024-2025 to capture displaced gift card demand.
What timeline should sellers follow to adapt to physical gift card discontinuation?
Valve's discontinuation timeline provides approximately 12 months (through end of 2026) for transition. Sellers should take immediate action (0-30 days) by auditing current gift card inventory and promotional strategies. Within 1-3 months, pivot marketing toward digital alternatives and gaming merchandise as gifting options. By Q2 2025, implement fraud-detection tools if offering digital payment solutions. The 12-18 month window allows sellers to test alternative gifting strategies, build customer awareness of digital options, and establish market position before major platforms (Apple, Google, Microsoft) potentially enter retail gift card fulfillment. Retailers should begin customer education campaigns immediately to normalize digital gift card adoption.