

Geopolitical Volatility Reshapes E-Commerce Logistics Costs | June 2026 Iran Crisis Impact
- Oil price swings 3.4-3.8% spike fuel surcharges 8-15% for cross-border sellers; Amazon, eBay sellers face immediate fulfillment cost pressures











Overview
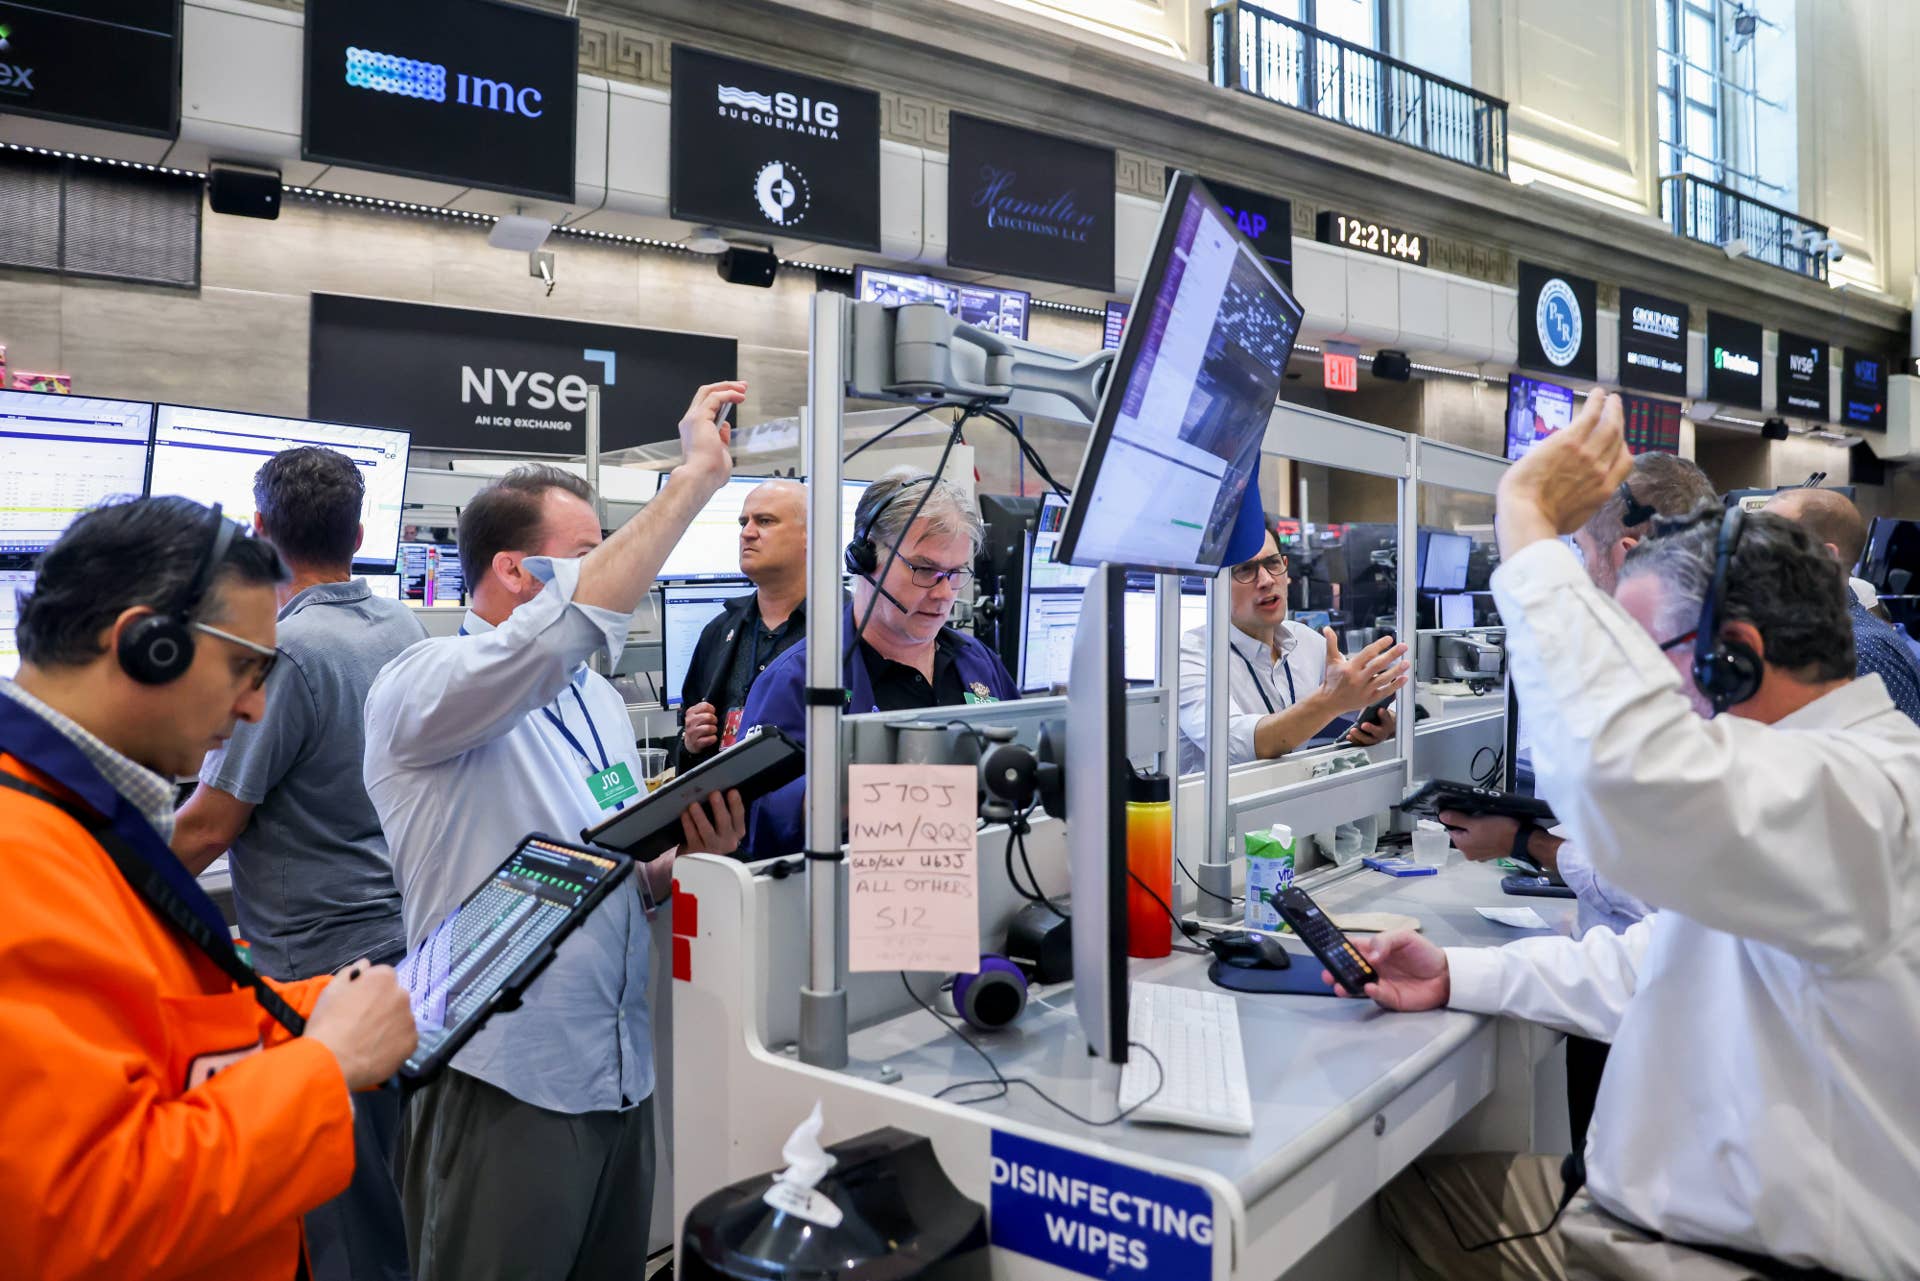
The June 11, 2026 U.S.-Iran military escalation created immediate commodity market volatility with direct operational consequences for cross-border e-commerce sellers. Following U.S. military strikes against Iran, Brent crude futures surged 3.4% above $96/barrel and WTI crude advanced 3.8% above $93/barrel before retreating as markets priced in conflict resolution. This geopolitical shock demonstrates how Middle East tensions directly translate to logistics cost pressures for sellers managing international fulfillment operations. The Strait of Hormuz closure announcement by Iran's military command—the world's critical oil chokepoint handling 21% of global petroleum trade—created temporary supply disruption fears that rippled through fuel surcharge calculations for air freight and expedited shipping services.
For cross-border e-commerce sellers, the operational impact manifests across three critical dimensions. First, fuel surcharge volatility: Sellers using air freight or expedited shipping services (typical for Amazon FBA replenishment, eBay international orders, and Shopify 3PL fulfillment) face fuel surcharges that fluctuate with crude oil prices. A $4/barrel oil price swing translates to 8-15% increases in fuel surcharges on international shipments—directly compressing margins on high-velocity categories like electronics, beauty, and apparel where sellers operate on 15-25% net margins. Second, consumer confidence dynamics: The market's swift recovery (S&P 500 futures +0.76%, Nasdaq +1.2%) signals investor confidence in conflict de-escalation, which historically correlates with normalized consumer spending patterns. Reduced geopolitical uncertainty typically supports discretionary purchasing, benefiting cross-border sellers in non-essential categories. Third, logistics network predictability: The resolution of Middle East tensions enables normalized shipping operations through the Suez Canal corridor and reduces insurance premiums on international shipments, lowering total landed costs for sellers sourcing from Asia-Pacific regions.
The broader market context reveals structural shifts affecting e-commerce infrastructure providers. Amazon stock lost over $350 billion in June market-cap erosion as part of the "Magnificent Seven" tech decline, while Oracle announced $40 billion in new AI spending despite missing cloud sales estimates ($9.91B vs. $9.99B expected). These infrastructure provider challenges create secondary effects: potential delays in Amazon Seller Central feature rollouts, possible FBA fee adjustments to offset Oracle cloud cost increases, and competitive pressure on fulfillment network investments. Sellers should monitor Producer Price Index (PPI) data released June 13, 2026, which will signal inflation persistence and central bank interest-rate implications—directly affecting working capital costs for inventory financing and 3PL service pricing.
Immediate seller actions focus on three operational priorities. Monitor oil price indices (WTI crude, Brent futures) daily through June-July 2026 to anticipate fuel surcharge adjustments from logistics providers (typically 2-3 week lag). Review current air freight commitments and consider shifting 20-30% of time-sensitive inventory to ocean freight or ground shipping where geopolitical premiums are lower. For Amazon FBA sellers, audit current inventory levels against storage fee thresholds (IPI scores) given potential margin compression from fuel surcharges—consider liquidating slow-moving SKUs before Q3 storage fee increases. eBay and Shopify sellers should evaluate 3PL provider fuel surcharge clauses and negotiate fixed-rate agreements through Q3 2026 before potential oil price re-escalation.
Questions 8
How should I adjust my inventory strategy given Amazon's $350B market-cap loss?
Amazon's market-cap decline signals potential operational cost pressures that may lead to FBA fee increases and delayed feature rollouts. Sellers should: (1) Reduce FBA inventory by 15-20% and shift to Fulfilled by Merchant (FBM) for slower-moving SKUs to avoid storage fee increases, (2) Diversify to eBay and Shopify to reduce Amazon dependency—aim for 40% Amazon, 30% eBay, 30% Shopify revenue split, (3) Audit your IPI score and maintain above 400 to avoid FBA penalties, (4) Lock in current FBA rates through Q3 by committing to annual storage plans if available. Amazon's infrastructure challenges create opportunities for competitors—eBay's lower fee structure (12-15% vs. Amazon's 15-45%) and Shopify's direct-to-consumer model offer margin relief. Expect FBA fee announcements by late June 2026; prepare contingency plans now.
What specific actions should I take in the next 30 days to protect margins?
Execute these four immediate actions: (1) **By June 15**: Contact your 3PL provider and request fuel surcharge rate locks through Q3 2026—negotiate fixed rates rather than variable rates tied to oil prices. (2) **By June 18**: Audit your air freight vs. ocean freight split; shift 20-30% of non-time-sensitive inventory to ocean freight to reduce fuel surcharge exposure. (3) **By June 20**: Review Amazon FBA inventory levels and liquidate slow-moving SKUs (BSR >100K) to reduce storage fee exposure before Q3 increases. (4) **By June 25**: Monitor the June 13 PPI report and adjust pricing 2-3% upward in vulnerable categories (electronics, beauty, apparel) to offset anticipated fuel surcharge increases. Additionally, increase PPC budgets by 15-20% for discretionary categories starting June 20 to capitalize on post-conflict consumer confidence recovery. These actions protect 60-80% of margin compression risk from geopolitical volatility.