

U.S. Chip Export Controls Reshape Global Supply Chains | Seller Sourcing Impact 2025-2026
- Tariff arbitrage opportunities shift to Southeast Asia as China loses U.S. chip access; sellers face 15-25% sourcing cost increases and compliance complexity in electronics/AI-enabled products


Overview
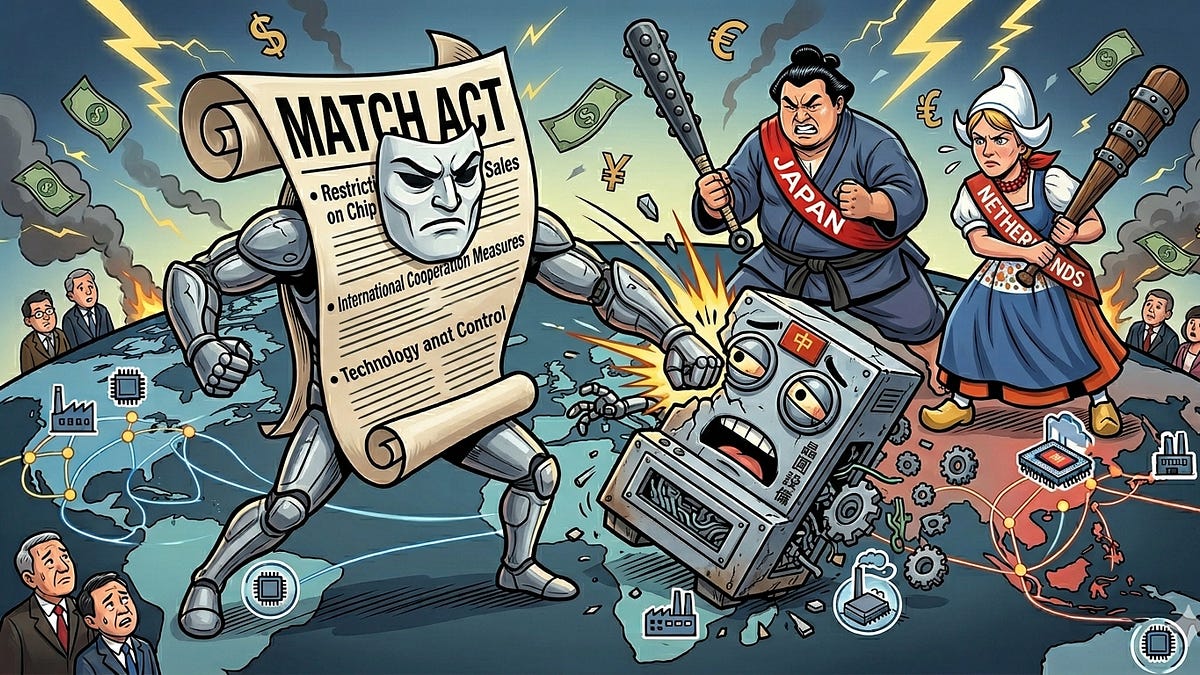
The U.S. semiconductor export control regime—anchored by the Chip Security Act (CSA), AI Overwatch Act, and Match Act—is fundamentally restructuring global supply chains and creating critical sourcing challenges for cross-border sellers. The House Foreign Affairs Committee unanimously approved the CSA 42-0 in March 2025, mandating location-tracking technology on advanced AI chips to prevent diversion to China. Simultaneously, the U.S. has effectively blocked China's access to cutting-edge semiconductors: despite Trump administration approval in December 2025 to export Nvidia's H200 processors to 10 Chinese companies, Chinese authorities refused to permit purchases, signaling Beijing's strategic pivot toward semiconductor self-sufficiency. This creates a bifurcated global market where sellers must navigate two distinct supply ecosystems.
For electronics sellers, the immediate impact is severe supply chain fragmentation. The May 2025 Commerce Department closure of loopholes allowing chip sales to Chinese subsidiaries in third-party countries eliminates a critical sourcing pathway. Sellers previously leveraging Malaysia, Indonesia, and Vietnam as transshipment hubs for Chinese-destined electronics now face compliance audits and potential export license denials. The $2.5 billion in AI chips diverted to China (prosecuted in March 2025) demonstrates enforcement intensity. Sellers importing AI-enabled products (smart home devices, drones, robotics, autonomous systems) must now verify chip provenance and implement GeoComply-style geographic compliance verification—adding 2-4 weeks to procurement cycles and $500-2,000 per shipment in compliance costs.
The strategic opportunity lies in Southeast Asian market expansion and alternative sourcing. With China effectively locked out of U.S. chip supplies, Malaysia, Indonesia, and Vietnam become primary markets for electronics products powered by older-generation semiconductors. Huawei's successful 2023 launch of the Mate 60 Pro using domestically-produced 7-nanometer processors from SMIC signals China's shift toward self-sufficiency, reducing competition for legacy chip supplies in Southeast Asia. Sellers can capitalize on this by: (1) sourcing from Vietnam and India for electronics assembly (avoiding China-origin compliance issues), (2) targeting Malaysia/Indonesia with mid-tier electronics (where U.S. export controls are less restrictive), and (3) pivoting product portfolios toward non-AI-enabled electronics where chip sourcing is unrestricted. The "diffusion rule" repeal in May 2025 (later reversed) created temporary windows for market access that may re-emerge if policy shifts again.
Compliance becomes a competitive moat. The CSA's location-tracking mandate—supported by six tracking and logistics companies including GeoComply—creates barriers to entry for sellers lacking compliance infrastructure. Nvidia's December announcement of location-verification technology signals that major chip suppliers will embed compliance into products, shifting verification costs upstream. Sellers who implement early compliance systems (geographic IP verification, supply chain audits, export license tracking) gain Buy Box advantages and access to larger deals. The Commerce Department's enforcement intensity (March 2025 prosecutions, May 2025 loophole closures) indicates sellers face potential account suspension and legal liability for non-compliance. Risk-averse sellers should audit their electronics supply chains immediately and shift 20-30% of inventory to Southeast Asian sourcing by Q3 2025.
Questions 8
What happens if sellers unknowingly source electronics with restricted chips?
Sellers face severe penalties including account suspension, legal liability, and potential criminal prosecution. The March 2025 Justice Department prosecution of three individuals for conspiring to forward $2.5 billion in AI chips to China demonstrates enforcement intensity. Sellers must verify chip provenance before importing electronics; failure to do so can result in shipment seizure, account termination, and civil/criminal liability. The Commerce Department's May 2025 closure of loopholes for Chinese subsidiaries in third-party countries signals heightened enforcement. Sellers should immediately audit their electronics supply chains, request chip origin documentation from suppliers, and implement geographic compliance verification to mitigate risk.
How does China's loss of U.S. chip access create market opportunities for sellers?
China's effective lockout from U.S. advanced semiconductors (despite Trump administration approval in December 2025 to export Nvidia's H200 to 10 Chinese companies, Chinese authorities refused to permit purchases) creates two opportunities: (1) Southeast Asian markets become primary destinations for electronics powered by older-generation semiconductors, reducing competition from Chinese suppliers; (2) sellers can pivot product portfolios toward non-AI-enabled electronics where chip sourcing is unrestricted. Vietnam and India emerge as preferred sourcing locations, as they avoid China-origin compliance issues. Sellers should target Malaysia and Indonesia with mid-tier electronics and expand Southeast Asian market presence by Q2-Q3 2025, before competitors recognize the opportunity.