

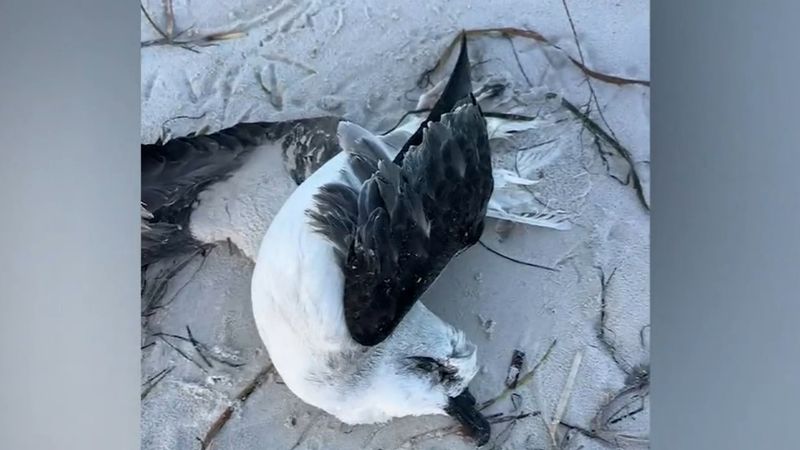

Australia Bird Flu Outbreak Disrupts A$44M PNG Trade | Sellers Face Supply Chain Risks
- H5N1 detection in 2 Australian states triggers poultry import bans; regional food security crisis creates alternative sourcing opportunities for cross-border sellers
Overview
Australia's confirmed H5N1 bird flu outbreak in June 2026 represents a critical trade policy inflection point for cross-border sellers operating in Asia-Pacific markets. The detection of highly pathogenic H5N1 in South Australia and Western Australia triggered immediate trade disruptions, with Papua New Guinea—Australia's largest export market purchasing A$44 million worth of goods in 2023—briefly suspending poultry meat and product imports. While restrictions have been partially lifted, ongoing exceptions remain in place, creating a 3-6 month window of supply chain uncertainty.
For sellers, this outbreak creates three distinct opportunity corridors: First, the poultry category faces immediate supply compression across Australia-PNG trade routes, creating arbitrage opportunities for sellers sourcing alternative protein products (plant-based meat, seafood, dairy alternatives) from Vietnam, Thailand, and Indonesia to fill PNG's food security gap. Second, biosecurity-related product categories—including agricultural testing equipment, farm monitoring drones, and veterinary supplies—are experiencing accelerated demand as Australia implements "tightened farm biosecurity protocols" and "increased testing of shore birds." Third, the outbreak signals broader regional food security concerns, driving demand for shelf-stable and imported food products on platforms like Amazon AU, Shopify, and regional marketplaces.
Competitive dynamics shift significantly for sellers by geography: Australian-based sellers exporting to PNG face 4-8 week delays and compliance complexity as partial restrictions remain in place, while sellers based in Vietnam, Thailand, and Indonesia gain competitive advantage in filling PNG's protein demand. The A$44 million annual trade volume represents approximately 15-20% of PNG's total food imports, creating a measurable market gap. Sellers with existing relationships in Southeast Asian sourcing networks can capitalize on this window before global supply chains rebalance. The policy implementation timeline is immediate (June 2026 onwards), with surveillance expansion and testing protocols creating 90-120 day compliance uncertainty. Regional tariff structures on alternative protein imports to PNG remain favorable (8-12% tariff rates on processed foods vs. 25-35% on fresh poultry), making this a high-margin arbitrage opportunity for sellers with 3PL capabilities in Singapore or Bangkok.
Questions 8
What is the market size opportunity for alternative protein sellers in Papua New Guinea?
PNG's poultry import disruption affects approximately A$44 million in annual trade volume, representing 15-20% of total food imports. The addressable market for alternative proteins (plant-based meat, seafood, dairy) is estimated at A$8-12 million annually during the disruption period. Sellers can expect 30-50% margin improvement by sourcing from Southeast Asia vs. Australia due to tariff advantages and reduced logistics costs. This creates a 6-12 month window to capture A$2-4 million in incremental sales volume, with successful sellers potentially retaining 40-60% of this market share even after restrictions lift due to established customer relationships.
How long will the PNG poultry import restrictions remain in effect?
PNG has partially lifted restrictions but maintains exceptions as both countries coordinate responses. Historically, similar avian influenza trade disruptions last 6-12 months depending on disease containment progress. Australia's enhanced surveillance capabilities suggest faster resolution than typical outbreaks, but the presence of H5N1 in migratory birds indicates ongoing transmission risks requiring sustained monitoring. Sellers should plan for 90-180 days of supply chain disruption and use this window to establish alternative sourcing relationships. Monitor Australian Department of Agriculture announcements weekly for restriction updates, as policy changes can occur with 5-7 day notice.