




Big Tech Data Center Backlash & U.S. Fiscal Crisis | E-Commerce Infrastructure Risk & Seller Cost Pressures
- Investor confidence collapse in Amazon, Microsoft, Meta threatens cloud service pricing stability; U.S. federal debt at 120% GDP by 2036 signals tariff/compliance cost increases for cross-border sellers






Overview
Critical Infrastructure & Cost Pressures Converging on E-Commerce Sellers
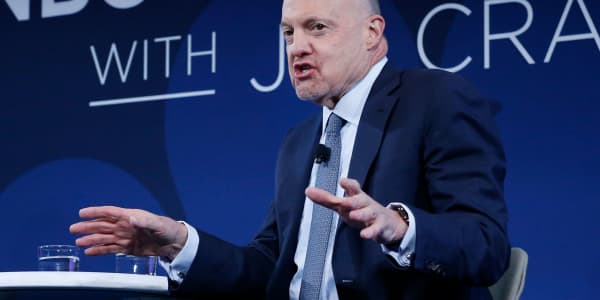
The June 2026 news cycle reveals two interconnected crises threatening e-commerce operational costs and platform stability. First, Big Tech's "Magnificent Seven" (Amazon, Microsoft, Meta, Apple, Alphabet) face a perfect storm of investor skepticism around massive data center buildouts, with Jim Cramer's June 28, 2026 CNBC analysis highlighting bipartisan political opposition to hyperscaler expansion, widespread AI job displacement anxiety, and narrative corruption that's driving valuations downward despite strong underlying businesses. This sentiment collapse directly impacts Amazon Web Services (AWS), Microsoft Azure, and Meta's infrastructure services—the backbone of millions of e-commerce operations globally. When Big Tech stock valuations compress due to negative sentiment (not operational weakness), these companies face pressure to monetize infrastructure more aggressively through higher cloud service fees, storage costs, and compute pricing.
Simultaneously, U.S. fiscal deterioration compounds seller cost pressures: United Overseas Bank's analysis projects federal debt reaching 120.21% of GDP by 2036, with the Iran war costing ~$25 billion (as of April 29, 2026) and the Trump administration's 10% global tariff proposal facing constitutional challenges following the Supreme Court's ruling on International Emergency Economic Powers Act tariffs. Corporate debt issuance hit $956 billion by May 2026 (43% year-on-year increase), signaling capital markets stress. This fiscal environment creates three direct seller impacts: (1) Tariff uncertainty—the 10% global tariff proposal may be insufficient to offset revenue losses, leaving sellers exposed to unpredictable duty costs on imports; (2) Compliance cost inflation—higher government yields and debt service requirements historically precede stricter customs enforcement and VAT audits; (3) Platform fee pressure—Amazon, Shopify, and other platforms may increase seller fees to offset rising infrastructure costs and maintain margins amid investor pressure.
The Honeywell Aerospace spinoff (June 2026) provides a secondary indicator: TD Cowen's Hold rating and concerns about "profit leverage" suggest aerospace/defense suppliers face margin compression, which cascades to logistics providers and supply chain partners that e-commerce sellers depend on. AIRO Group Holdings ($88M revenue, 87.6% from drones/avionics), Dragonfly Energy Holdings ($55M revenue, lithium batteries for RVs/marine), and AML3D (42.9% forecasted revenue growth in 3D printing for aerospace) all face execution risks and funding challenges—signaling potential supply chain disruptions for sellers in electronics, automotive accessories, and industrial categories.
For e-commerce sellers, the convergence means: AWS/Azure pricing pressure within 6-12 months; tariff cost volatility through 2026-2027; potential platform fee increases to offset Big Tech valuation pressure; and supply chain tightness in aerospace-dependent logistics. Sellers relying on Amazon FBA, Shopify Plus, or Microsoft-powered fulfillment should monitor quarterly earnings calls for infrastructure cost guidance.
Questions 8
What immediate actions should sellers take in June-July 2026 to mitigate these risks?
Immediate actions (0-30 days): (1) Audit current AWS/Azure/Shopify costs and model 10-15% increases; (2) Review supplier contracts for tariff pass-through clauses and renegotiate if needed; (3) Calculate landed costs assuming 12-15% tariff rates, not 10%; (4) Request quotes from 2-3 alternative 3PL providers for cost comparison; (5) Review FBA fee structure and identify slow-moving SKUs for 3PL migration; (6) Ensure customs documentation (origin certificates, HS codes, supplier invoices) is audit-ready. Strategic adjustments (1-6 months): (1) Diversify sourcing to tariff-advantaged regions; (2) Build DTC presence on Shopify/WooCommerce; (3) Negotiate volume discounts with platforms before Q3 2026; (4) Increase inventory buffers for aerospace-linked suppliers by 20-30%; (5) Evaluate hybrid fulfillment models. The convergence of Big Tech valuation pressure, fiscal stress, and aerospace supply chain weakness creates a 6-12 month window for proactive cost management before fee increases materialize.
How does the aerospace sector consolidation affect drone and battery sellers?
Honeywell Aerospace's spinoff signals consolidation across aerospace supply chains. AIRO (drone platforms, $77.1M revenue) and Dragonfly Energy (lithium batteries, $54.98M revenue) face margin pressure as larger OEMs consolidate suppliers. Sellers in these categories should expect: (1) **Reduced pricing power**: Customers demand 5-10% volume discounts as they consolidate suppliers; (2) **Longer sales cycles**: Aerospace OEMs conduct extended due diligence on independent suppliers; (3) **Increased compliance requirements**: Defense/aerospace customers require AS9100 certification, ITAR compliance, and enhanced quality controls. Sellers should invest in certifications (AS9100, ISO 9001) and quality systems to differentiate from competitors. Diversify customer base: aerospace OEMs represent 60-70% of revenue for many suppliers; target commercial aviation, defense contractors, and space companies to reduce concentration risk.