



German Auto Market Collapse in China | Supply Chain Disruption & Aftermarket Parts Opportunity
- Volkswagen, BMW, Mercedes-Benz face steep sales declines as Chinese EV makers gain 40%+ market share; creates $2-4B aftermarket parts opportunity for cross-border sellers


Overview
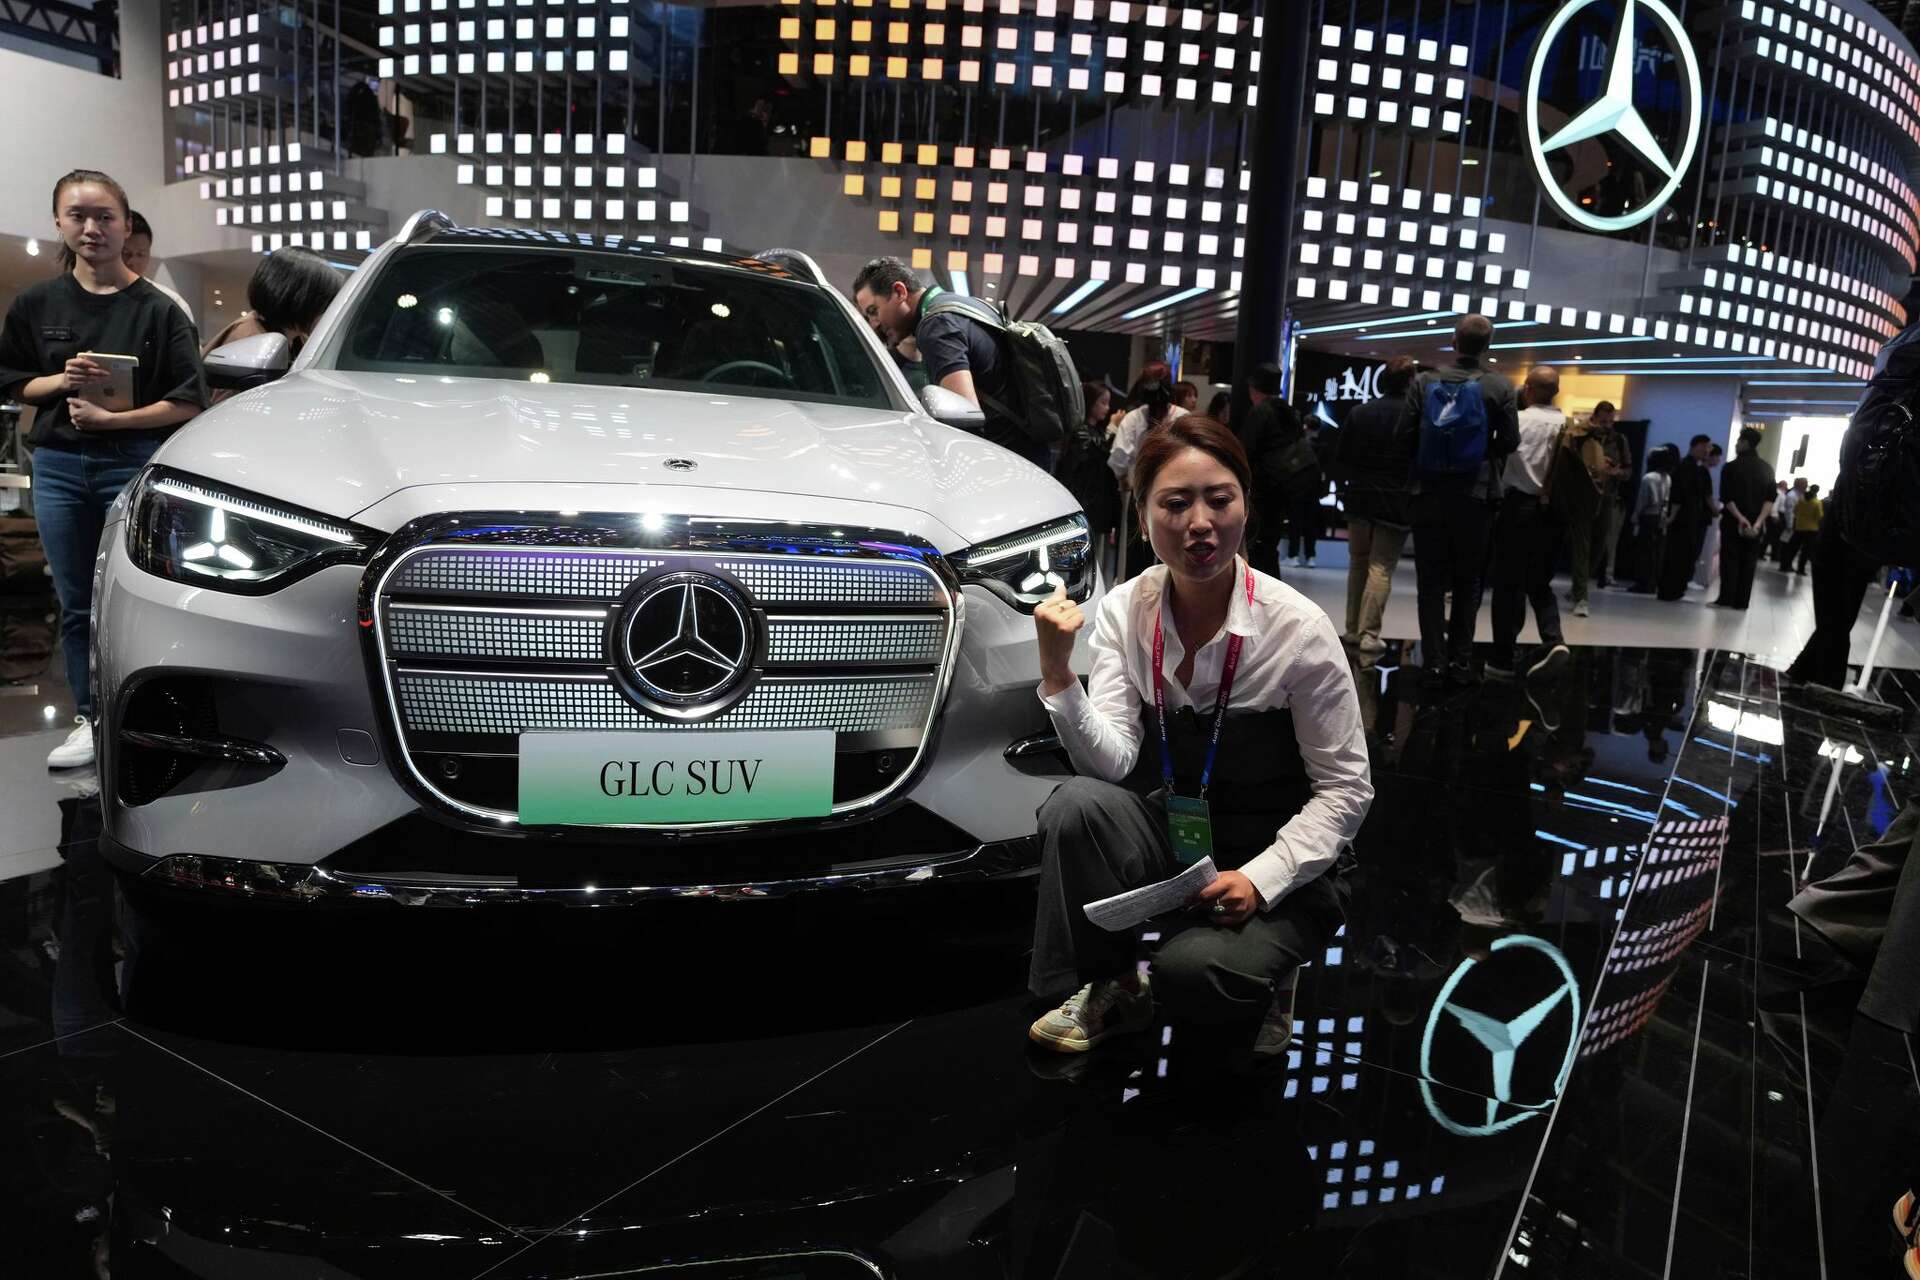
German automotive manufacturers are experiencing a critical market collapse in China, with Volkswagen, BMW, and Mercedes-Benz reporting steep sales declines as domestic Chinese competitors and new EV entrants capture market share. This represents a fundamental shift in global automotive dynamics with cascading implications for cross-border e-commerce sellers across multiple product categories.
The competitive pressure stems from Chinese manufacturers' rapid advancement in electric vehicle technology, autonomous driving capabilities, and price-competitive positioning. Volkswagen's strategic response—reducing its brand portfolio to streamline operations—signals management expects prolonged market challenges rather than temporary fluctuations. This consolidation strategy reflects the severity of competitive pressure, with Chinese EV makers now offering comparable technology at 30-40% lower price points. Industry analysts project German carmakers will accelerate innovation cycles, particularly in EV development and autonomous systems, requiring massive R&D investments that will strain profitability.
For cross-border e-commerce sellers, this creates a critical supply chain disruption opportunity in automotive aftermarket parts and accessories. As German carmakers lose market share in China, their component suppliers and logistics providers face reduced OEM demand. Simultaneously, the surge in Chinese EV adoption creates explosive demand for: (1) EV charging accessories and cables (HS 8544.30), (2) battery management system components (HS 8534), (3) automotive electronics and control modules (HS 8537), and (4) replacement parts for aging German vehicle fleets in secondary markets. Chinese sellers are already capturing this demand through Alibaba, Amazon, and emerging platforms like Temu and Shein, which now feature automotive categories.
The market shift also creates tariff arbitrage opportunities. As German OEM production declines in China, tariff-advantaged sourcing from Vietnam, India, and Thailand for automotive components becomes more attractive. Sellers can exploit the 5-8% tariff differential between Chinese-origin and ASEAN-origin automotive parts (HS codes 8708.30-8708.99) by shifting sourcing to Vietnam or India, improving margins by $15-40 per unit depending on category. The timing window is critical: German carmakers' brand consolidation typically takes 12-18 months to implement, creating a 6-12 month window before supply chain adjustments fully materialize.
Competitive dynamics favor small-to-medium sellers (SMEs) with agility to pivot sourcing and product mix. Large multinational suppliers face legacy contracts and production commitments to German OEMs, limiting flexibility. SMEs can rapidly source EV-related components from emerging Chinese suppliers (now offering 20-30% cost advantages over German suppliers) and sell through Amazon, eBay, and Shopify to global markets. The geographic shift in automotive manufacturing power toward Asia creates a 3-5 year window where Chinese and ASEAN-based suppliers can establish market dominance before German carmakers stabilize their competitive position.
Questions 7
Which seller segments (SMEs vs. large suppliers) have competitive advantages in this market shift?
Small-to-medium sellers (SMEs) have significant competitive advantages over large multinational suppliers due to operational agility. Large suppliers face legacy contracts and production commitments to German OEMs, limiting their ability to pivot sourcing and product mix. SMEs can rapidly source EV-related components from emerging Chinese suppliers (offering 20-30% cost advantages) and sell through Amazon, eBay, and Shopify to global markets. SMEs also benefit from lower overhead costs, allowing them to compete on price in price-sensitive segments where Chinese competitors excel. Large suppliers typically require 18-24 months to restructure operations, while SMEs can execute sourcing changes within 4-8 weeks. This creates a 12-18 month window where SMEs can establish market dominance before larger competitors respond.
What specific Amazon FBA strategies should sellers use for automotive aftermarket parts?
Sellers should focus on high-velocity, low-weight EV charging accessories and battery components that qualify for Amazon FBA's standard fulfillment. EV charging cables (HS 8544.30) and adapters have 40-60% annual growth and ship efficiently through FBA networks. Create separate ASINs for different voltage specifications (110V, 220V, 380V) to capture regional demand variations. Use Amazon's automotive category filters to target buyers searching for specific vehicle models and EV types. Implement competitive pricing strategies leveraging 5-8% tariff advantages from ASEAN sourcing. Monitor Buy Box competition closely, as margins compress quickly in high-velocity categories. Consider Fulfillment by Amazon (FBA) for products under $50 to maximize Prime eligibility and conversion rates, which typically run 2-3x higher than Fulfilled by Merchant (FBM) options.