


AI Infrastructure Compliance Costs | $100M+ Annual Burden for Data Center Operators
- Wisconsin PSC mandates A-/A3 credit ratings or cash collateral for data center developers; Oracle faces $100M+ annual compliance costs; regulatory precedent threatens $1.2T AI infrastructure investment timeline










Overview
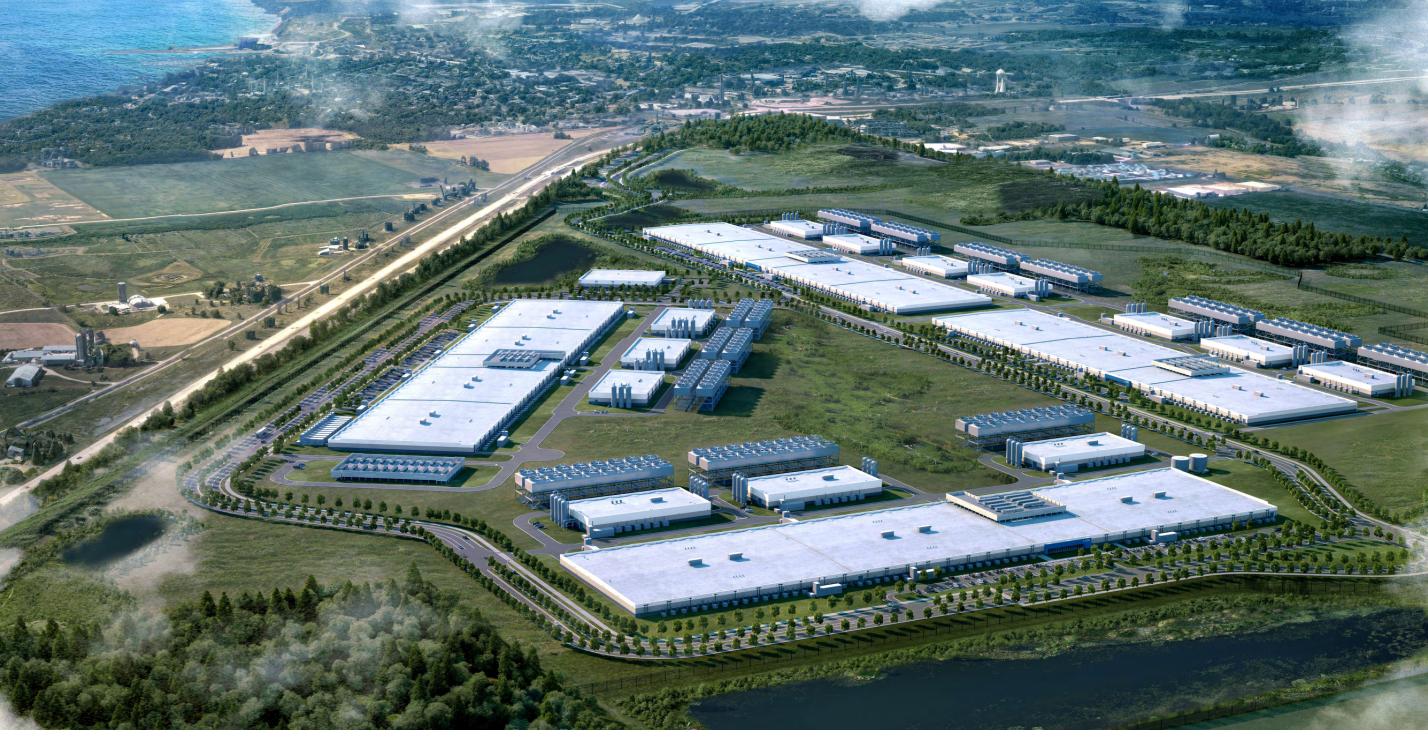
Wisconsin's Public Service Commission has established a critical regulatory precedent that will reshape AI infrastructure compliance costs across the United States. In April 2024, Wisconsin regulators approved rate structures requiring data center developers to maintain credit ratings of A- or A3, or post substantial cash collateral—a requirement that directly triggered Oracle's July 9 credit rating downgrade to BBB- (junk-adjacent status). Oracle claims these requirements impose costs exceeding $100 million annually and has sued the PSC to challenge them, but the regulatory framework signals a broader shift toward financial accountability requirements for large-scale infrastructure projects.
This regulatory model creates a critical compliance barrier with direct implications for e-commerce infrastructure and seller operations. The Wisconsin precedent establishes that utility regulators can mandate financial safeguards for data center projects, effectively creating a two-tier system: compliant operators with A-/A3 ratings (Microsoft, Alphabet, Amazon with stronger balance sheets) and non-compliant operators forced to post cash collateral or exit markets. For e-commerce sellers, this translates to potential cost increases in cloud infrastructure pricing, AI-powered fulfillment services, and logistics optimization tools—all dependent on data center availability and pricing. S&P projects Oracle's free cash flow deficit will widen to $34.2 billion by fiscal 2027, indicating the company may reduce capital expenditures or divest non-core assets, potentially affecting Oracle Cloud Infrastructure (OCI) pricing and service availability for sellers using OCI-based e-commerce platforms.
The competitive advantage shifts decisively toward financially stronger tech giants. S&P explicitly warns that Oracle's competitors (Microsoft, Alphabet, Amazon, Meta) have greater financial flexibility to outspend the company, creating structural competitive disadvantages. Industry-wide, five major tech companies plan to invest over $1.2 trillion in AI next year, but regulatory compliance costs will compress margins for weaker-capitalized operators. For e-commerce sellers, this consolidation means fewer infrastructure providers, potentially higher pricing for cloud services, and reduced negotiating power. Additionally, S&P identifies OpenAI as a key credit risk—if OpenAI cannot meet its obligations under the $500 billion Stargate partnership, Oracle could be burdened with massive data center leases it cannot exit, creating cascading service disruptions for dependent platforms and sellers.
Sellers should monitor three critical compliance-driven market shifts: (1) Data center pricing increases as operators pass compliance costs to customers; (2) Consolidation of infrastructure providers, reducing competitive pricing pressure; (3) Potential service disruptions if weaker operators exit markets or face financial stress. The Wisconsin model will likely spread to other states with major data center projects, creating a patchwork of regional compliance requirements. Sellers using cloud-dependent services (Amazon Web Services, Microsoft Azure, Google Cloud) should expect pricing adjustments within 12-18 months as these companies absorb regulatory compliance costs and pass them downstream.
Questions 8
What immediate actions should sellers take in response to Oracle's credit downgrade and regulatory pressure?
Sellers should take three immediate actions: (1) Audit cloud service dependencies—identify which platforms rely on Oracle, Amazon, Microsoft, or Google infrastructure and assess pricing vulnerability; (2) Evaluate multi-cloud strategies to reduce single-provider dependency; (3) Monitor Oracle's quarterly earnings and capital expenditure announcements for signs of service reductions or pricing increases. Within 30 days, sellers should request pricing guarantees from cloud providers and negotiate multi-year contracts before compliance costs are fully passed through. Within 90 days, sellers should develop contingency plans for service disruptions and identify alternative fulfillment or logistics providers.
How does the $1.2 trillion AI infrastructure investment affect e-commerce seller costs?
Five major tech companies (Microsoft, Alphabet, Amazon, Meta, Oracle) plan to invest over $1.2 trillion in AI next year, exceeding U.S. national defense spending. However, regulatory compliance costs (like Wisconsin's requirements) will compress margins for weaker operators and increase pricing for all customers. E-commerce sellers should expect: (1) Higher cloud infrastructure costs as operators pass compliance expenses downstream; (2) Consolidation of providers, reducing competitive pricing; (3) Potential service disruptions if weaker operators exit markets. Sellers in high-margin categories (luxury goods, electronics) can absorb cost increases; sellers in low-margin categories (apparel, home goods) should evaluate alternative fulfillment strategies.