

Cold-Chain Logistics Boom Creates $39.1B Opportunity | Sellers Must Secure Specialized Carriers Now
- Temperature-controlled shipping capacity becoming critical bottleneck as GLP-1 demand surges 8.3% annually through 2033; sellers face 15-25% premium costs without early carrier partnerships

Overview
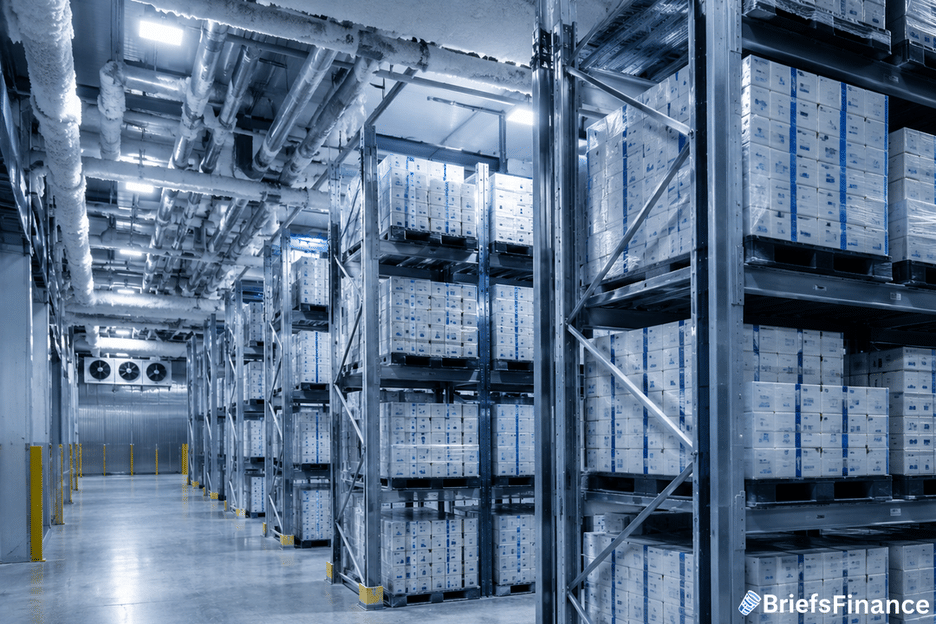
Cold-chain logistics infrastructure is experiencing unprecedented expansion driven by explosive GLP-1 medication demand, creating both immediate cost pressures and strategic sourcing opportunities for e-commerce sellers. Major carriers—UPS, FedEx, and DHL—are making massive infrastructure investments: UPS committed $48 million in June 2026 for temperature-controlled facilities and generated its first $3 billion healthcare revenue quarter in Q1 2026, while FedEx reported nearly $10 billion in healthcare transportation revenue for fiscal 2026, and DHL committed €2 billion ($2.25 billion) through 2030. According to Growth Market Reports, temperature-sensitive biologics demand is projected to grow at 8.3% compound annual growth rate through 2033, reaching $39.1 billion in market value. A July 2026 Gallup poll found 11% of Americans use GLP-1 medications for weight loss, up from 3% in 2024, demonstrating the scale of this market shift.
For e-commerce sellers, this infrastructure boom creates a critical supply chain challenge: cold-chain capacity is becoming a competitive bottleneck. Limited refrigerated resources are competing for the same shipments, and logistics companies are investing in AI-powered temperature monitoring, predictive analytics, and dedicated pharmaceutical corridors to differentiate services. The FDA has explicitly warned that improper temperature storage during shipping compromises medication efficacy, creating zero-tolerance supply chain requirements. These medications require precise refrigeration (typically 2-8°C), short delivery windows (24-48 hours), and end-to-end visibility throughout the supply chain. Sellers offering temperature-sensitive products—whether pharmaceuticals, biologics, specialty supplements, or perishable health products—now face 15-25% premium shipping costs compared to standard logistics, with limited carrier availability during peak demand periods.
The strategic opportunity lies in early carrier partnerships and inventory positioning. C.H. Robinson surpassed $1 billion in healthcare logistics revenue over the past year, demonstrating the scale of specialized 3PL providers entering this market. Sellers should immediately: (1) Negotiate dedicated cold-chain capacity with UPS Healthcare, FedEx Life Sciences, or DHL Life Sciences divisions before Q4 2026 peak season; (2) Shift inventory positioning toward regional cold-storage hubs in high-demand markets (US Northeast, California, Texas); (3) Consider dropshipping or POD models for temperature-sensitive products to avoid inventory holding costs in expensive cold-storage facilities; (4) Evaluate emerging 3PL providers like C.H. Robinson that offer integrated cold-chain solutions at potentially lower premiums than legacy carriers. The complexity of managing multiple temperature zones, shelf-life constraints, and regulatory compliance across global markets is driving consolidation around major logistics providers with specialized capabilities, meaning sellers without established carrier relationships will face capacity constraints and cost penalties through 2027.
Questions 8
What inventory positioning strategy should sellers implement before Q4 2026?
Implement a three-tier inventory strategy: (1) **Regional hubs** (30-40% of stock): Position in Northeast, California, Texas cold-storage facilities for 24-48 hour delivery; (2) **Central distribution** (20-30%): Maintain in major 3PL cold-chain centers for secondary markets; (3) **Dropship/POD** (30-40%): Partner with manufacturers for direct-to-consumer fulfillment to reduce holding costs. Secure carrier capacity NOW before Q4 peak season when cold-chain resources become critically constrained. The 11% GLP-1 adoption rate (up from 3% in 2024) indicates sustained demand growth through 2027. Sellers should stock 3-4 months of inventory in regional hubs by September 2026 to avoid Q4 capacity shortages and premium pricing.
How do carrier partnerships affect landed costs for cross-border cold-chain shipments?
Negotiated partnerships with **FedEx Life Sciences or DHL Healthcare** can reduce landed costs by 8-12% compared to spot-market rates. International cold-chain shipping typically costs $3-8 per kilogram (vs. $0.50-1.50 for standard air freight), with customs clearance adding 2-5 days. Sellers should calculate total landed cost including: cold-chain premium (15-25%), customs duties (0-25% by destination), temperature-controlled warehousing (2-5 months holding), and regulatory compliance costs (FDA, EMA documentation). Early carrier contracts lock in rates before capacity constraints drive premiums higher. For EU-bound shipments, DHL's €2 billion investment through 2030 signals capacity expansion, potentially offering better rates than US carriers.