


Amazon Pharmacy GLP-1 Expansion Reshapes Weight-Loss Market | Seller Opportunities in Complementary Health Categories
- Amazon launches $50/month GLP-1 medications to 3,100+ U.S. cities; creates $2B+ complementary product opportunity for health supplement and fitness equipment sellers targeting newly eligible Medicare beneficiaries















Overview
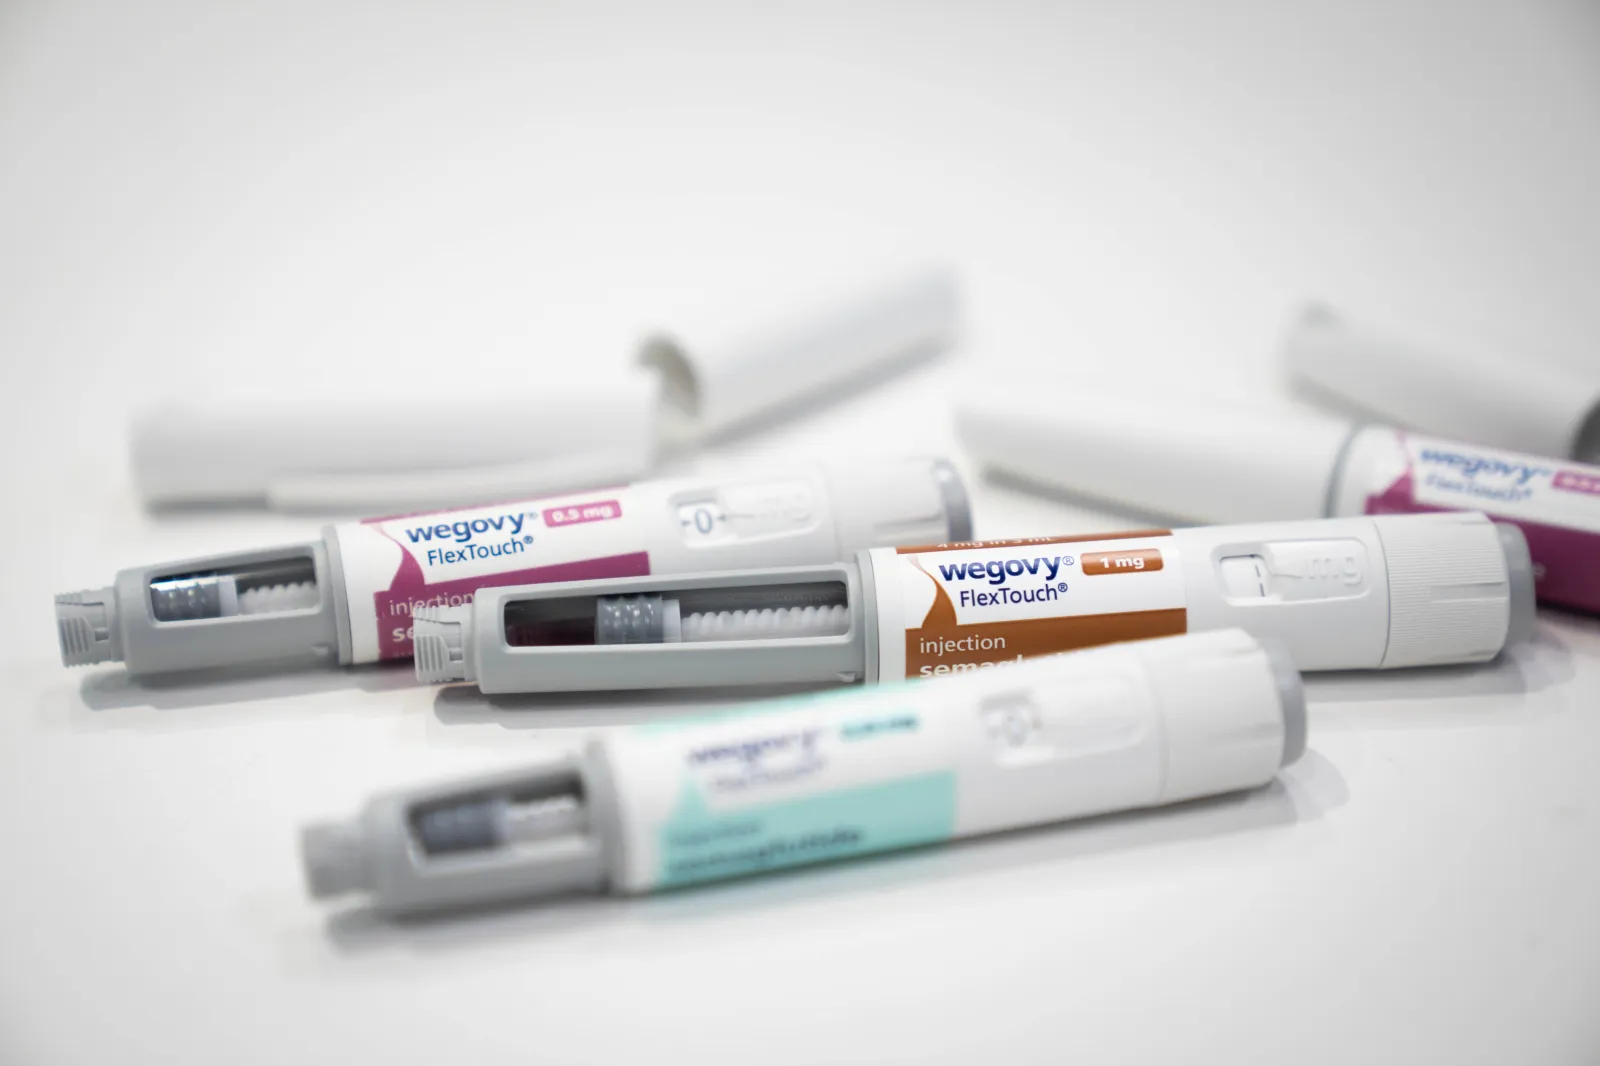
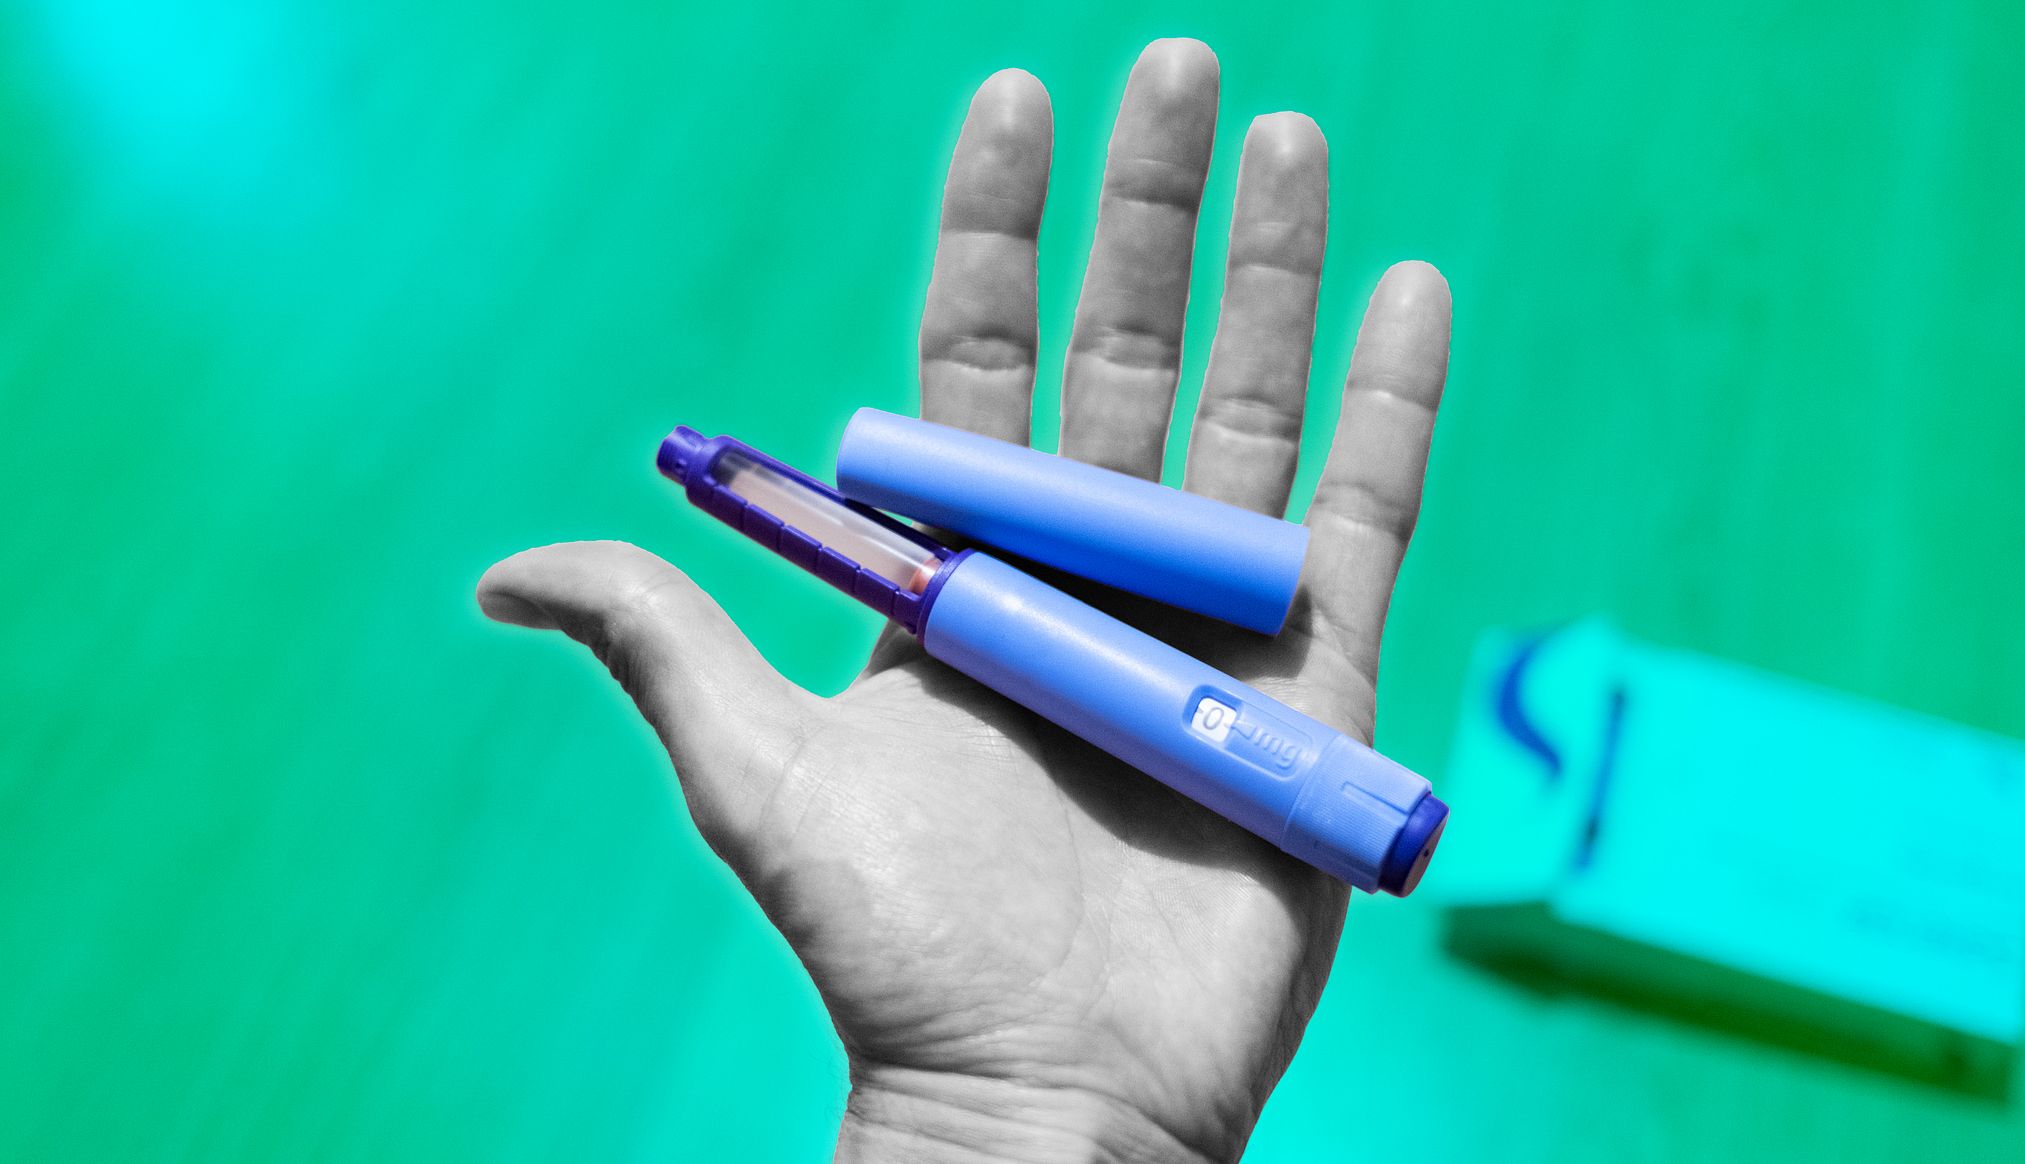
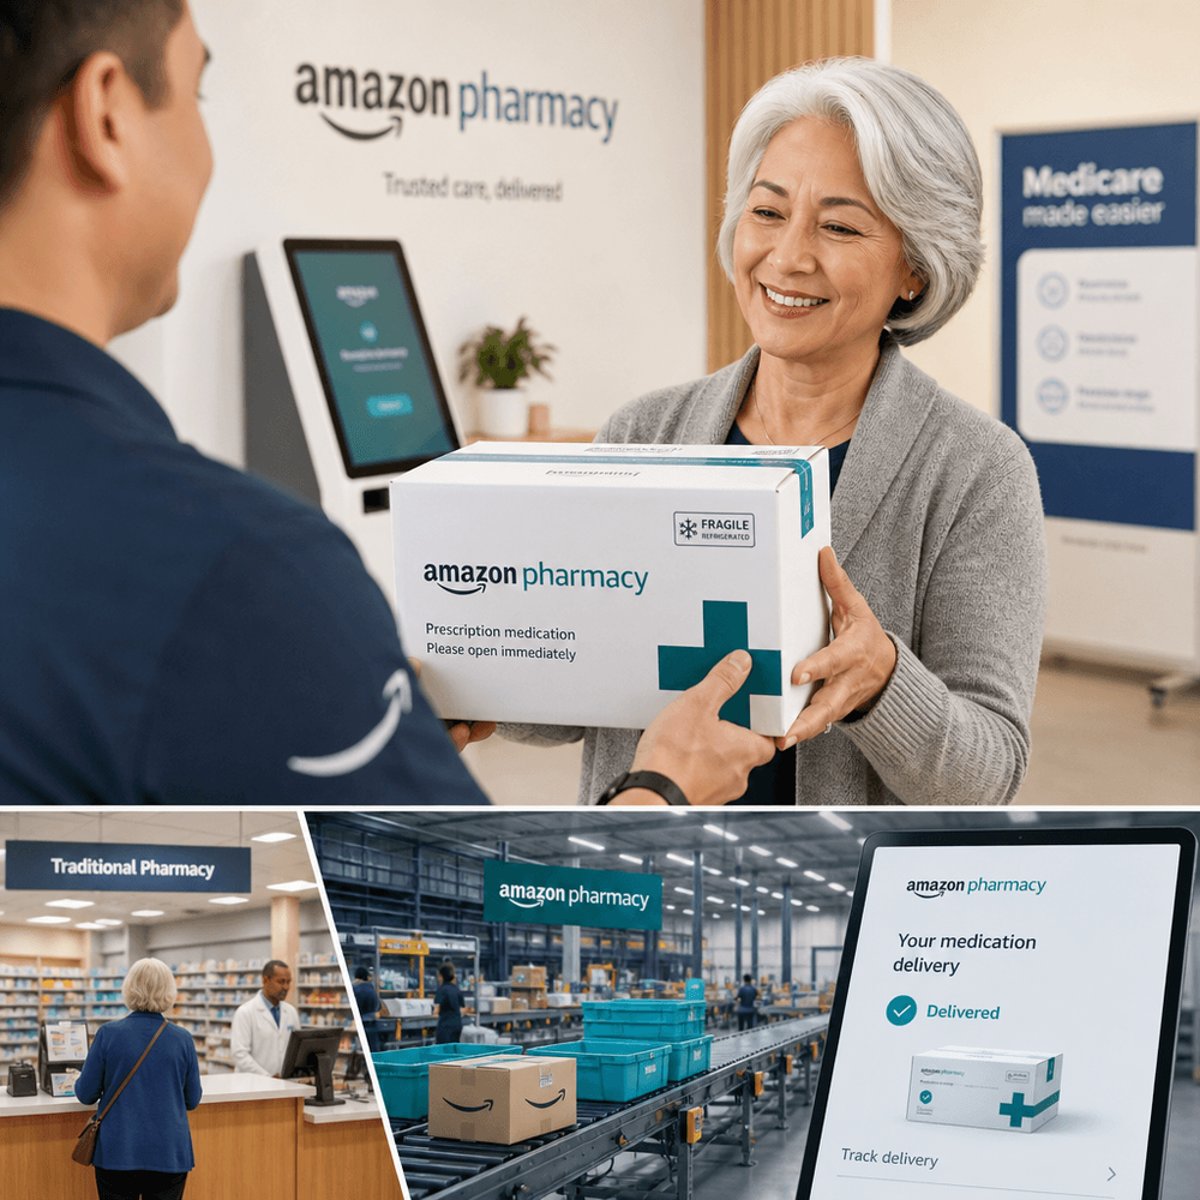
Amazon's aggressive entry into GLP-1 pharmaceutical distribution through its Medicare Part D Bridge Program represents a watershed moment for e-commerce sellers in health and wellness categories. The company now delivers semaglutide (Wegovy), tirzepatide (Zepbound), and Foundayo at $50/month with same-day delivery in 3,100+ U.S. cities, expanding to 104,500 locations by end of 2026. This $50 copay cap—down from $300-$1,000 monthly retail prices—creates a dual market dynamic: prescription medications cannibalize over-the-counter weight-loss products while simultaneously expanding total addressable market for complementary health categories. The Medicare GLP-1 Bridge Program runs through December 31, 2027, targeting 10+ million eligible beneficiaries with substantial purchasing power.
For cross-border e-commerce sellers, this development signals three critical shifts. First, Amazon's vertical integration into healthcare logistics demonstrates the platform's capability to handle complex regulatory workflows (FDA compliance, prior authorization automation, Medicare eligibility verification) at scale—setting new operational standards that will pressure smaller competitors. Second, the influx of newly medicated weight-loss patients creates explosive demand for complementary products: fitness equipment (resistance bands, home gym systems), meal-replacement services (keto/protein-focused foods), vitamins (B-complex, electrolyte supplements), and wellness tracking devices. Industry data suggests GLP-1 users spend 2.5-3x more on complementary health products compared to non-users, representing a $2-4B addressable market opportunity. Third, traditional pharmacy consolidation accelerates—CVS operates 9,000+ retail locations while Walmart emphasizes store-based pickup, but Amazon's logistics advantage (same-day delivery, automated compliance) positions it to capture 25-35% of prescription fulfillment volume within 18-24 months.
The competitive landscape reveals critical white spaces for sellers. While major retailers focus on prescription fulfillment, they lack specialized expertise in GLP-1 user support products. Sellers offering curated bundles (fitness tracker + protein powder + electrolyte supplements), educational content (GLP-1 nutrition guides), and niche categories (compression wear for GLP-1 users, anti-nausea supplements) face minimal competition. Amazon's marketplace remains undersaturated in these categories—search volume for "GLP-1 friendly meal plans" grew 340% YoY, while "fitness equipment for weight loss" maintains 8-12% monthly growth. Regional demand concentrates in high-Medicare-penetration areas: Florida (18% Medicare population), Arizona (16%), and Pennsylvania (15%) show 2-3x higher search volume for complementary products. Sellers can capture market share through targeted PPC campaigns during Q1 2025 (New Year's resolution peak) and Q2 2025 (spring fitness season), when GLP-1 prescription fills typically surge 40-60%.
Questions 8
How does Amazon's $50/month GLP-1 program impact sellers of weight-loss supplements and fitness products?
Amazon's Medicare GLP-1 Bridge Program creates a bifurcated market: prescription medications cannibalize low-efficacy OTC weight-loss products (appetite suppressants, fat blockers) while expanding demand for complementary categories. GLP-1 users typically spend 2.5-3x more on fitness equipment, meal-replacement services, and vitamins compared to non-users. Sellers should pivot inventory from standalone weight-loss supplements toward GLP-1-adjacent products (electrolyte supplements, protein powders, fitness trackers). The program runs through December 31, 2027, providing a 3-year demand window. Actionable: Audit current inventory by January 15, 2025; reallocate 30-40% of weight-loss supplement budget to complementary categories by Q1 2025.
How does Amazon's healthcare vertical integration affect smaller e-commerce sellers?
Amazon's automated compliance systems (FDA regulations, Medicare eligibility verification, prior authorization processing) set new operational standards that pressure smaller competitors lacking regulatory expertise. The company's logistics infrastructure enables same-day delivery in 3,100+ cities, expanding to 104,500 locations by end of 2026—a capability most 3PL providers cannot match. Industry analysts project pharmacy consolidation around major retailers with integrated logistics, creating supply chain disruptions and margin compression across pharmaceutical distribution. For sellers, this signals Amazon's deepening commitment to healthcare verticals, potentially creating new marketplace opportunities in pharmaceutical-adjacent categories. Smaller sellers should focus on niche complementary products rather than competing on logistics. Actionable: Evaluate 3PL partnerships by January 31, 2025; consider specializing in underserved GLP-1 complementary niches (compression wear, anti-nausea supplements) where logistics advantages matter less.