


US AI CapEx Boom Reaches 3% GDP | Seller Opportunity in Tech Infrastructure Demand
- Historic $300B+ annual AI investment surge creates demand for enterprise software, automation tools, and productivity solutions across all seller categories








Overview
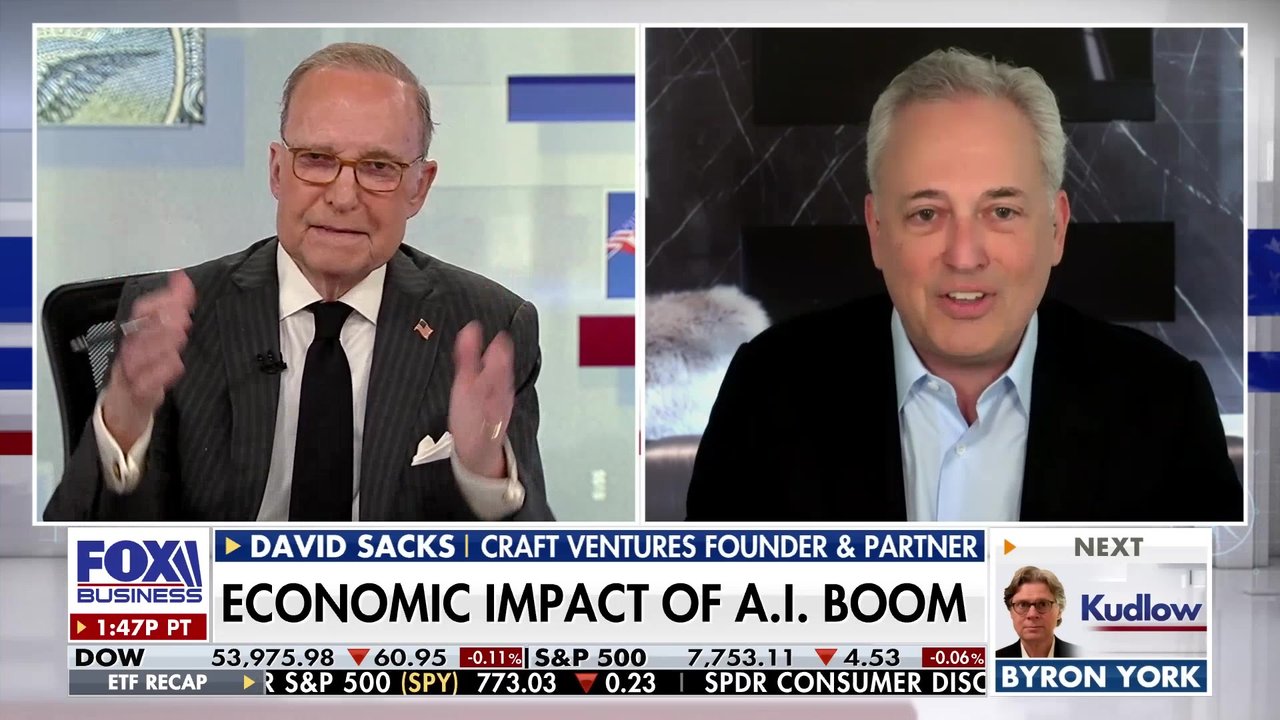
The US is entering a historic AI capital expenditure cycle that will reshape e-commerce seller opportunities through 2026 and beyond. David Sacks, a prominent tech policy advisor, projects AI CapEx spending will reach 3% of US GDP in the coming year—an unprecedented $300B+ annual investment in technology infrastructure. This forecast, delivered during an August 11, 2026 Fox Business interview, signals sustained economic growth driven by enterprise AI adoption, which directly impacts seller demand patterns, customer purchasing power, and competitive dynamics across all e-commerce categories.
The macroeconomic tailwind creates immediate seller opportunities through three mechanisms. First, increased corporate spending on AI infrastructure drives demand for B2B-adjacent products: enterprise software integrations, automation tools, data analytics platforms, and productivity software that sellers can source and resell on Amazon Business, Shopify B2B, and specialized marketplaces. Companies deploying AI systems need complementary hardware (GPUs, servers, networking equipment), software licenses, and implementation services—categories where third-party sellers capture 30-40% of marketplace volume. Second, pro-innovation tax policies and accelerated depreciation mechanisms incentivize companies to invest in technology faster, compressing purchase cycles from 12-18 months to 6-9 months. This acceleration benefits sellers offering rapid-deployment solutions and just-in-time inventory models. Third, productivity gains from AI adoption will increase consumer disposable income and business profitability, lifting overall e-commerce demand across discretionary categories (electronics, home office equipment, professional tools) by an estimated 5-8% through 2026.
Sacks' comparison to the railroad expansion era underscores the scale of this opportunity. The railroad boom created demand for steel, labor, and logistics infrastructure—analogous to today's AI infrastructure buildout requiring semiconductors, cloud services, and data center equipment. Sellers positioned in tech-adjacent categories (computer components, networking hardware, software licenses, office automation) should expect 15-25% category growth over the next 12-18 months. Additionally, the emphasis on tax policy incentives demonstrates that regulatory frameworks will remain favorable for technology investment, reducing compliance risk for sellers in this space. The forecast suggests sustained economic momentum contingent on maintaining pro-innovation policies, meaning sellers should prioritize sourcing and inventory allocation toward AI-adjacent products now, before competitive saturation increases.
For e-commerce sellers, this economic expansion translates to three actionable opportunities. First, sellers should immediately audit their product catalogs for AI-adjacent categories: enterprise software, automation tools, data analytics platforms, productivity hardware, and cloud infrastructure components. Second, sellers should increase inventory allocation to technology categories by 15-20% over the next 6 months, capitalizing on the compressed purchase cycles driven by accelerated depreciation policies. Third, sellers should develop marketing strategies targeting business buyers and IT decision-makers, who will be the primary drivers of this spending surge. The 3% GDP projection represents $300B+ in annual AI CapEx—a market opportunity larger than the entire US e-commerce furniture category. Sellers who position themselves early in this cycle can capture disproportionate market share before larger competitors saturate the space.
Questions 8
How does the projected 3% AI CapEx spending affect e-commerce seller demand?
The 3% GDP projection represents approximately $300B+ in annual AI infrastructure investment, creating direct demand for enterprise software, automation tools, and productivity hardware that sellers can source and resell. Companies deploying AI systems need complementary products—GPUs, servers, software licenses, and implementation services—where third-party sellers capture 30-40% of marketplace volume. This spending surge will compress purchase cycles from 12-18 months to 6-9 months, benefiting sellers offering rapid-deployment solutions. Sellers in tech-adjacent categories should expect 15-25% category growth over the next 12-18 months as corporate buyers accelerate technology investments.
Which product categories benefit most from the AI CapEx boom?
Enterprise software, automation tools, data analytics platforms, productivity hardware, cloud infrastructure components, GPU and server equipment, networking hardware, and office automation products are primary beneficiaries. Additionally, discretionary categories (electronics, home office equipment, professional tools) will see 5-8% demand lift from productivity gains and increased consumer disposable income. Sellers should prioritize sourcing in these categories immediately, before competitive saturation increases. Amazon Business and Shopify B2B platforms are ideal channels for reaching the IT decision-makers and business buyers driving this spending surge.