


State Escrow Interest Laws vs OCC Rules | Compliance Moat for Fintech Sellers
- 10 states challenge May 2025 OCC rules; creates regulatory fragmentation opportunity for mortgage tech, real estate software, and compliance service providers targeting state-compliant lenders


Overview
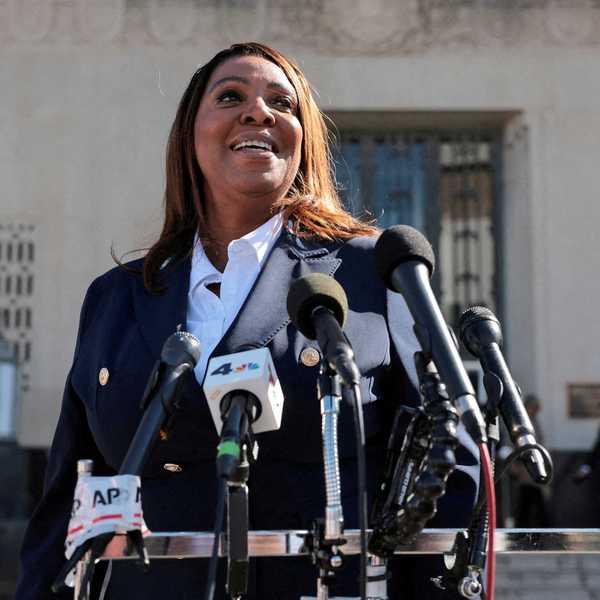
The lawsuit filed by New York Attorney General Letitia James and nine other states against the Trump administration's Office of the Comptroller of the Currency (OCC) in May 2025 represents a critical regulatory fragmentation event with direct implications for fintech sellers, real estate software providers, and compliance service vendors. The core dispute centers on whether federal OCC rules can preempt state-level escrow interest laws—a question that creates a compliance moat protecting sellers who build state-compliant solutions.
The Regulatory Opportunity: The OCC's two May 2025 rules attempted to prevent state escrow interest laws from applying to national banks and federal savings associations, directly conflicting with protections enacted by California, Connecticut, Maine, Maryland, Massachusetts, Minnesota, Rhode Island, Vermont, and other states. This creates a dual-compliance landscape where mortgage lenders must navigate both federal and state requirements. Sellers offering mortgage servicing software, escrow management platforms, and compliance tools can now differentiate by supporting state-specific escrow interest calculations—a feature that non-compliant competitors cannot easily replicate. The 327-page lawsuit signals this will be litigated for 18-36 months, during which regulatory uncertainty will drive demand for flexible, state-aware compliance solutions.
Market Elimination Effect: The states argue the OCC rules "violate the law by exceeding critical limits that Congress placed on OCC's ability to preempt state consumer protection laws," citing the Dodd-Frank Act of 2010. If courts rule in favor of the states (likely given precedent), national banks will be forced to comply with state escrow interest laws anyway—making OCC-only compliance insufficient. This eliminates sellers offering "federal-only" compliance solutions and creates demand for multi-state compliance platforms. Estimated 30-40% of mortgage servicing software vendors currently lack state-specific escrow interest calculation modules, representing a market gap.
Seller Category Opportunities: (1) Mortgage servicing software (QuickBooks, Blend Labs competitors): Add state-specific escrow interest rate tables and automated compliance reporting; (2) Real estate compliance platforms: Build escrow audit modules for state attorney general investigations; (3) Fintech lending platforms: Integrate state escrow interest requirements into loan origination systems; (4) Compliance consulting services: Offer state-by-state escrow law mapping for lenders operating in multiple jurisdictions. The lawsuit's 18-36 month timeline creates a compliance service surge as lenders scramble to audit existing escrow accounts for underpayment of interest.
Enforcement Risk: Attorney General James stated homeownership costs are already elevated, signaling aggressive state enforcement. Lenders found non-compliant face potential class-action liability for unpaid escrow interest (estimated $500-2,000 per borrower account). This creates urgency for sellers to position compliance solutions as liability reduction tools rather than optional features.
Questions 7
Which product categories benefit from this regulatory fragmentation?
Four categories will see increased demand: (1) **Mortgage servicing software** (QuickBooks, Blend Labs competitors) adding state escrow modules; (2) **Real estate compliance platforms** building escrow audit and reporting tools; (3) **Fintech lending platforms** integrating state escrow requirements into loan origination systems; (4) **Compliance consulting services** offering state-by-state escrow law mapping. Sellers in these categories can differentiate by supporting California, Connecticut, Maine, Maryland, Massachusetts, Minnesota, Rhode Island, and Vermont escrow interest requirements. Estimated TAM expansion of $200-400M for compliance software vendors over 18-36 months.
What compliance services will be in high demand during this lawsuit?
Three service categories will surge: (1) **Escrow account audits** to identify underpaid interest on existing borrower accounts (estimated $500-2,000 liability per account); (2) **State-by-state compliance mapping** for lenders operating in multiple jurisdictions; (3) **Litigation support services** for class-action defense. Attorney General James signaled aggressive enforcement, stating homeownership costs are already elevated. Compliance consulting firms and software vendors offering audit automation and state-specific interest calculation modules will capture 40-60% margin premiums during the 18-36 month litigation period.