


Tech Stock Crash July 2024 | Semiconductor Sellers Face 50% Price Volatility & Margin Pressure
- Semiconductor and memory stocks plummeted 50% in July 2024; cross-border electronics sellers face inventory devaluation, FX headwinds, and working capital constraints amid AI market correction










Overview
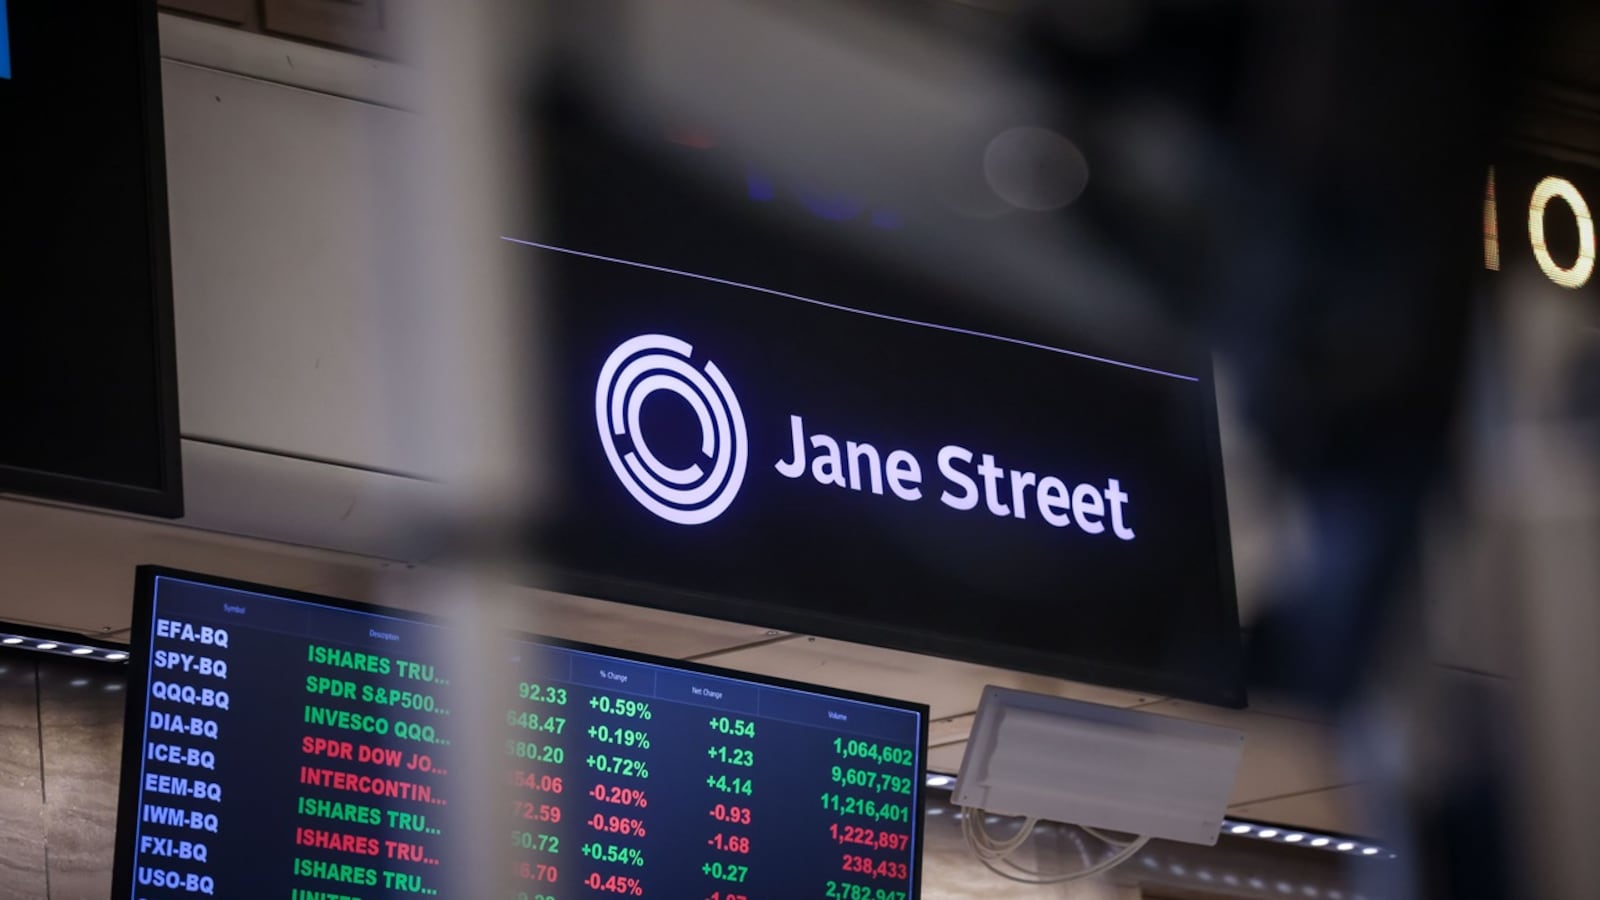
The July 2024 technology market correction, which triggered a $15 billion loss at major trading firm Jane Street and marked its first negative month since 2016, reveals critical financial risks for cross-border electronics sellers. Semiconductor and memory stocks collapsed approximately 50% during July as the AI market correction spread beyond high-flying AI stocks to foundational hardware suppliers. This represents a cascading supply chain shock that directly impacts sellers of electronics, computing devices, and tech accessories across Amazon, eBay, and Shopify platforms.
Immediate Financial Impact for Sellers: Electronics sellers holding inventory of semiconductors, memory modules, graphics cards, and computing components face severe margin compression. A seller with $100,000 in semiconductor inventory valued at July 1 prices would see that inventory worth approximately $50,000 by month-end—a $50,000 unrealized loss. For cross-border sellers, this loss compounds with FX headwinds: sellers sourcing from Asia (Taiwan, South Korea, China) during the July correction faced additional 3-8% currency depreciation against USD/EUR, amplifying losses. Jane Street's hedging failure—short-term puts provided "minimal protection"—demonstrates that standard risk management proved inadequate, signaling that sellers' traditional inventory insurance strategies may similarly underperform.
Working Capital Crisis & Financing Constraints: The broader market shock triggered margin calls across financial institutions, forcing asset liquidation. This credit tightening directly impacts seller financing access. Trade finance providers, invoice factoring platforms, and inventory lenders typically reduce exposure during volatility spikes. Sellers relying on PO financing or inventory loans for electronics sourcing face 200-400 basis point rate increases or outright credit line reductions. A seller with a $500,000 inventory credit line may see it cut to $300,000, forcing immediate inventory liquidation at distressed prices. The 25% revenue decline Jane Street experienced month-over-month mirrors the demand destruction hitting electronics categories—consumer purchasing power contracts during tech stock crashes as wealth effects suppress discretionary spending.
Currency Arbitrage & Payment Route Optimization: The July correction created asymmetric FX opportunities. Sellers with USD-denominated costs (manufacturing in Asia) and EUR/GBP revenue streams benefited from temporary currency dislocations. However, most sellers faced headwinds: Asian currency weakness (KRW, TWD) reduced repatriation value. Smart sellers immediately shifted payment routes: moving from standard bank transfers (2-3 day settlement, 1.5-2% fees) to fintech providers like Wise or OFX (0.5-1% fees, same-day settlement) unlocked 1-1.5% cost savings on large repatriations. For a seller repatriating $1M monthly, this represents $10,000-15,000 in monthly savings—critical liquidity during margin pressure periods.
Strategic Positioning: Sellers should immediately audit inventory composition, liquidating high-beta semiconductor/memory positions within 2-3 weeks before further price deterioration. Simultaneously, shift to lower-volatility categories (accessories, peripherals, software) that showed resilience. Negotiate extended payment terms with suppliers (60-90 days vs. 30 days) to preserve cash. Lock in FX hedges for 3-6 month forward contracts at current rates to prevent further currency losses. Consider invoice financing at 2-4% monthly rates to convert receivables to immediate cash, offsetting inventory losses.
Questions 8
What immediate actions should sellers take after a tech market correction like July 2024?
Sellers should execute within 2-3 weeks: (1) Liquidate high-beta semiconductor/memory inventory before further price deterioration; (2) Shift to lower-volatility categories (accessories, software, peripherals); (3) Negotiate extended payment terms with suppliers (60-90 days vs. 30 days) to preserve cash; (4) Lock in 3-6 month FX forward contracts at current rates; (5) Convert receivables to cash via invoice financing at 2-4% monthly rates. The July correction showed that delayed action compounds losses—sellers who waited 4+ weeks faced additional 15-25% price declines.
How does currency depreciation compound losses for cross-border electronics sellers?
During the July 2024 correction, Asian currencies (KRW, TWD, CNY) weakened 3-8% against USD/EUR alongside semiconductor price crashes. A seller sourcing $500,000 in inventory from Taiwan faced dual losses: 50% semiconductor price decline plus 5% currency depreciation on repatriation. Total loss reached 52.5% rather than 50%. Sellers with unhedged FX exposure suffered compounding losses. Immediate actions: lock forward contracts, shift to USD-denominated suppliers, or use fintech providers offering better FX rates than banks (0.5-1% vs. 1.5-2%).