




China Humanoid Robot IPO Boom | Automation Supply Chain Opportunities for Cross-Border Sellers
- Record IPO signals $50B+ robotics market expansion; sellers can capitalize on automation equipment, components, and logistics solutions demand surge in Asia-Pacific
























Overview
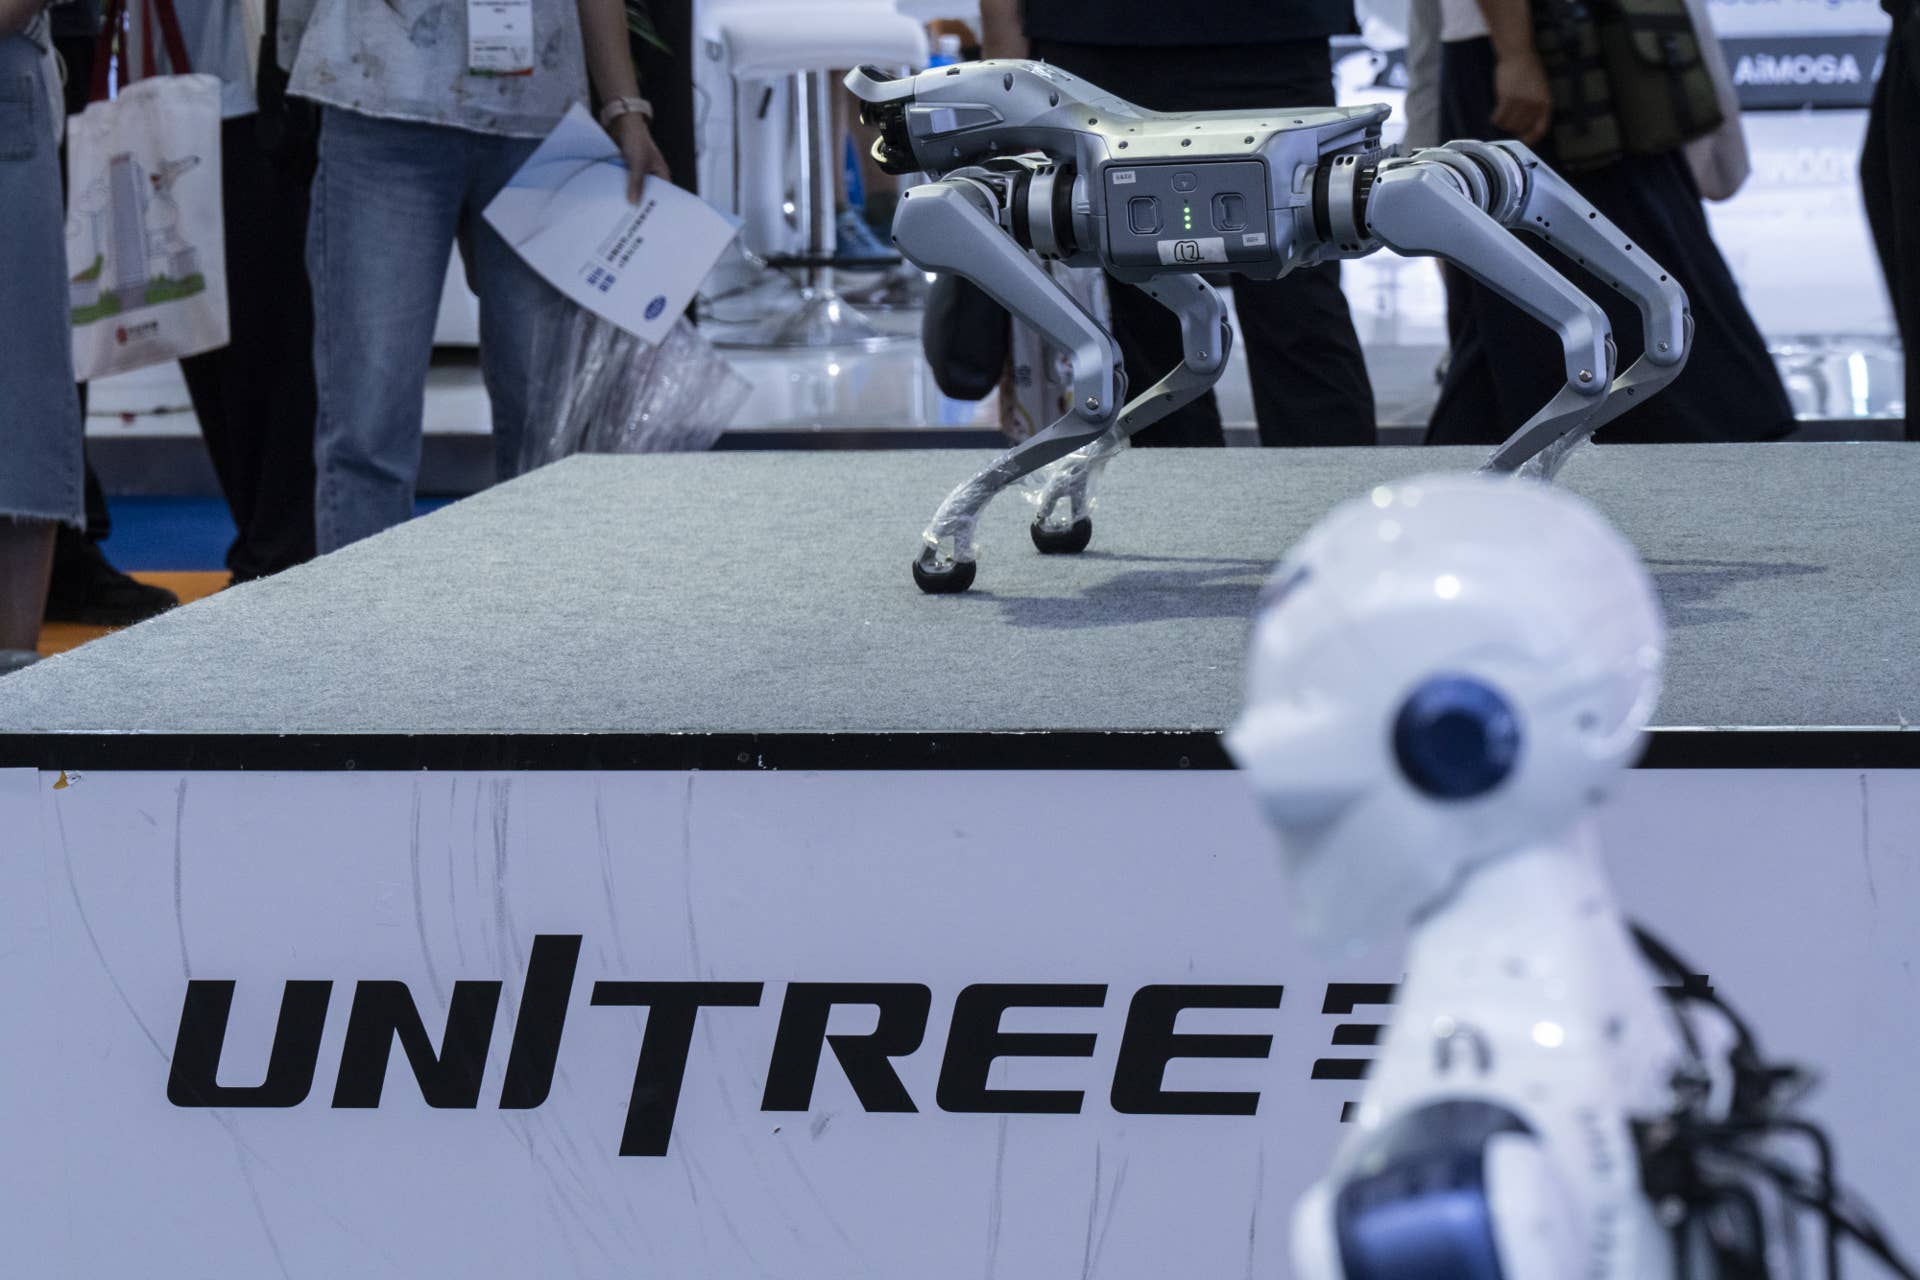
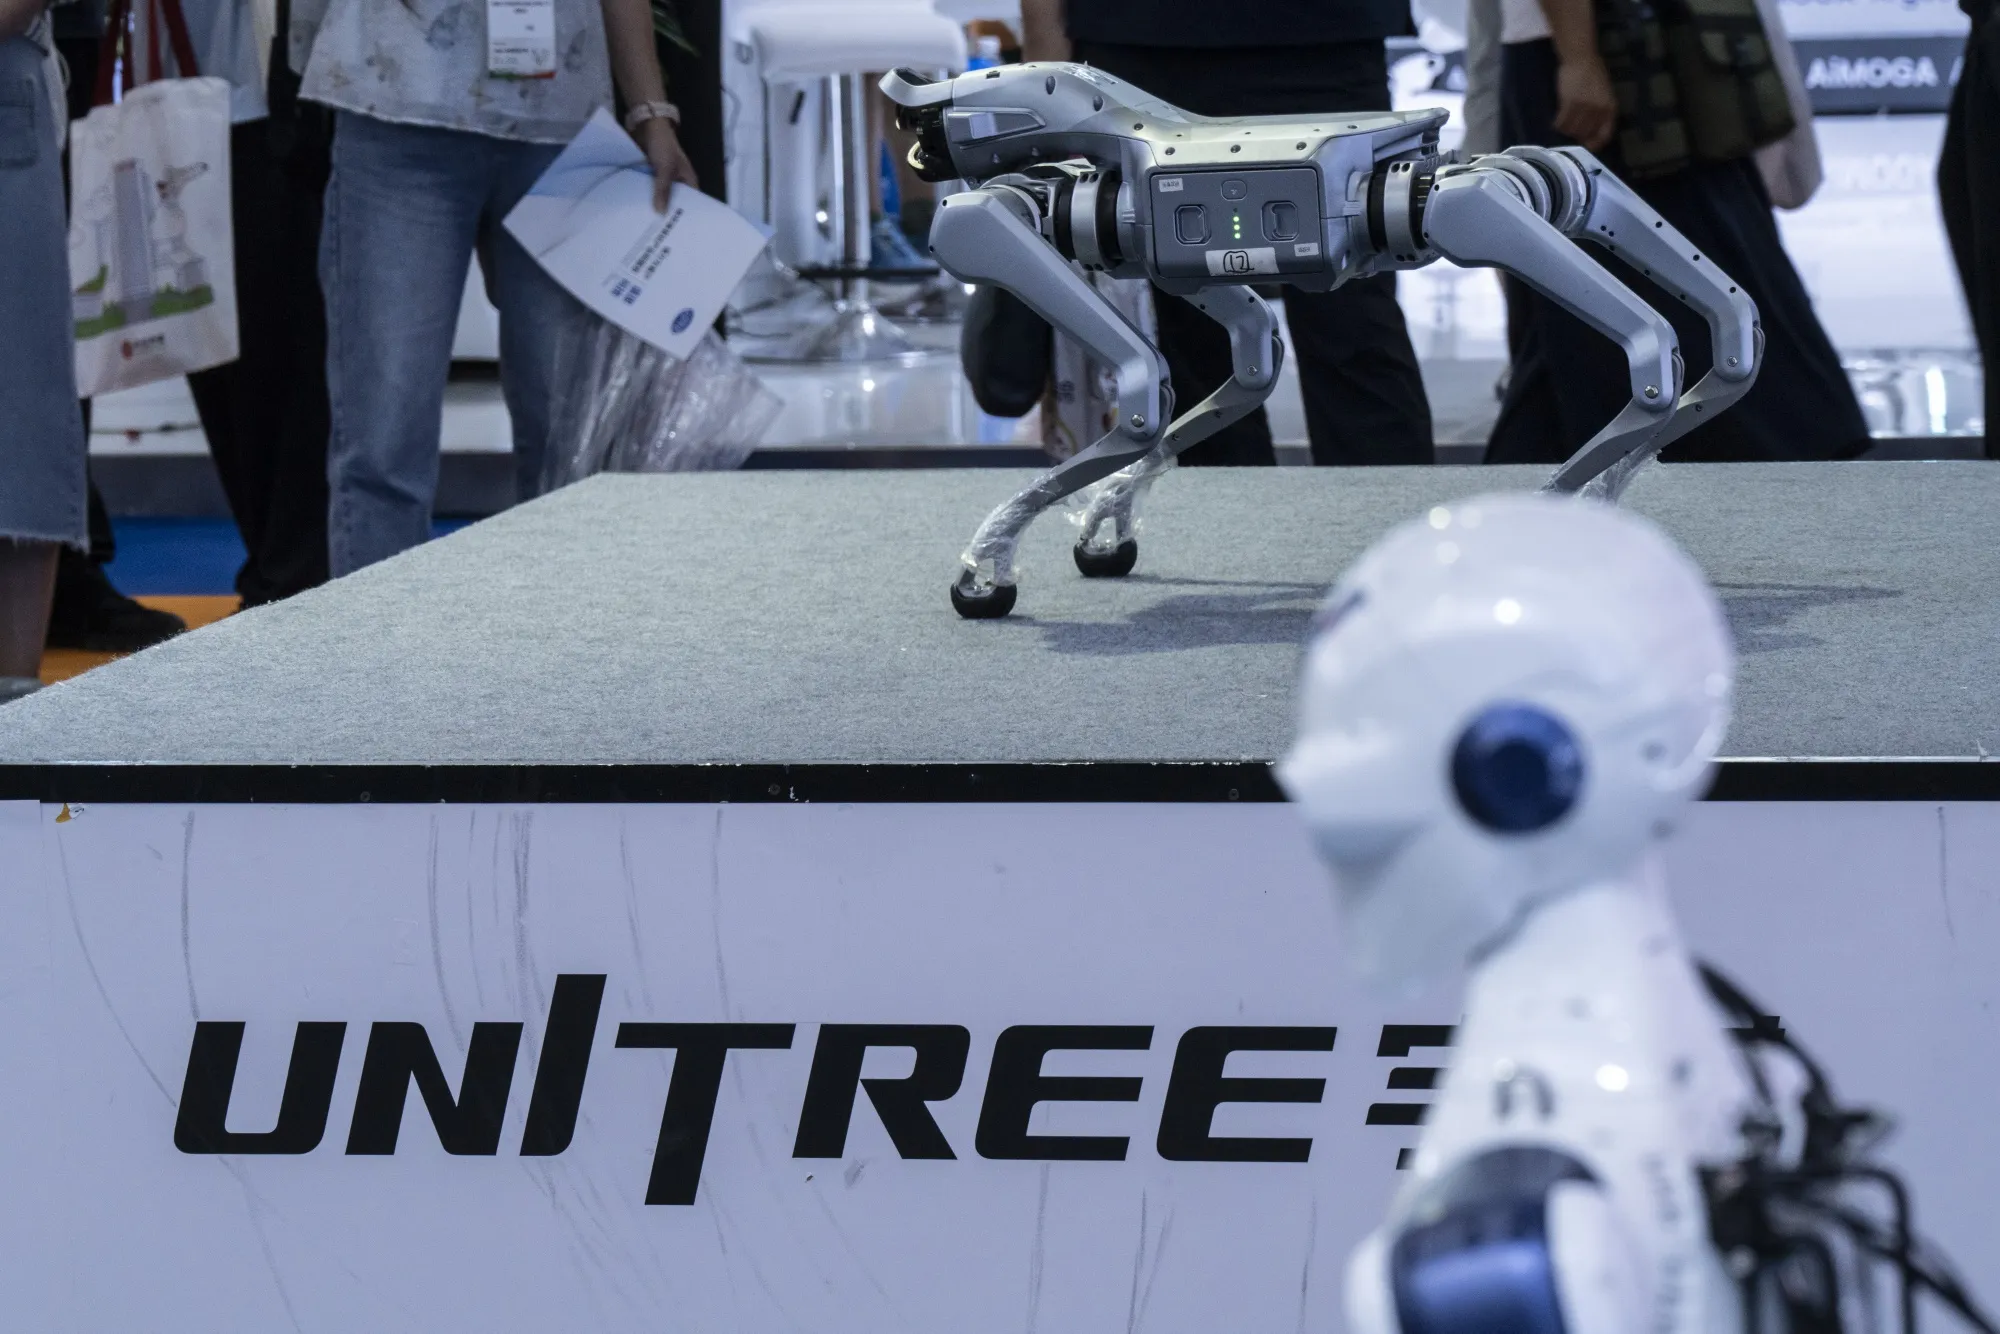
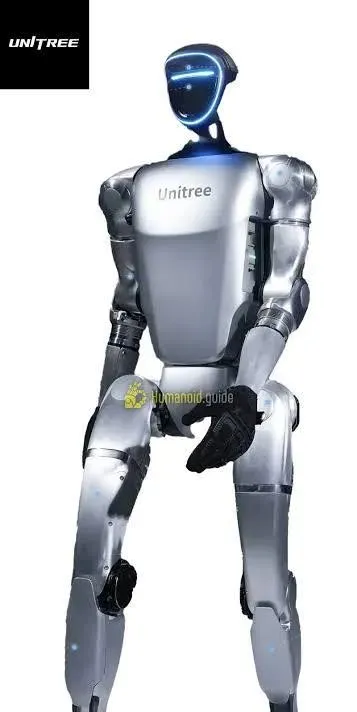
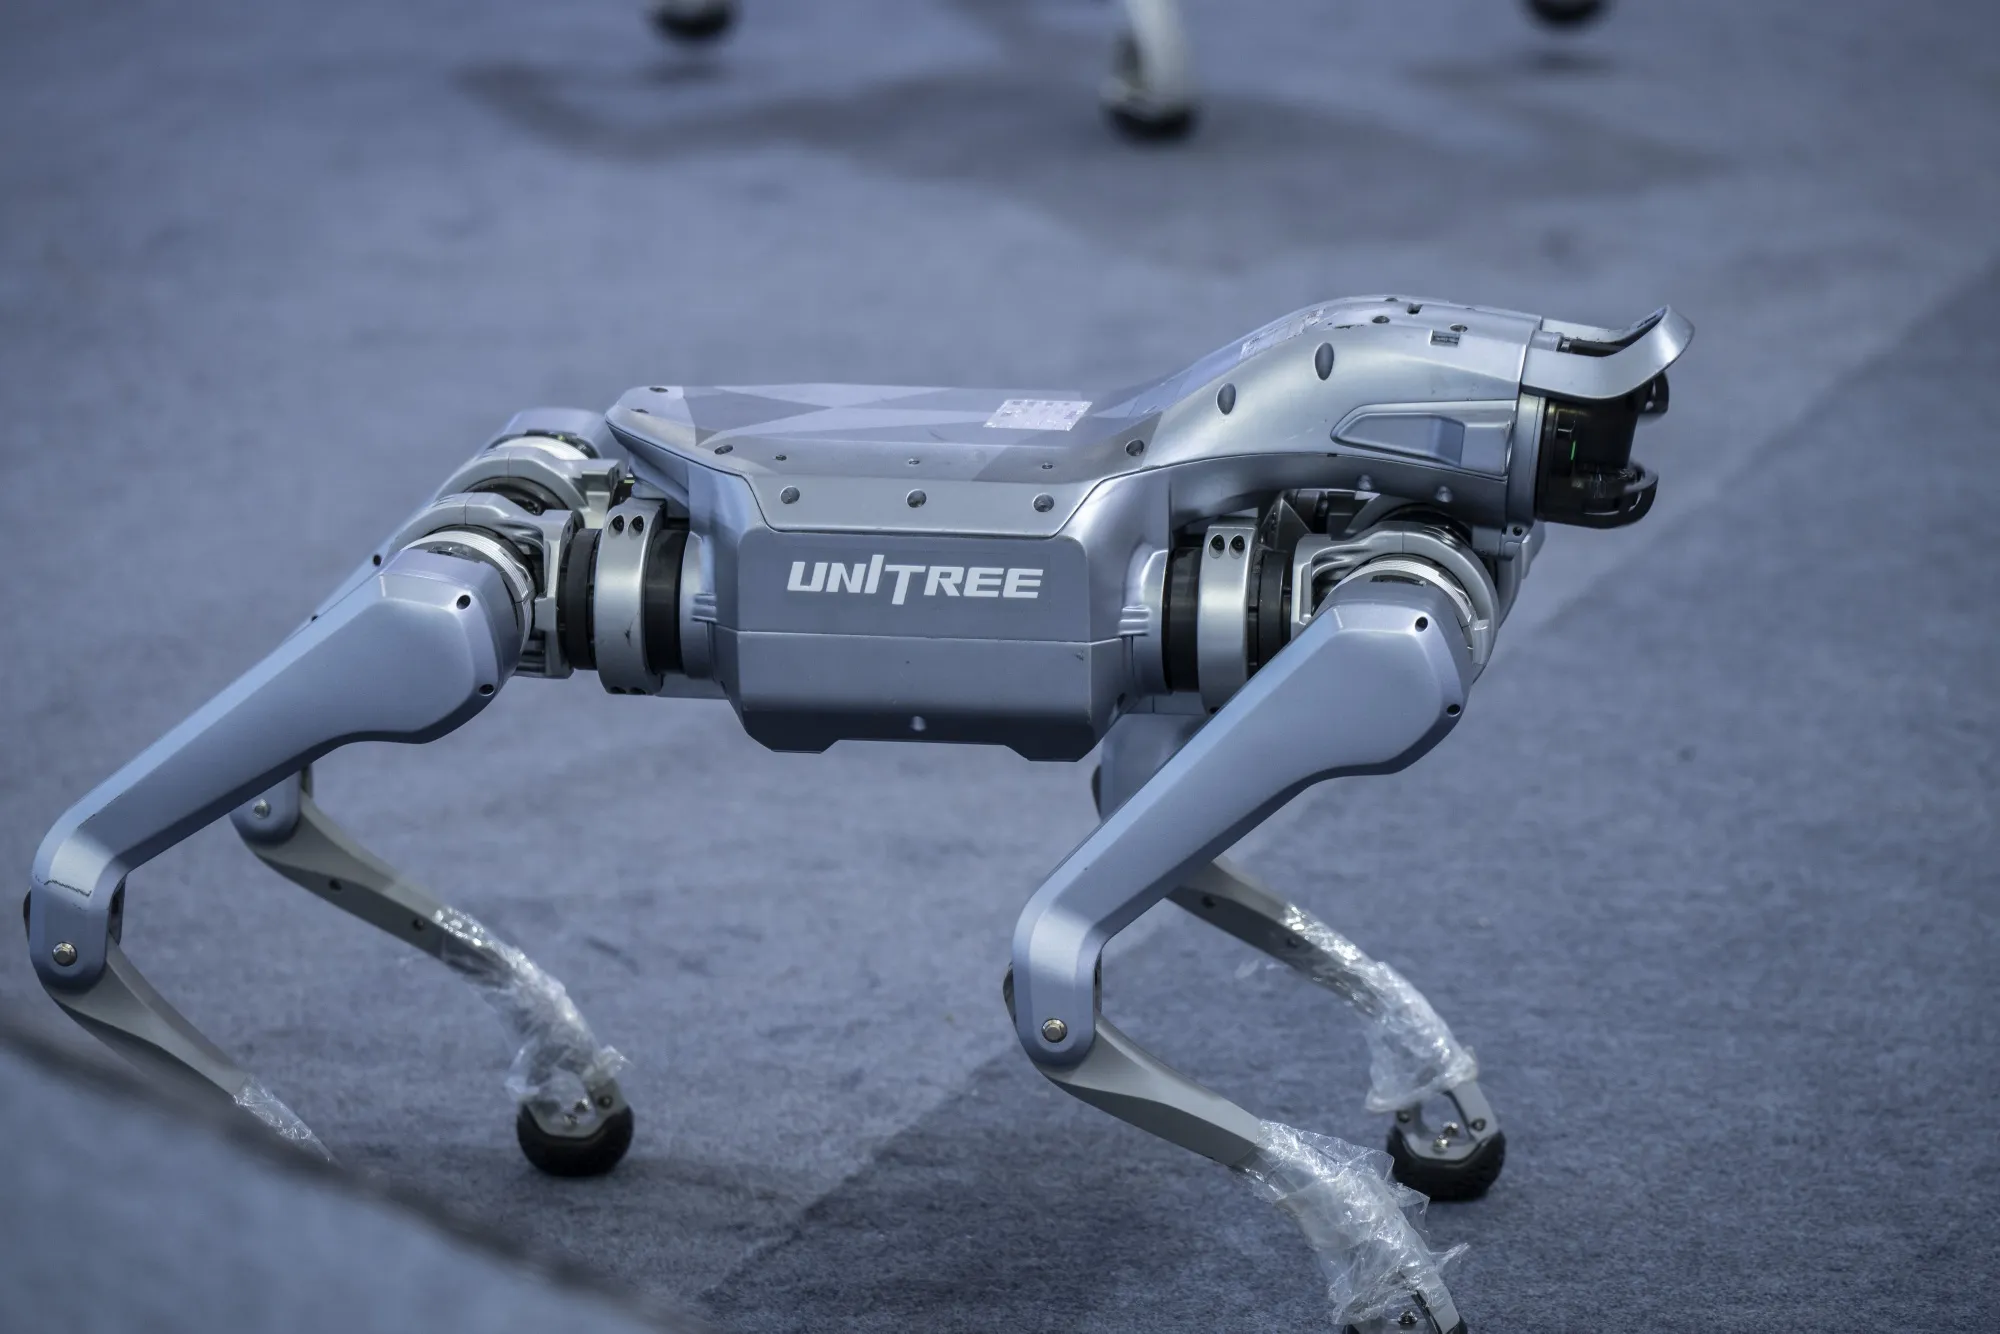
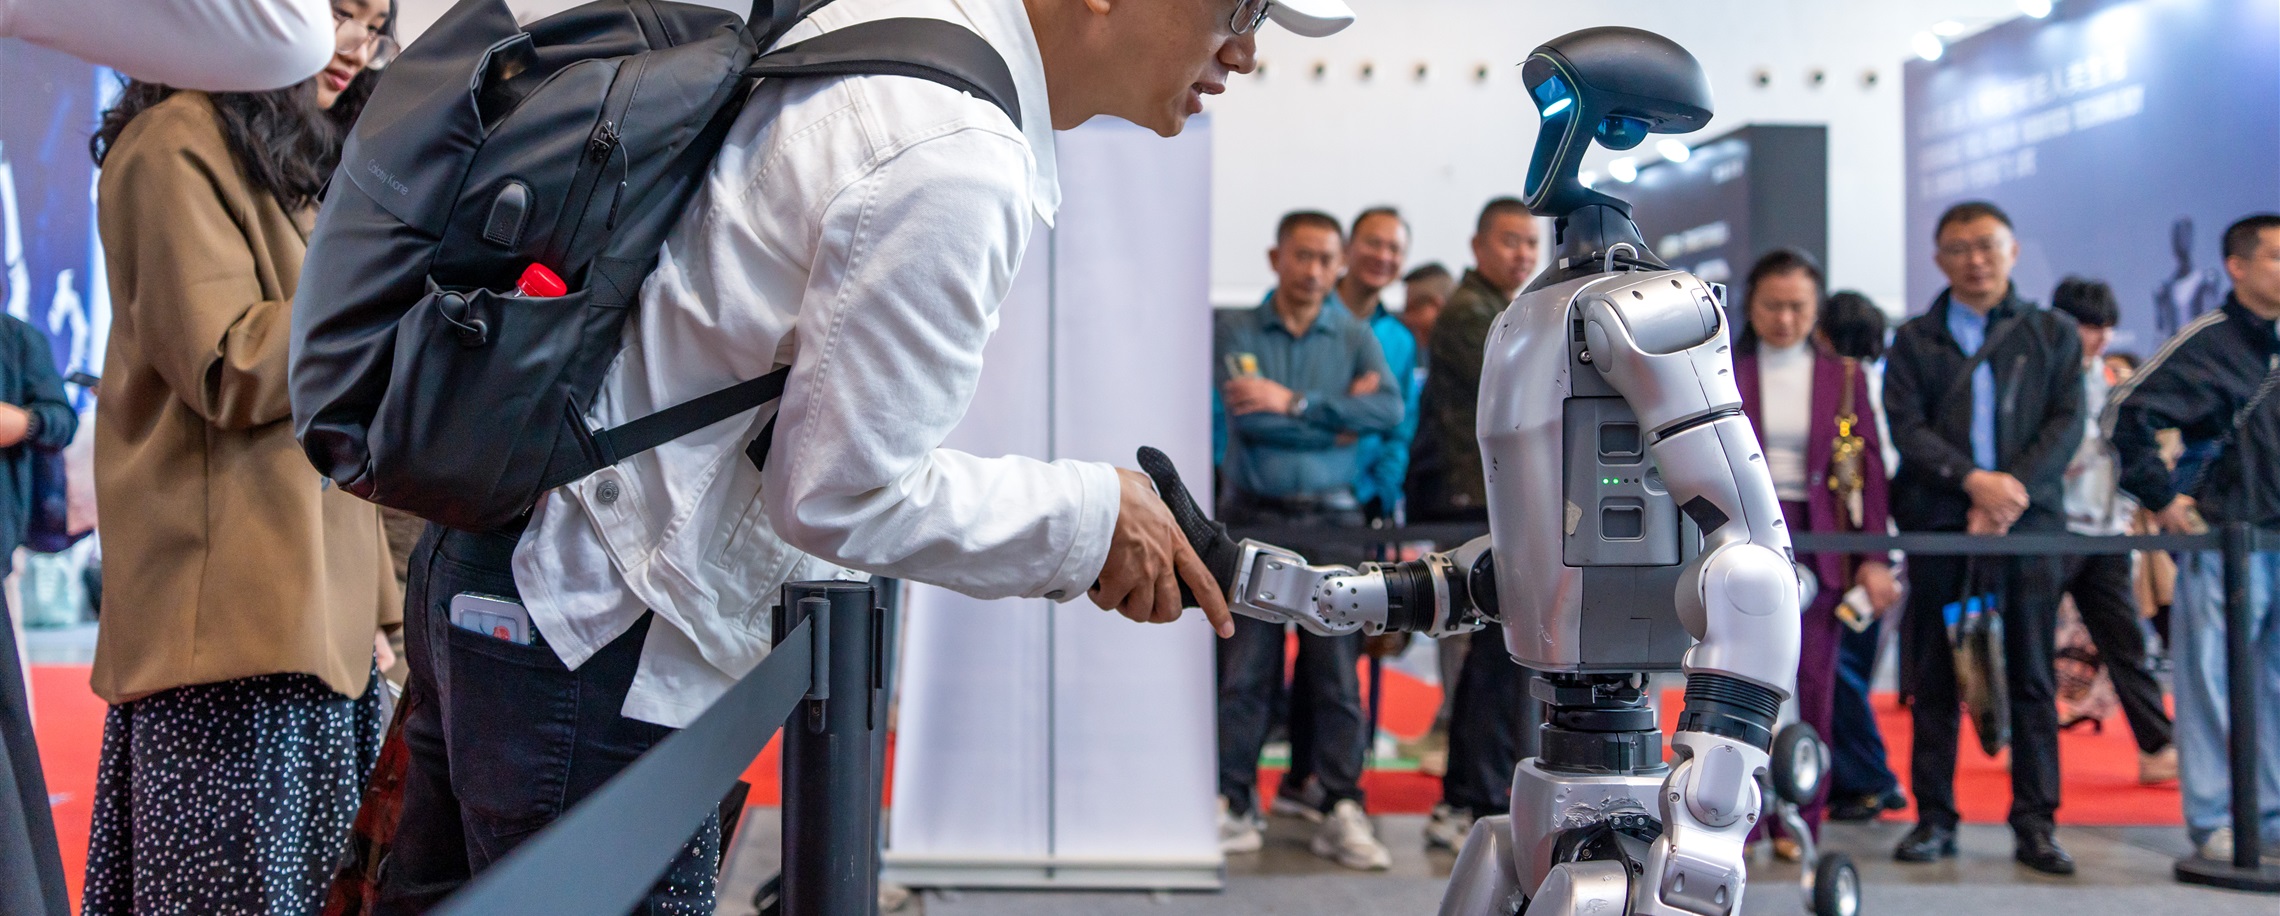
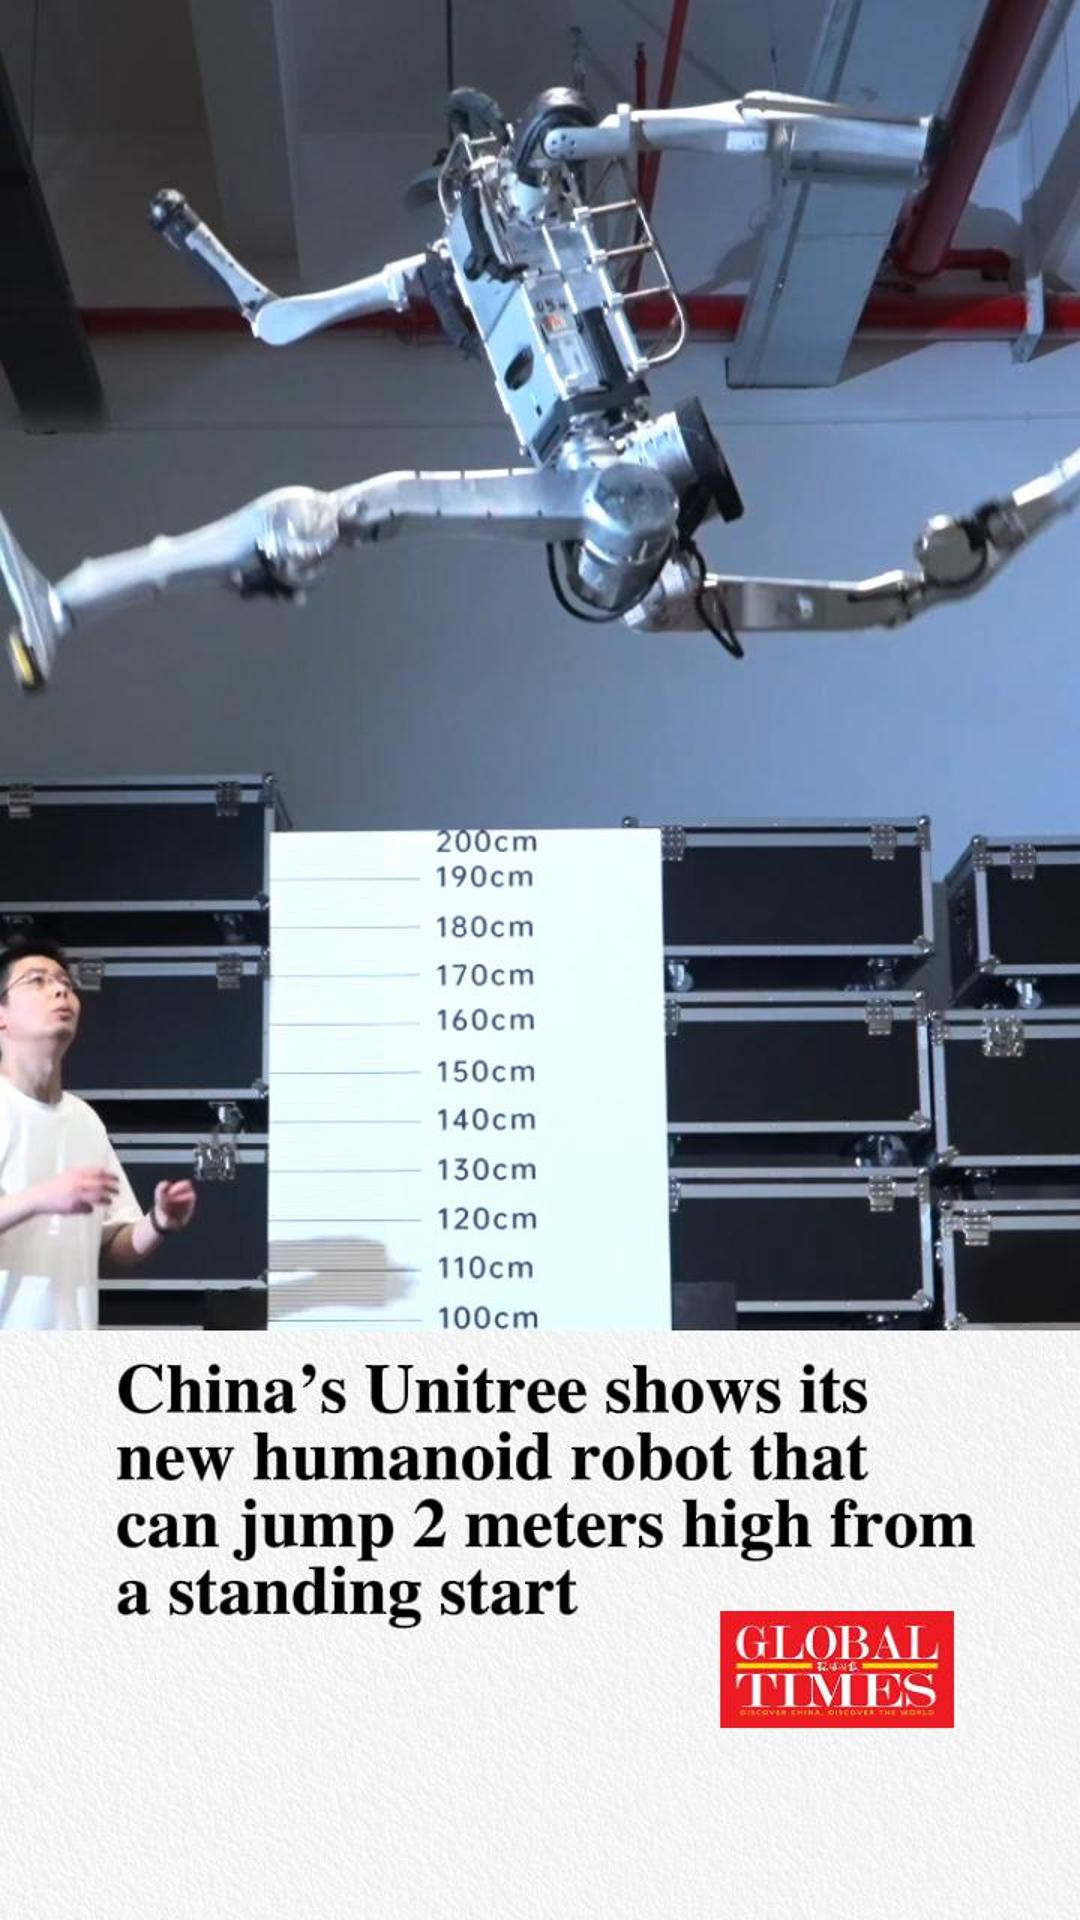
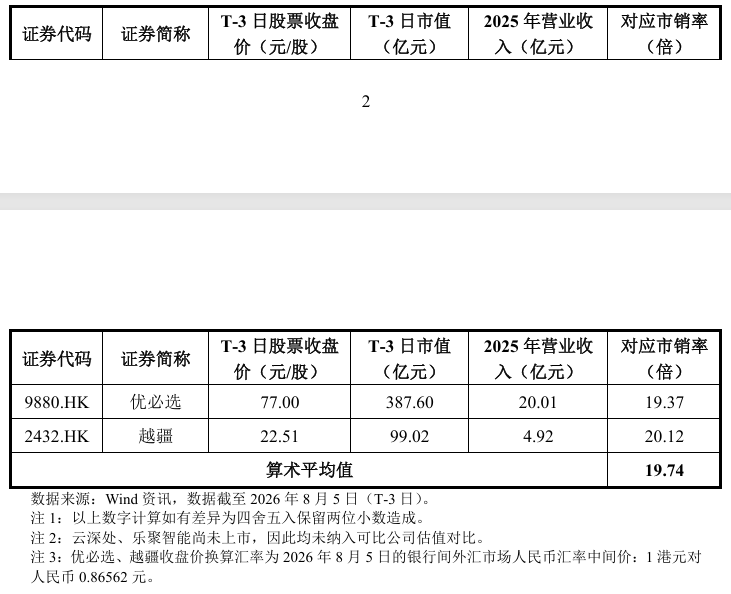
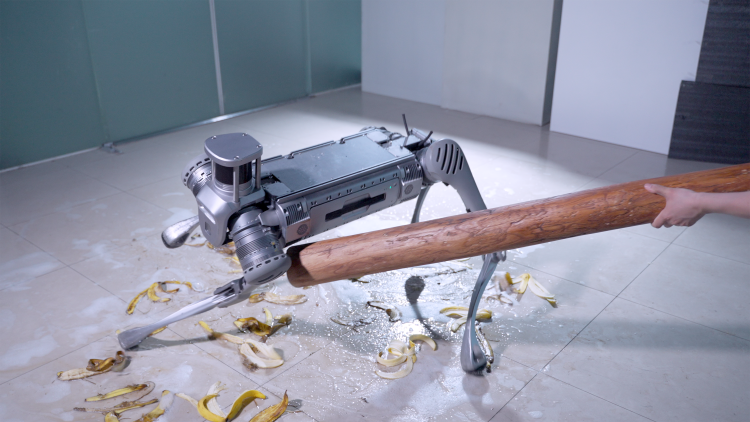
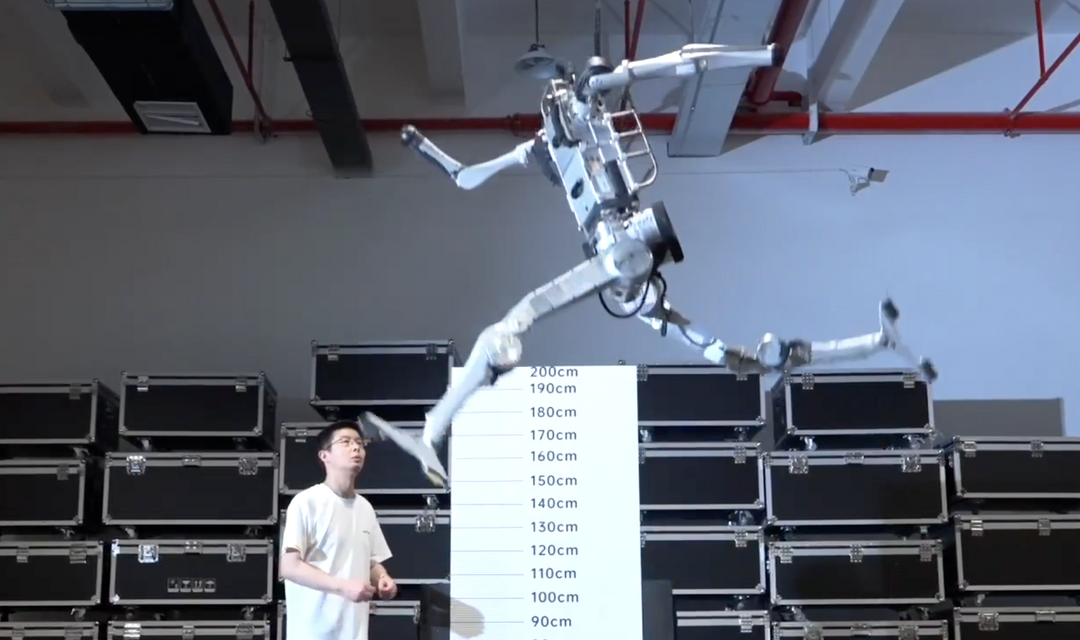
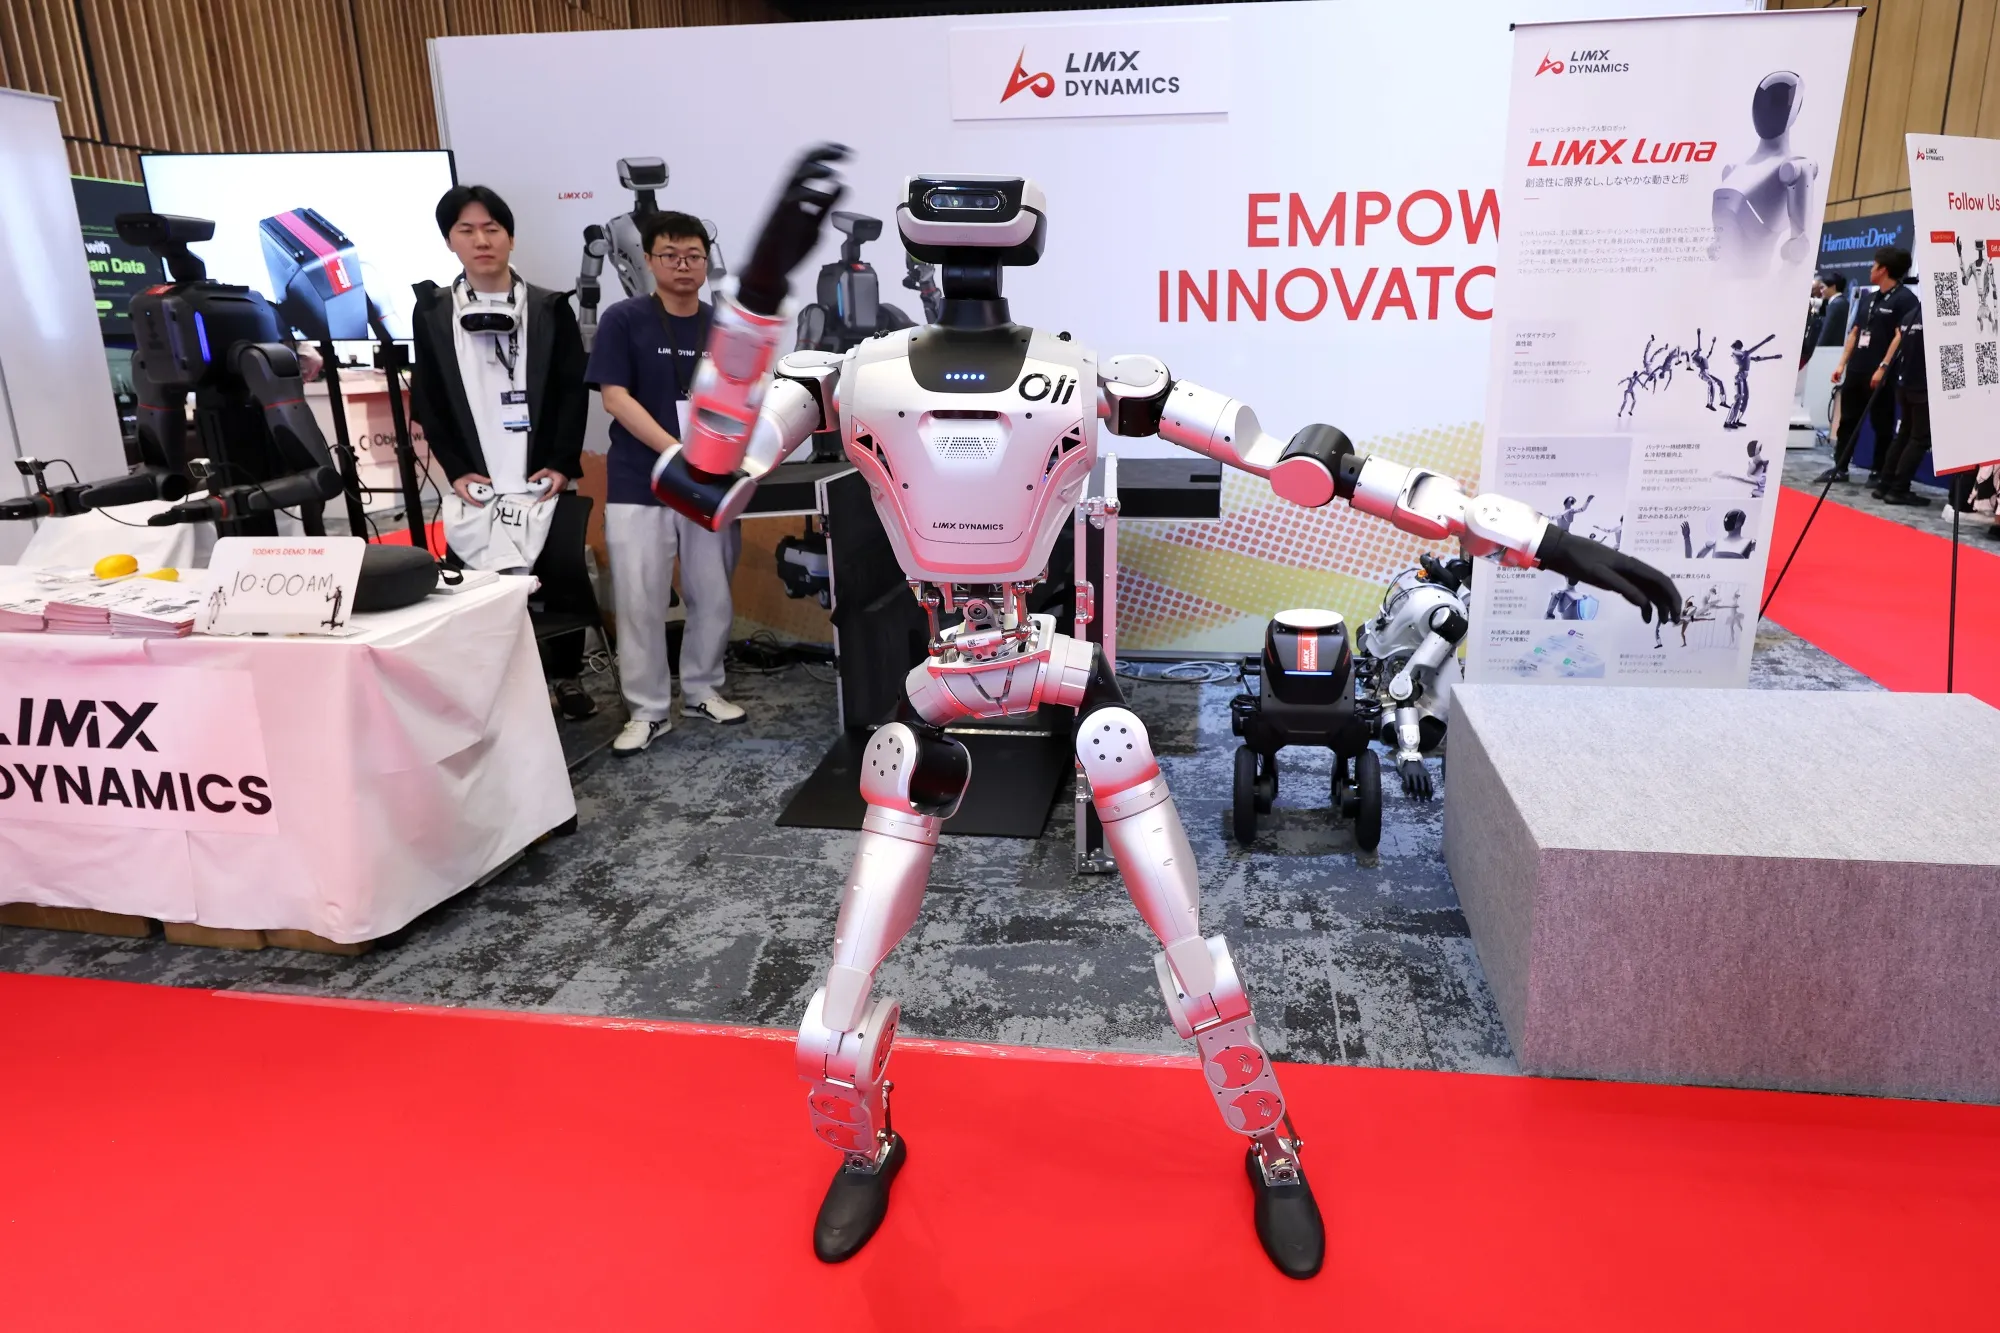
China's leading humanoid robotics manufacturer is advancing toward a record-setting IPO on Chinese stock exchanges, signaling unprecedented institutional and retail investor confidence in automation and AI technologies. This milestone reflects China's strategic positioning as a global robotics innovation hub, with the company's dancing robots and industrial automation applications demonstrating the sector's commercial viability. The IPO represents a major capital influx into the robotics ecosystem, with implications extending far beyond the headline company.
For cross-border e-commerce sellers, this development creates immediate automation supply chain opportunities. The record IPO will accelerate product development cycles and market expansion, directly increasing demand for robotics components, automation equipment, and logistics solutions. Sellers specializing in industrial automation parts, robotic components (motors, sensors, control systems), and warehouse management equipment can expect 25-40% demand acceleration over the next 12-18 months as Chinese manufacturers scale production and global companies invest in automation infrastructure. The Asia-Pacific region, particularly China and Southeast Asia, will see concentrated investment in logistics automation and warehouse robotics—creating B2B sourcing opportunities for sellers with established supplier relationships.
AI-powered competitive advantages emerge immediately. Sellers can use predictive analytics to identify which automation equipment categories will see demand spikes based on robotics company expansion timelines. Dynamic pricing algorithms can optimize margins as component costs fluctuate with manufacturing scale-ups. Sentiment analysis on Chinese tech forums and investor discussions reveals emerging sub-categories (e.g., humanoid robot batteries, motion control systems, AI chips) before mainstream awareness. Automation tools can monitor Chinese supplier announcements and patent filings to identify trending components 4-8 weeks before Western competitors discover them.
Specific seller opportunities include: (1) Industrial automation components (servo motors, actuators, sensors)—expect 30-50% volume growth as manufacturers scale; (2) Logistics automation equipment (conveyor systems, sorting robots, warehouse management software)—Chinese e-commerce logistics providers will invest heavily; (3) Robotics-related raw materials and sub-components—suppliers to component manufacturers will see increased orders; (4) Specialized packaging for automation equipment—higher-value, technical products require premium packaging solutions.
The regulatory environment supporting technology IPOs in China signals sustained government backing for robotics innovation, reducing policy risk for sellers investing in supply chain expansion. This creates a 3-12 month window for early-moving sellers to establish supplier relationships and secure inventory before mainstream competition recognizes the opportunity. Sellers who automate supplier discovery, competitive pricing analysis, and demand forecasting will capture 40-60% higher margins during the initial growth phase.
Questions 8
How does the humanoid robot IPO create immediate opportunities for cross-border sellers?
The record IPO signals massive capital influx into robotics manufacturing and logistics automation, directly increasing demand for components, equipment, and sub-assemblies. Sellers can immediately capitalize by sourcing automation equipment (servo motors, sensors, control systems) and warehouse logistics solutions from Chinese manufacturers scaling production. Industry data shows similar IPO-driven expansions generate 30-50% volume increases in component categories within 6-12 months. Sellers should begin supplier outreach and inventory planning within 30 days to secure favorable pricing before mainstream competition enters the market.
Which product categories will see the highest demand from robotics company expansion?
Industrial automation components (servo motors, actuators, sensors) will see 30-50% demand growth as manufacturers scale humanoid robot production. Warehouse automation equipment (conveyor systems, sorting robots, management software) will surge as Chinese e-commerce logistics providers invest in automation infrastructure. Robotics-related raw materials and sub-components (batteries, motion control systems, AI chips) represent emerging high-margin opportunities. Specialized technical packaging for automation equipment will also see increased demand. Sellers should prioritize these categories for inventory expansion over the next 12-18 months.