
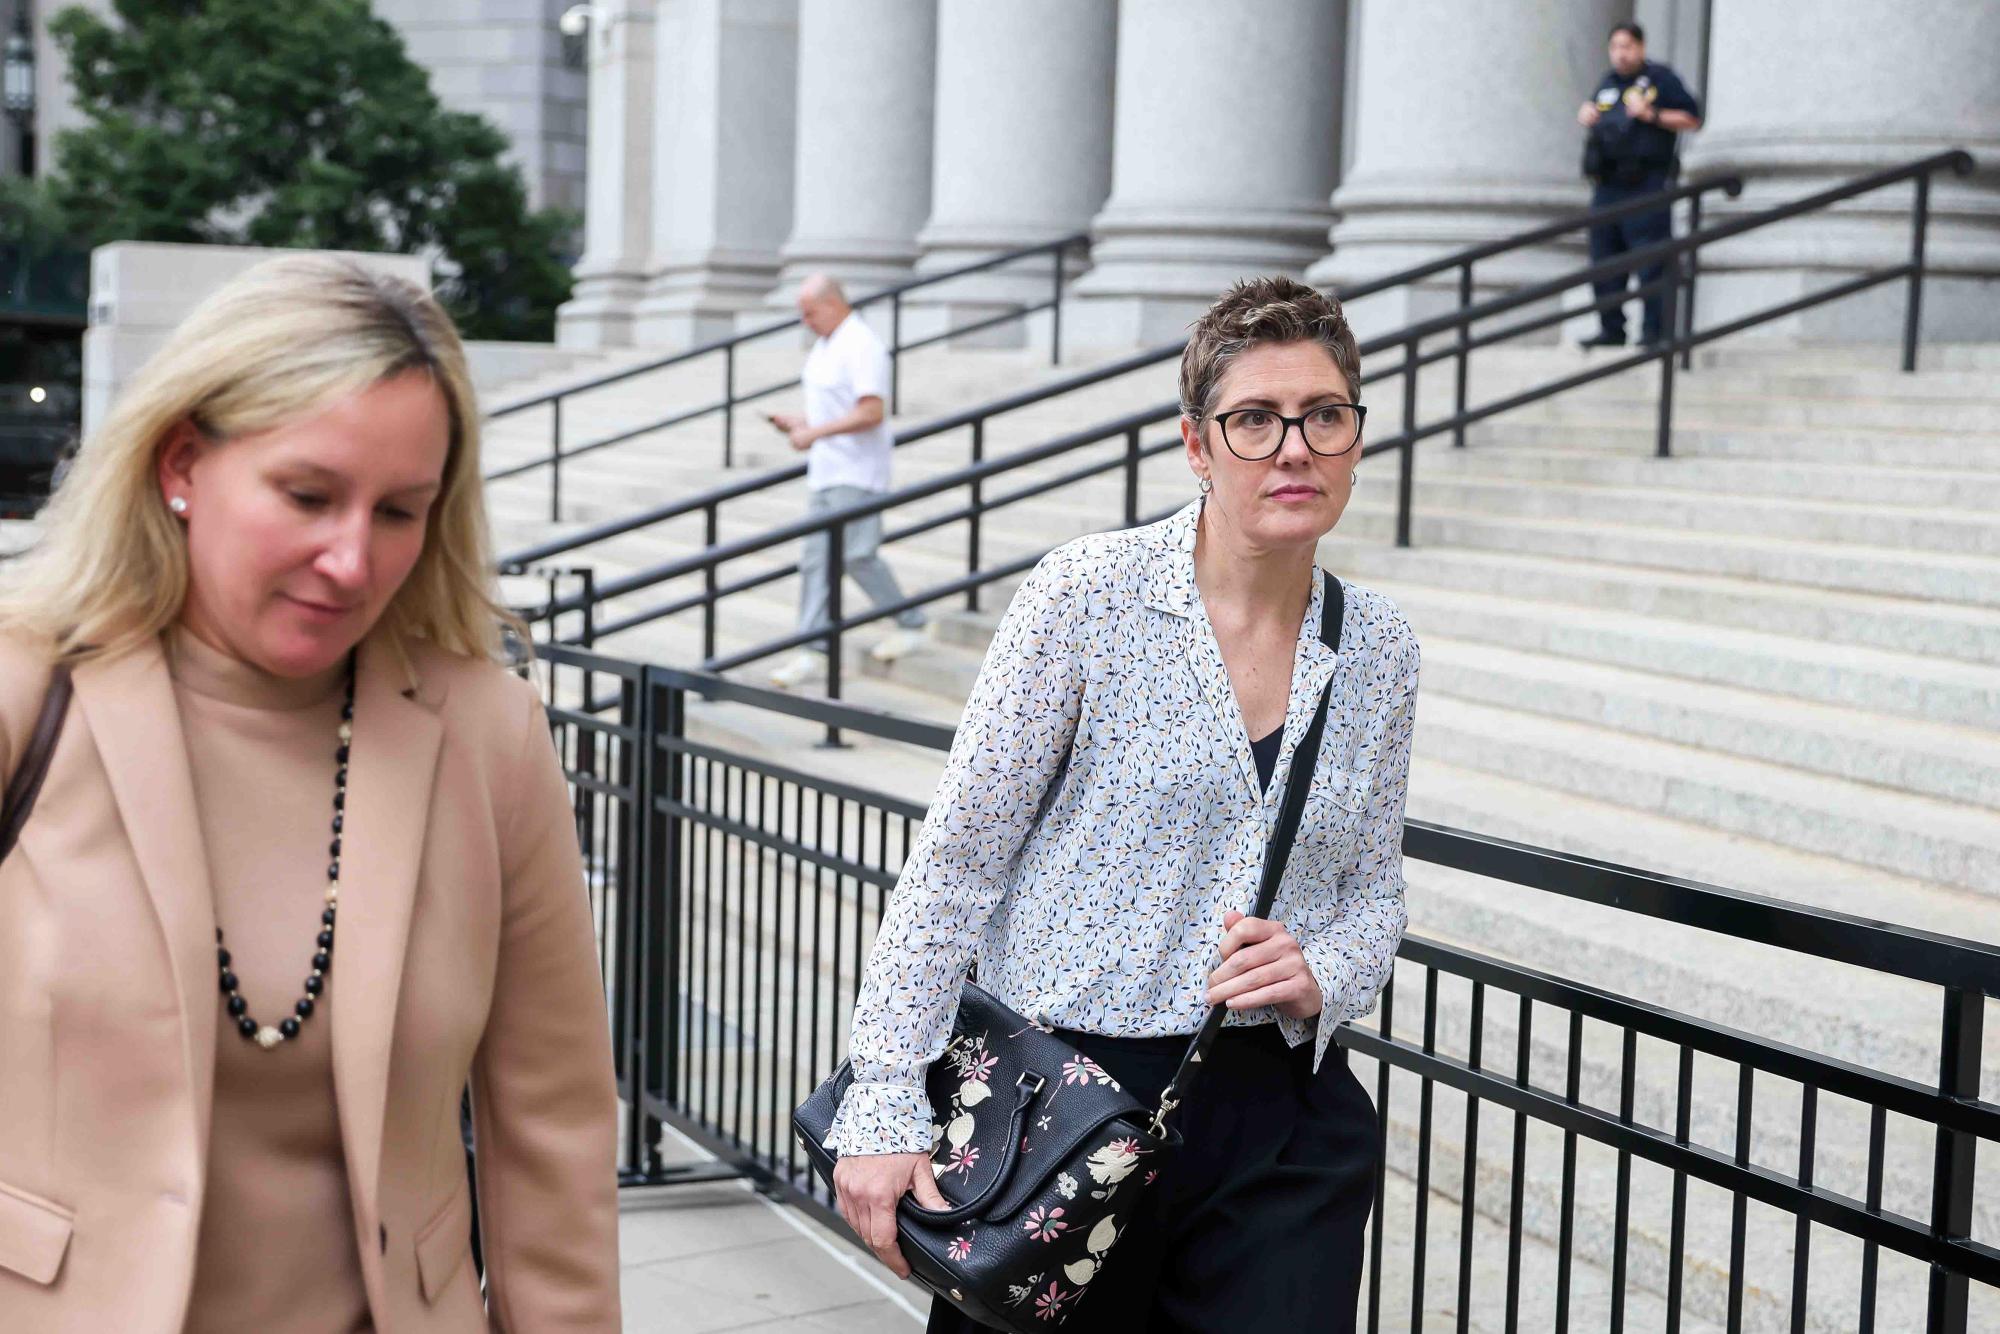

Fashion-Tech Fraud Case Signals Stricter Compliance Enforcement for E-Commerce Platforms
- $300M CaaStle fraud exposes regulatory gaps in fashion-tech sector; sellers face heightened due diligence requirements and compliance scrutiny




Overview
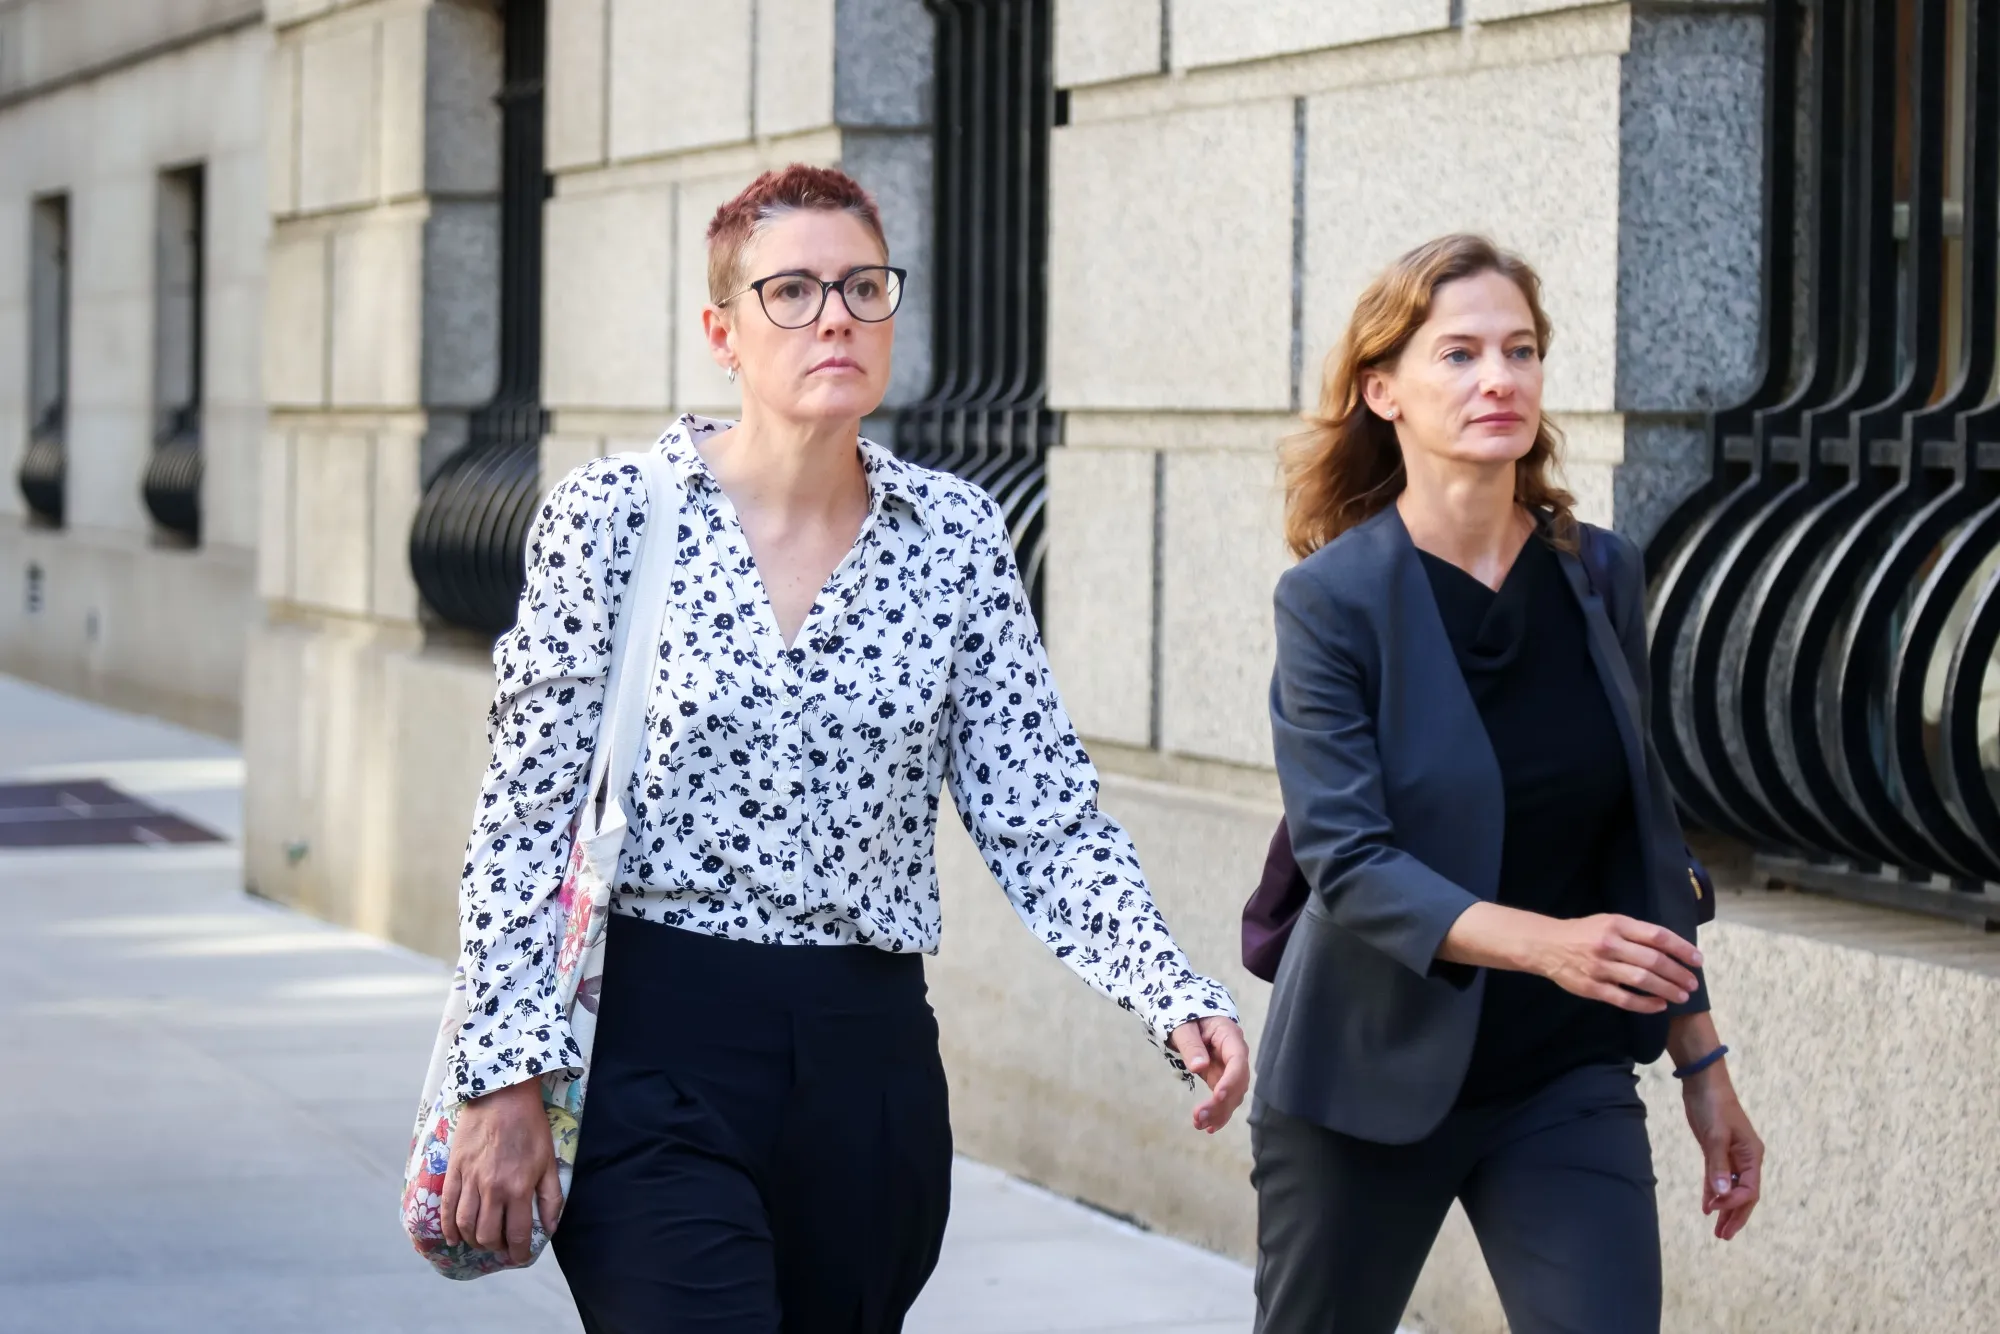
The sentencing of CaaStle founder Christine Hunsicker to five years in federal prison for orchestrating a $300 million securities fraud scheme (2019-2025) marks a critical inflection point in regulatory enforcement against fashion-tech platforms. Hunsicker's conviction for fabricating financial documents, falsifying audited statements, and misrepresenting company valuation at $1.4 billion—while concealing severe financial distress—demonstrates that federal prosecutors now treat investor deception in tech-enabled fashion businesses with the same severity as major fraud cases like Theranos ($800M fraud, Elizabeth Holmes serving 10 years). This precedent directly impacts e-commerce sellers and platform operators in three compliance dimensions.
First, investor verification and financial transparency requirements are tightening. The case reveals that CaaStle continued fraudulent activities even after law enforcement seized electronic devices in March 2025, indicating prosecutors view ongoing deception as aggravating. For sellers seeking venture funding or operating as funded platforms, this signals that due diligence processes—previously vulnerable to falsified bank records and fabricated shareholder documentation—are now subject to criminal liability. The Manhattan US Attorney's Office prosecution demonstrates federal focus on fashion-tech specifically, a sector where "rapid growth and innovation sometimes outpace compliance infrastructure" (per News 2). Sellers operating rental platforms, subscription models, or technology-enabled fashion services must now implement auditable financial controls and third-party verification systems. Estimated compliance cost: $50K-200K annually for mid-sized platforms to establish SOC 2 Type II certification, independent audits, and investor disclosure protocols.
Second, platform accountability for seller conduct is expanding. The comparison to Theranos suggests prosecutors view platform founders as personally liable for systemic misrepresentation—not just individual transactions. For marketplace operators and SaaS providers serving fashion sellers, this creates liability exposure if seller financial claims (inventory valuations, revenue projections, customer metrics) are not independently verified. Platforms like CaaStle that expanded to "selling its platform to external fashion companies" face heightened scrutiny of seller onboarding, financial vetting, and ongoing monitoring. Sellers using third-party platforms should expect new compliance requirements: verified business registration, tax ID validation, and periodic financial audits. Timeline: Expect new platform policies within 6-12 months as legal teams respond to this precedent.
Third, the fashion-rental category faces regulatory winnowing. CaaStle's bankruptcy (spring 2025) following fraud revelation eliminates a major platform competitor, but more importantly, it signals that fashion-tech platforms without robust compliance infrastructure cannot survive investor scrutiny. Sellers who previously relied on CaaStle's platform for customer acquisition, inventory management, or fulfillment now face platform exit risk. The case demonstrates that fashion-rental platforms—a "growing segment of the e-commerce industry" (News 2)—are now subject to the same regulatory intensity as fintech and biotech startups. Compliant sellers can exploit this by: (1) migrating to platforms with transparent financial reporting and third-party audits, (2) building direct-to-consumer channels to reduce platform dependency, (3) obtaining E&O insurance and compliance certifications to differentiate from non-compliant competitors.
Questions 8
What platform risks should sellers monitor after CaaStle's bankruptcy?
CaaStle's spring 2025 bankruptcy following fraud revelation demonstrates that fashion-tech platforms without transparent financial reporting face sudden collapse. Sellers relying on CaaStle for customer acquisition, inventory management, or fulfillment lost access to these services. Sellers should now evaluate platform financial health by requesting: audited financial statements, third-party compliance certifications, and insurance coverage for seller protection. Platforms without SOC 2 Type II certification or independent audits should be considered high-risk. Diversify across multiple platforms and build direct-to-consumer channels to reduce dependency on any single platform.
How can sellers differentiate themselves through compliance after this case?
Compliant sellers can exploit the regulatory winnowing by obtaining E&O insurance, third-party financial audits, and compliance certifications that non-compliant competitors lack. The case demonstrates that platforms and sellers with transparent financial reporting and independent verification survive regulatory scrutiny while others face bankruptcy. Sellers should advertise compliance credentials (SOC 2, audited financials, business liability insurance) to attract risk-averse buyers and platform operators. This creates a competitive moat: non-compliant sellers face platform removal or higher fees, while compliant sellers gain preferential treatment and lower compliance costs through scale.