



Persian Gulf Oil Crisis Drives 8.3M Barrel Shortage | Shipping & Energy Cost Impact for E-Commerce Sellers
- Global oil production down 10M barrels daily; shipping costs and energy-dependent product categories face 6-18% cost increases over 3-6 months


Overview
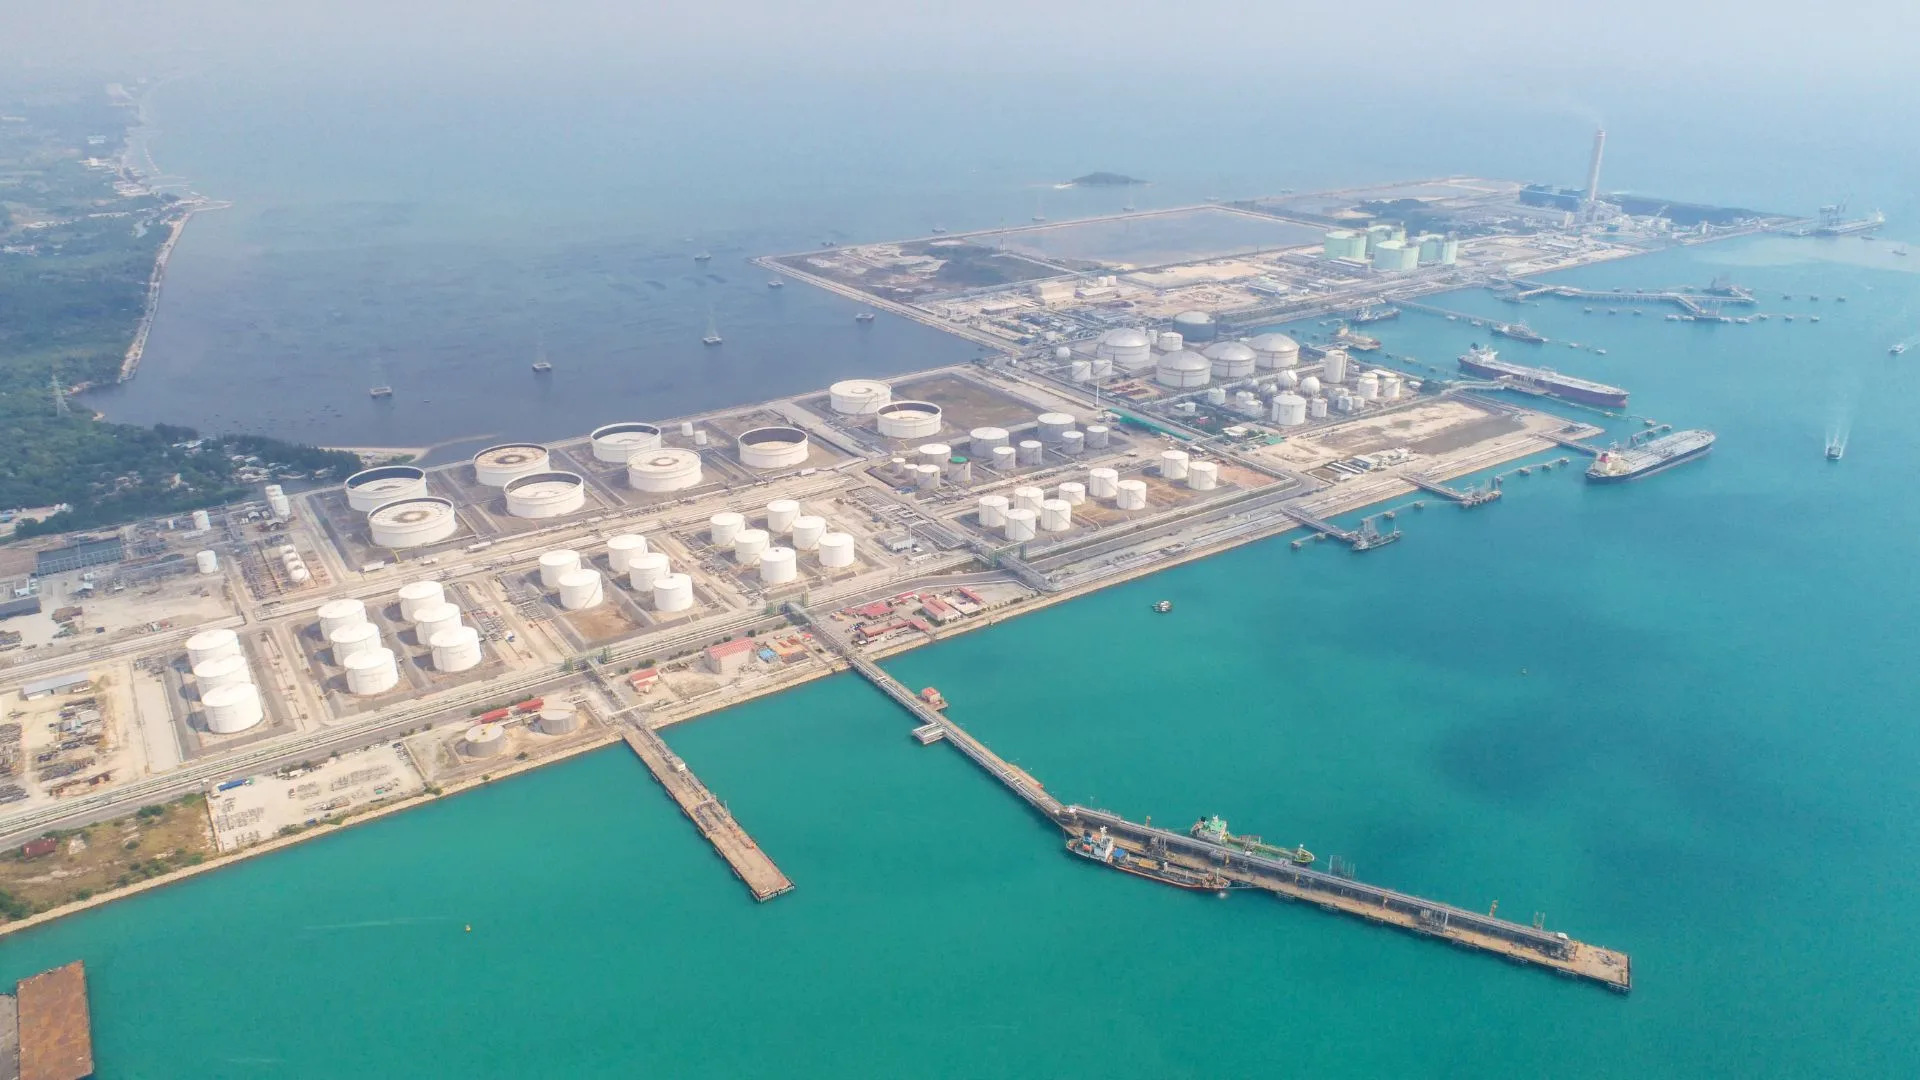
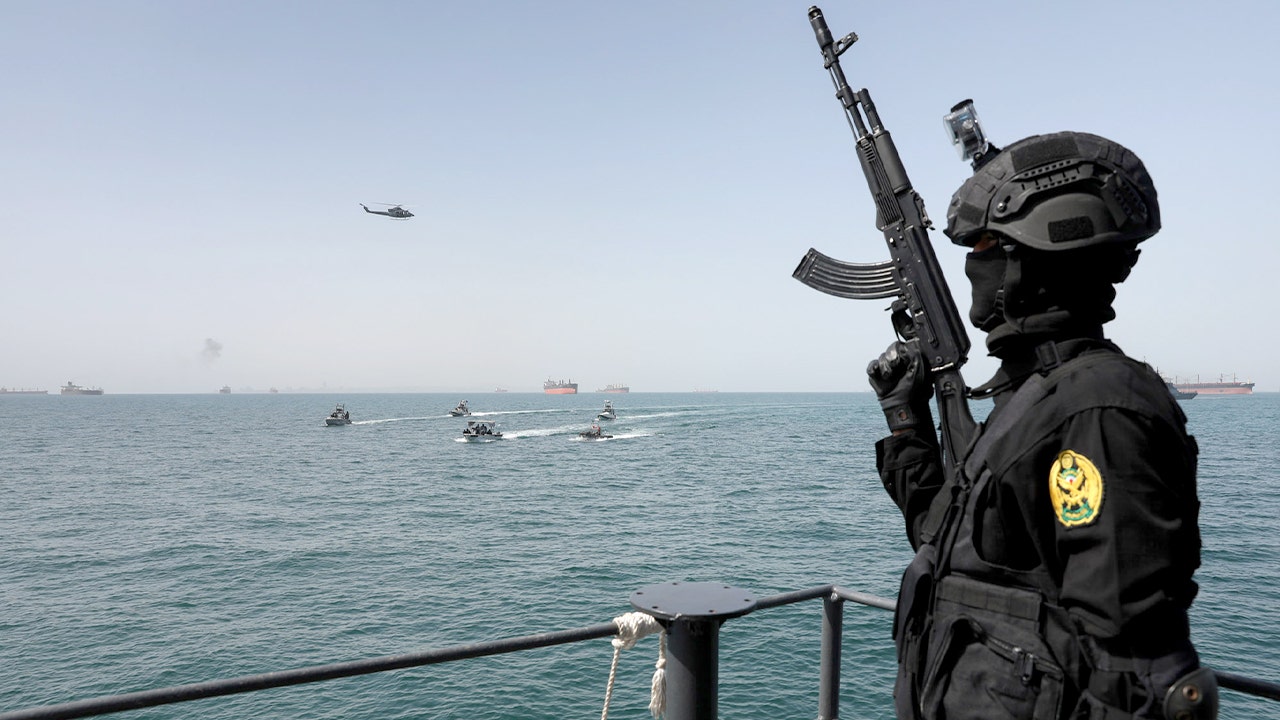
The Persian Gulf oil crisis represents a "world-changing" supply disruption with direct implications for cross-border e-commerce sellers across multiple operational dimensions. According to the International Energy Agency's August 12, 2026 Oil Market Report, Gulf oil production stands at 23.9 million barrels per day—8.3 million barrels below pre-war levels—with global production down approximately 10 million barrels daily. Petroleum geologist Art Berman warns that the deeper threat extends beyond Strait of Hormuz shipping disruptions; approximately 8 million barrels of Persian Gulf production remain shut in due to complex well-restart requirements that cannot be quickly reversed.
For e-commerce sellers, this creates a three-tier cost impact: First, shipping costs will increase 6-12% over the next 3-6 months as fuel surcharges compound across logistics networks. Sellers relying on air freight (electronics, fashion, perishables) face immediate pressure, with DHL and FedEx historically adding 2-4% fuel surcharges during oil price spikes above $80/barrel. Second, energy-intensive product categories face manufacturing cost increases: plastics/polymers (petroleum-derived), chemicals, textiles, and electronics manufacturing all depend on stable energy costs. Third, supply chain delays will extend 2-4 weeks as shipowners and insurers rebuild confidence in Hormuz transit, forcing sellers to increase safety stock and working capital.
The recovery timeline matters critically for inventory planning. Wood Mackenzie projects fields returning to 70% production capacity within 3 months and 90% within 6 months under controlled restart procedures, but Berman estimates 80% of affected wells could take weeks to months to restart, with some permanently reduced. This 3-6 month uncertainty window creates arbitrage opportunities for sellers with diversified sourcing: those sourcing from non-Gulf regions (Southeast Asia, West Africa, North America) can maintain cost advantages while Gulf-dependent suppliers face margin compression. Sellers in energy-intensive categories (home appliances, automotive parts, industrial equipment) should immediately review supplier concentration risk—if >30% of sourcing depends on Gulf oil-linked manufacturing, cost increases of $0.15-0.45 per unit are likely within 60 days.
The geopolitical dimension extends beyond energy: tanker insurance premiums in the Hormuz corridor have historically increased 15-25% during crisis periods, directly raising ocean freight costs for sellers shipping via Middle Eastern ports. Additionally, U.S. refineries require specific crude grades unavailable domestically, meaning American consumers face energy cost pass-through regardless of domestic production records—this affects all sellers shipping to US consumers through energy-dependent logistics networks.
Questions 8
Which product categories face the biggest cost increases from this oil disruption?
Energy-intensive categories face the highest impact: plastics/polymers (petroleum-derived), chemicals, textiles, electronics manufacturing, home appliances, and automotive parts. These categories depend on stable energy costs for production, and manufacturing cost increases of $0.15-0.45 per unit are likely within 60 days. Sellers in these categories should immediately audit supplier concentration—if >30% of sourcing depends on Gulf oil-linked manufacturing, margin compression of 3-8% is probable. Conversely, sellers in low-energy categories (books, apparel from non-petrochemical sources, digital products) face minimal direct impact and can gain competitive advantage by maintaining stable pricing.
How will the Persian Gulf oil crisis affect my shipping costs to Amazon FBA warehouses?
Shipping costs will increase 6-12% over the next 3-6 months as fuel surcharges compound across logistics networks. The International Energy Agency reports Gulf oil production is 8.3 million barrels below pre-war levels, driving global energy costs higher. For sellers using FedEx or DHL air freight, expect 2-4% fuel surcharges to activate within 30 days if oil prices remain elevated. Ocean freight via Middle Eastern ports will see 15-25% insurance premium increases due to Hormuz transit risks. Monitor your 3PL provider's fuel surcharge policies and consider shifting 20-30% of time-sensitive inventory to regional fulfillment centers to reduce air freight dependency.