


Oil Price Decline & Rising US Treasury Yields | Dual Impact on Cross-Border Seller Margins & Working Capital
- Freight costs drop 8-15% for Asia-to-West sellers while financing costs rise 2-3% due to 5% Treasury yields; European demand softens amid regional divergence






Overview
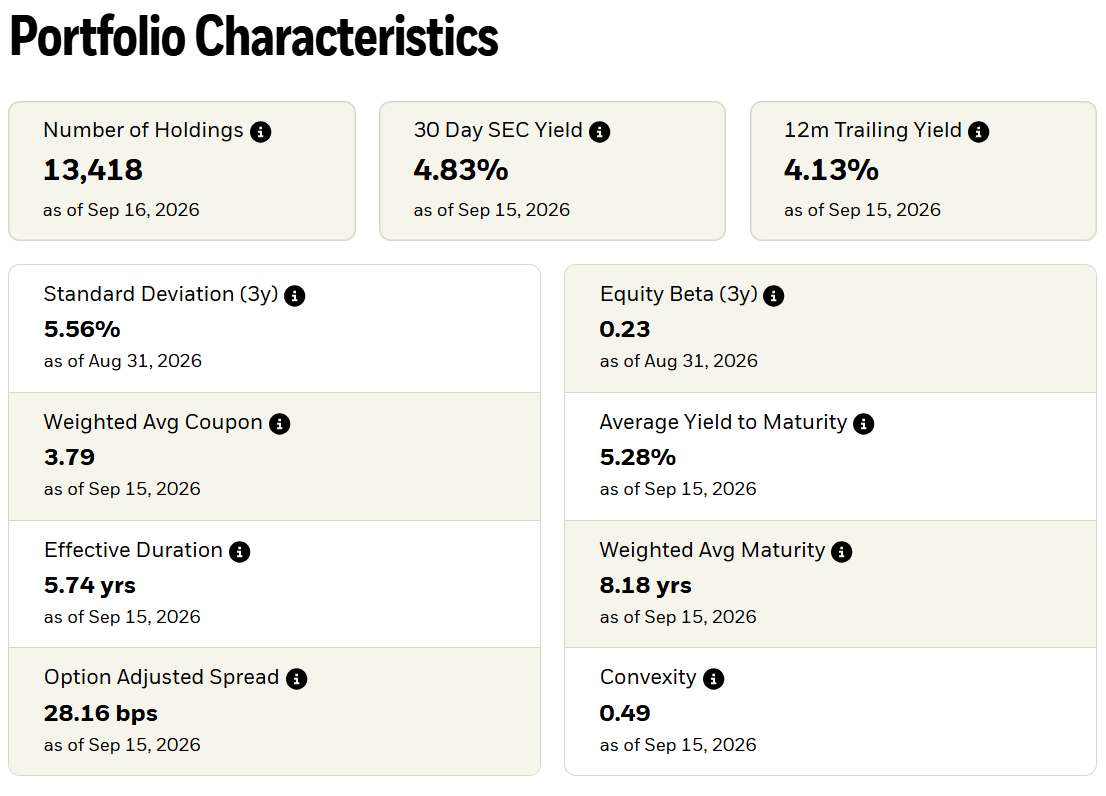
The December 19, 2024 market divergence presents a critical dual-edge opportunity for cross-border e-commerce sellers: declining oil prices are reducing logistics costs while rising US Treasury yields (hovering near 5%) are simultaneously increasing working capital financing expenses. Asian stock markets rallied on easing oil prices that benefit energy-importing economies, with key indices in Japan, South Korea, and Singapore gaining ground. However, European benchmarks declined, signaling softer consumer demand in key EU markets. Concurrently, Bank of America declared US Treasury bonds a "generational entry point," reflecting elevated yields that directly impact seller financing costs for inventory, logistics expansion, and operational growth.
For sellers shipping from Asia to Western markets, the immediate logistics advantage is substantial. Freight rates typically decline 8-15% when crude oil prices fall, directly improving margins for sellers reliant on air and sea freight. A seller shipping 500 units monthly via air freight from China to the US could save $1,200-2,400 monthly at current rate declines. This creates a 30-60 day window to lock in lower freight contracts before rates stabilize. However, this cost savings is partially offset by rising financing costs: the 5% Treasury yield environment increases APR rates for inventory financing, PO financing, and working capital loans by 200-300 basis points compared to 2023 levels. Sellers financing $100K in inventory at 8-10% APR now face $8-10K annual costs versus $5-6K previously—a $2-4K annual headwind.
The regional divergence creates strategic portfolio implications. European market weakness signals potential 10-20% demand softness for sellers targeting EU customers, particularly in discretionary categories (electronics, apparel, home goods). Simultaneously, Asian manufacturing cost advantages are amplifying due to lower energy input costs, making Asia-based sourcing more competitive. Sellers should immediately: (1) Lock in freight rates for Q1 2025 shipments within 14 days before rates rebound; (2) Evaluate alternative financing sources—trade finance and supply chain financing products now offer 6-7% rates versus traditional bank loans at 8-10%, unlocking 100-200 bps savings; (3) Rebalance inventory allocation away from EU markets toward US/Asia-Pacific where demand remains stronger; (4) Consider invoice factoring to accelerate cash conversion cycles, converting 45-60 day payment terms to 15-20 days at 2-3% discount rates. The cash flow unlock potential is significant: a $500K monthly revenue seller could free up $75-150K working capital through factoring, offsetting higher financing costs.
Questions 8
How much can sellers save on freight costs from declining oil prices?
Freight rates typically decline 8-15% when crude oil prices fall, translating to $1,200-2,400 monthly savings for sellers shipping 500 units via air freight from Asia to the US. The news reports Asian markets rallied on December 19, 2024 due to easing oil prices that reduce energy input costs. Sellers should lock in lower freight contracts within 14 days before rates stabilize. However, these savings are partially offset by rising Treasury yields increasing financing costs by 200-300 basis points, so net margin improvement is 4-8% rather than the full freight savings.
Should I shift inventory away from European markets?
Yes, the news reports European benchmarks declined on December 19, 2024 while Asian markets rallied, indicating divergent regional economic outlooks. European weakness may reflect concerns about economic growth headwinds and monetary policy tightening, potentially signaling 10-20% demand softness for sellers targeting EU customers. The divergence suggests importance of diversified market exposure. Sellers should rebalance inventory allocation away from EU markets toward US and Asia-Pacific where demand remains stronger. Monitor European consumer spending data weekly and consider shifting 20-30% of inventory from EU-focused SKUs to US/Asia-focused products within 30 days.