

Crypto Regulatory Shift: SEC/CFTC Agency Rules Replace Failed Clarity Act | Seller Compliance Impact
- Senate defeats landmark crypto bill 49-50; regulators bypass Congress with tokenized assets, no-action relief, and independent rulemaking affecting crypto payment processors and blockchain-based commerce platforms







Overview
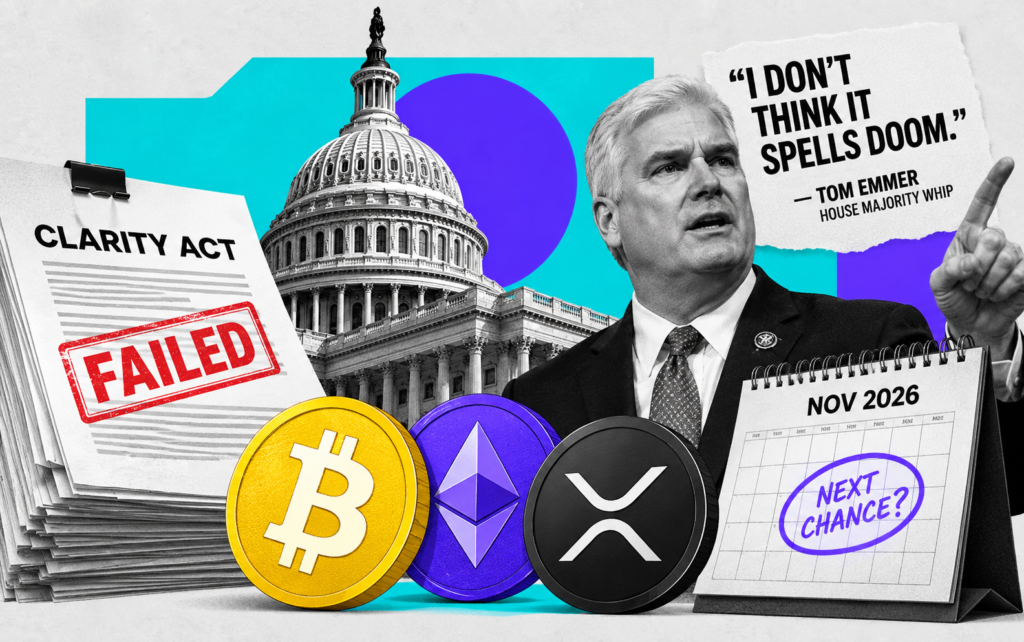
The Senate's failure to advance the Clarity Act on a 49-50 procedural vote represents a fundamental shift in cryptocurrency regulation from legislative to agency-led governance. The bill, which underwent over a year of bipartisan negotiations with 120+ negotiated changes, fell 11 votes short of the 60-vote threshold needed for passage. This defeat has immediate implications for e-commerce sellers accepting cryptocurrency payments and operating on blockchain-based marketplaces. SEC Chair Paul Atkins explicitly tied the agency's new tokenized-stock innovation exemption to the Clarity Act's failure, releasing the measure to enable onchain trading of U.S. stocks. Simultaneously, the CFTC advanced its regulatory agenda by issuing no-action relief for passive software providers and submitting broader crypto markets rulemaking proposals to the White House.
For cross-border e-commerce sellers, this regulatory fragmentation creates both compliance barriers and opportunities. The shift from unified Congressional standards to independent SEC and CFTC rulemaking means sellers must now navigate divergent regulatory frameworks rather than a single comprehensive standard. Sellers accepting cryptocurrency payments (Bitcoin, Ethereum, stablecoins) face uncertainty about which agency has primary jurisdiction over their transactions. The SEC's tokenized-stock exemption opens new product categories—digital securities and blockchain-based equity offerings—but requires sellers to understand securities law compliance. The CFTC's no-action relief for passive software providers creates a compliance pathway for payment processors and blockchain infrastructure providers, but this relief is temporary and subject to future enforcement discretion.
Industry sentiment has shifted decisively toward regulatory guidance over legislative solutions. Kristin Smith, president of the Solana Policy Institute, stated that "regulatory guidance represents the more viable path forward right now" rather than waiting for Congressional action. This reflects growing fatigue with the legislative process and indicates that sellers should expect rapid agency rulemaking rather than stable statutory frameworks. The regulatory-led approach bypasses gridlock but raises questions about consistency and comprehensive market oversight—meaning compliance requirements could shift as different agencies issue guidance independently. For sellers operating crypto payment systems, blockchain-based marketplaces, or tokenized product offerings, the immediate priority is monitoring SEC and CFTC guidance releases rather than waiting for Congressional action. The 49-50 vote breakdown, with seven negotiating Democrats signaling continued commitment to bipartisan efforts, suggests legislative efforts may resume, but regulatory action will likely establish de facto standards in the interim.
Questions 8
What does industry preference for regulatory guidance over legislation mean for sellers?
Kristin Smith, president of the Solana Policy Institute, stated that regulatory guidance represents 'the more viable path forward right now' rather than waiting for Congressional action. This reflects industry consensus that agency rulemaking will establish de facto standards faster than legislation. For sellers, this means: (1) regulatory guidance will change frequently as agencies issue new interpretations, (2) compliance requirements may shift with new administrations and agency leadership, and (3) sellers must establish continuous monitoring systems rather than one-time compliance audits. The regulatory-led approach also creates opportunities for sellers offering compliance consulting, regulatory tracking, and compliance automation services. Sellers should subscribe to SEC and CFTC press release alerts, monitor Federal Register notices, and establish quarterly compliance reviews to track regulatory changes. The industry fatigue with legislative processes suggests Congress may not pass comprehensive crypto legislation for 2-3 years, making agency guidance the primary compliance source.
How should sellers prepare for the CFTC's broader crypto markets rulemaking?
The CFTC submitted a broader crypto markets rulemaking proposal to the White House for review, indicating comprehensive permanent rules are coming. This rulemaking will likely address market manipulation, custody standards, derivatives trading, and stablecoin regulation. Sellers should prepare by: (1) documenting current compliance practices against anticipated CFTC requirements, (2) identifying gaps between current operations and likely regulatory standards, (3) building compliance infrastructure for custody, anti-manipulation monitoring, and transaction reporting, and (4) establishing relationships with compliance consultants and legal advisors specializing in crypto regulation. The rulemaking process typically takes 12-18 months from White House review to final rule publication, giving sellers a planning window. Sellers should also monitor state-level crypto regulations—New York's BitLicense and other state frameworks may impose additional requirements. The CFTC rulemaking will likely increase compliance costs by 15-30% for crypto payment processors and marketplace operators.
Why did the CFTC issue no-action relief for passive software providers?
The CFTC issued no-action relief to enable blockchain infrastructure providers and payment processors to operate without immediate regulatory enforcement. No-action relief means the agency commits not to pursue enforcement against specified activities for a defined period. This benefits sellers operating crypto payment systems, wallet services, and blockchain marketplaces by providing temporary legal certainty. However, no-action relief is discretionary and can be withdrawn—it's not a permanent compliance pathway. The CFTC simultaneously submitted a broader crypto markets rulemaking proposal to the White House, indicating permanent rules are coming. Sellers relying on no-action relief should use this window to build compliance infrastructure and prepare for stricter permanent regulations. The relief typically lasts 12-24 months, so sellers should plan for regulatory changes within 18 months.
How does regulatory fragmentation between SEC and CFTC affect cross-border sellers?
The shift from unified Congressional standards to independent SEC and CFTC rulemaking creates regulatory arbitrage opportunities but also compliance complexity. The SEC focuses on securities (tokenized stocks, digital equity offerings), while the CFTC focuses on commodities (Bitcoin, Ethereum, futures). A seller offering both tokenized securities and commodity trading faces dual compliance obligations. Cross-border sellers must also navigate international regulatory frameworks—the EU's Markets in Crypto Assets Regulation (MiCA) and Singapore's Payment Services Act create additional requirements. The regulatory fragmentation means sellers cannot rely on a single compliance framework. Instead, sellers should map their specific products against SEC and CFTC jurisdiction, identify which agency has primary authority, and build compliance systems for each jurisdiction separately. This increases compliance costs by 20-40% compared to unified standards.
How does the Clarity Act's defeat affect sellers accepting cryptocurrency payments?
The Senate's 49-50 vote failure means sellers no longer have a unified Congressional framework for crypto transactions. Instead, the SEC and CFTC are issuing independent guidance—the SEC released a tokenized-stock exemption enabling onchain trading, while the CFTC issued no-action relief for passive software providers. Sellers accepting Bitcoin, Ethereum, or stablecoins must now monitor both agencies' guidance rather than following a single standard. This creates compliance uncertainty: payment processors may face different requirements depending on whether the SEC or CFTC claims jurisdiction. Sellers should immediately audit their crypto payment systems against current SEC and CFTC guidance and establish monitoring protocols for new agency releases.
What is the SEC's tokenized-stock exemption and how does it create seller opportunities?
SEC Chair Paul Atkins explicitly tied the agency's new tokenized-stock innovation exemption to the Clarity Act's failure, releasing it to enable onchain trading of U.S. stocks. This exemption allows companies to issue digital securities on blockchain networks without full securities registration. For e-commerce sellers, this creates opportunities in three areas: (1) selling blockchain infrastructure tools to companies issuing tokenized securities, (2) offering custody and wallet services for digital asset holders, and (3) creating educational content and compliance consulting services. However, sellers offering these services must comply with securities law—this is not a regulatory-free zone. The exemption is temporary and subject to SEC review, so sellers should treat this as a time-limited opportunity window to establish market position before permanent rules are finalized.
What are the risks of relying on temporary no-action relief for crypto payment systems?
The CFTC's no-action relief provides temporary legal certainty but carries significant risks. No-action relief can be withdrawn at any time, leaving sellers without compliance protection. If the CFTC withdraws relief or issues enforcement guidance contradicting the relief, sellers operating under the relief may face retroactive enforcement. Additionally, no-action relief typically applies only to specified activities—if sellers expand their services beyond the relief scope, they lose protection. Sellers relying on no-action relief should: (1) document exactly which activities are covered by the relief, (2) avoid expanding services beyond relief scope without new guidance, (3) build permanent compliance infrastructure in parallel with relief reliance, and (4) establish contingency plans for relief withdrawal. The risk is particularly acute for payment processors and marketplace operators serving multiple customer segments—different customer types may face different regulatory treatment. Sellers should treat no-action relief as a 12-24 month bridge to permanent compliance infrastructure, not a long-term compliance strategy.
Which seller categories face the highest compliance costs from regulatory fragmentation?
Sellers offering multiple crypto services face the highest compliance costs due to regulatory fragmentation. Specifically: (1) Crypto payment processors accepting multiple asset types (Bitcoin, Ethereum, stablecoins) must comply with both SEC and CFTC frameworks—estimated compliance cost $200K-500K annually for mid-sized processors. (2) Blockchain marketplace operators offering both tokenized securities and commodity trading face dual compliance obligations—estimated cost $300K-800K annually. (3) Cross-border sellers operating in multiple jurisdictions (US, EU, Asia) must navigate divergent regulatory frameworks—estimated cost $400K-1.2M annually. (4) Stablecoin issuers and custodians face the most complex compliance landscape with requirements from SEC, CFTC, Federal Reserve, and state regulators—estimated cost $500K-2M annually. Sellers offering single-service offerings (e.g., Bitcoin payment processing only) face lower compliance costs of $50K-150K annually. The regulatory fragmentation creates a competitive advantage for large sellers with compliance resources and disadvantages small sellers, likely consolidating the market toward 5-10 major platforms.
What does industry preference for regulatory guidance over legislation mean for sellers?
Kristin Smith, president of the Solana Policy Institute, stated that regulatory guidance represents 'the more viable path forward right now' rather than waiting for Congressional action. This reflects industry consensus that agency rulemaking will establish de facto standards faster than legislation. For sellers, this means: (1) regulatory guidance will change frequently as agencies issue new interpretations, (2) compliance requirements may shift with new administrations and agency leadership, and (3) sellers must establish continuous monitoring systems rather than one-time compliance audits. The regulatory-led approach also creates opportunities for sellers offering compliance consulting, regulatory tracking, and compliance automation services. Sellers should subscribe to SEC and CFTC press release alerts, monitor Federal Register notices, and establish quarterly compliance reviews to track regulatory changes. The industry fatigue with legislative processes suggests Congress may not pass comprehensive crypto legislation for 2-3 years, making agency guidance the primary compliance source.
How should sellers prepare for the CFTC's broader crypto markets rulemaking?
The CFTC submitted a broader crypto markets rulemaking proposal to the White House for review, indicating comprehensive permanent rules are coming. This rulemaking will likely address market manipulation, custody standards, derivatives trading, and stablecoin regulation. Sellers should prepare by: (1) documenting current compliance practices against anticipated CFTC requirements, (2) identifying gaps between current operations and likely regulatory standards, (3) building compliance infrastructure for custody, anti-manipulation monitoring, and transaction reporting, and (4) establishing relationships with compliance consultants and legal advisors specializing in crypto regulation. The rulemaking process typically takes 12-18 months from White House review to final rule publication, giving sellers a planning window. Sellers should also monitor state-level crypto regulations—New York's BitLicense and other state frameworks may impose additional requirements. The CFTC rulemaking will likely increase compliance costs by 15-30% for crypto payment processors and marketplace operators.
Why did the CFTC issue no-action relief for passive software providers?
The CFTC issued no-action relief to enable blockchain infrastructure providers and payment processors to operate without immediate regulatory enforcement. No-action relief means the agency commits not to pursue enforcement against specified activities for a defined period. This benefits sellers operating crypto payment systems, wallet services, and blockchain marketplaces by providing temporary legal certainty. However, no-action relief is discretionary and can be withdrawn—it's not a permanent compliance pathway. The CFTC simultaneously submitted a broader crypto markets rulemaking proposal to the White House, indicating permanent rules are coming. Sellers relying on no-action relief should use this window to build compliance infrastructure and prepare for stricter permanent regulations. The relief typically lasts 12-24 months, so sellers should plan for regulatory changes within 18 months.
How does regulatory fragmentation between SEC and CFTC affect cross-border sellers?
The shift from unified Congressional standards to independent SEC and CFTC rulemaking creates regulatory arbitrage opportunities but also compliance complexity. The SEC focuses on securities (tokenized stocks, digital equity offerings), while the CFTC focuses on commodities (Bitcoin, Ethereum, futures). A seller offering both tokenized securities and commodity trading faces dual compliance obligations. Cross-border sellers must also navigate international regulatory frameworks—the EU's Markets in Crypto Assets Regulation (MiCA) and Singapore's Payment Services Act create additional requirements. The regulatory fragmentation means sellers cannot rely on a single compliance framework. Instead, sellers should map their specific products against SEC and CFTC jurisdiction, identify which agency has primary authority, and build compliance systems for each jurisdiction separately. This increases compliance costs by 20-40% compared to unified standards.
How does the Clarity Act's defeat affect sellers accepting cryptocurrency payments?
The Senate's 49-50 vote failure means sellers no longer have a unified Congressional framework for crypto transactions. Instead, the SEC and CFTC are issuing independent guidance—the SEC released a tokenized-stock exemption enabling onchain trading, while the CFTC issued no-action relief for passive software providers. Sellers accepting Bitcoin, Ethereum, or stablecoins must now monitor both agencies' guidance rather than following a single standard. This creates compliance uncertainty: payment processors may face different requirements depending on whether the SEC or CFTC claims jurisdiction. Sellers should immediately audit their crypto payment systems against current SEC and CFTC guidance and establish monitoring protocols for new agency releases.
What is the SEC's tokenized-stock exemption and how does it create seller opportunities?
SEC Chair Paul Atkins explicitly tied the agency's new tokenized-stock innovation exemption to the Clarity Act's failure, releasing it to enable onchain trading of U.S. stocks. This exemption allows companies to issue digital securities on blockchain networks without full securities registration. For e-commerce sellers, this creates opportunities in three areas: (1) selling blockchain infrastructure tools to companies issuing tokenized securities, (2) offering custody and wallet services for digital asset holders, and (3) creating educational content and compliance consulting services. However, sellers offering these services must comply with securities law—this is not a regulatory-free zone. The exemption is temporary and subject to SEC review, so sellers should treat this as a time-limited opportunity window to establish market position before permanent rules are finalized.
What are the risks of relying on temporary no-action relief for crypto payment systems?
The CFTC's no-action relief provides temporary legal certainty but carries significant risks. No-action relief can be withdrawn at any time, leaving sellers without compliance protection. If the CFTC withdraws relief or issues enforcement guidance contradicting the relief, sellers operating under the relief may face retroactive enforcement. Additionally, no-action relief typically applies only to specified activities—if sellers expand their services beyond the relief scope, they lose protection. Sellers relying on no-action relief should: (1) document exactly which activities are covered by the relief, (2) avoid expanding services beyond relief scope without new guidance, (3) build permanent compliance infrastructure in parallel with relief reliance, and (4) establish contingency plans for relief withdrawal. The risk is particularly acute for payment processors and marketplace operators serving multiple customer segments—different customer types may face different regulatory treatment. Sellers should treat no-action relief as a 12-24 month bridge to permanent compliance infrastructure, not a long-term compliance strategy.
Which seller categories face the highest compliance costs from regulatory fragmentation?
Sellers offering multiple crypto services face the highest compliance costs due to regulatory fragmentation. Specifically: (1) Crypto payment processors accepting multiple asset types (Bitcoin, Ethereum, stablecoins) must comply with both SEC and CFTC frameworks—estimated compliance cost $200K-500K annually for mid-sized processors. (2) Blockchain marketplace operators offering both tokenized securities and commodity trading face dual compliance obligations—estimated cost $300K-800K annually. (3) Cross-border sellers operating in multiple jurisdictions (US, EU, Asia) must navigate divergent regulatory frameworks—estimated cost $400K-1.2M annually. (4) Stablecoin issuers and custodians face the most complex compliance landscape with requirements from SEC, CFTC, Federal Reserve, and state regulators—estimated cost $500K-2M annually. Sellers offering single-service offerings (e.g., Bitcoin payment processing only) face lower compliance costs of $50K-150K annually. The regulatory fragmentation creates a competitive advantage for large sellers with compliance resources and disadvantages small sellers, likely consolidating the market toward 5-10 major platforms.
What does industry preference for regulatory guidance over legislation mean for sellers?
Kristin Smith, president of the Solana Policy Institute, stated that regulatory guidance represents 'the more viable path forward right now' rather than waiting for Congressional action. This reflects industry consensus that agency rulemaking will establish de facto standards faster than legislation. For sellers, this means: (1) regulatory guidance will change frequently as agencies issue new interpretations, (2) compliance requirements may shift with new administrations and agency leadership, and (3) sellers must establish continuous monitoring systems rather than one-time compliance audits. The regulatory-led approach also creates opportunities for sellers offering compliance consulting, regulatory tracking, and compliance automation services. Sellers should subscribe to SEC and CFTC press release alerts, monitor Federal Register notices, and establish quarterly compliance reviews to track regulatory changes. The industry fatigue with legislative processes suggests Congress may not pass comprehensive crypto legislation for 2-3 years, making agency guidance the primary compliance source.
How should sellers prepare for the CFTC's broader crypto markets rulemaking?
The CFTC submitted a broader crypto markets rulemaking proposal to the White House for review, indicating comprehensive permanent rules are coming. This rulemaking will likely address market manipulation, custody standards, derivatives trading, and stablecoin regulation. Sellers should prepare by: (1) documenting current compliance practices against anticipated CFTC requirements, (2) identifying gaps between current operations and likely regulatory standards, (3) building compliance infrastructure for custody, anti-manipulation monitoring, and transaction reporting, and (4) establishing relationships with compliance consultants and legal advisors specializing in crypto regulation. The rulemaking process typically takes 12-18 months from White House review to final rule publication, giving sellers a planning window. Sellers should also monitor state-level crypto regulations—New York's BitLicense and other state frameworks may impose additional requirements. The CFTC rulemaking will likely increase compliance costs by 15-30% for crypto payment processors and marketplace operators.