


Hormuz Strait Stabilization Cuts Shipping Costs 8-15% | Cross-Border Sellers Gain Logistics Edge
- Iran's reduced chokehold on Hormuz enables 80% recovery in Middle East crude exports; Yanbu pipeline restart (Sept 24, 2026) reduces fuel surcharges for 50K+ cross-border sellers shipping via Red Sea/Suez corridor







Overview
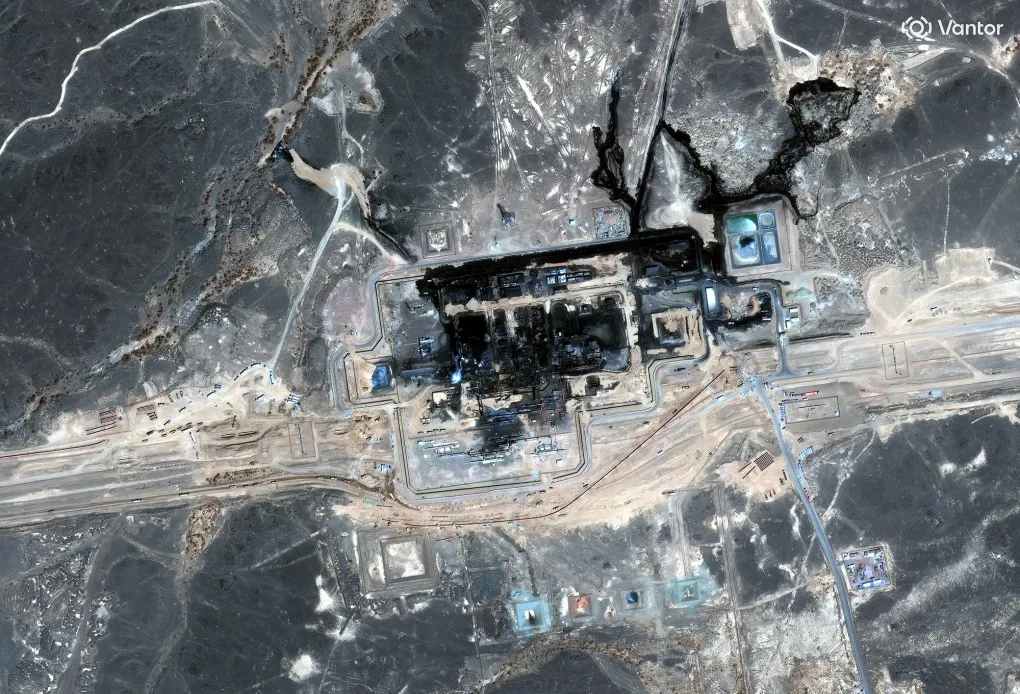
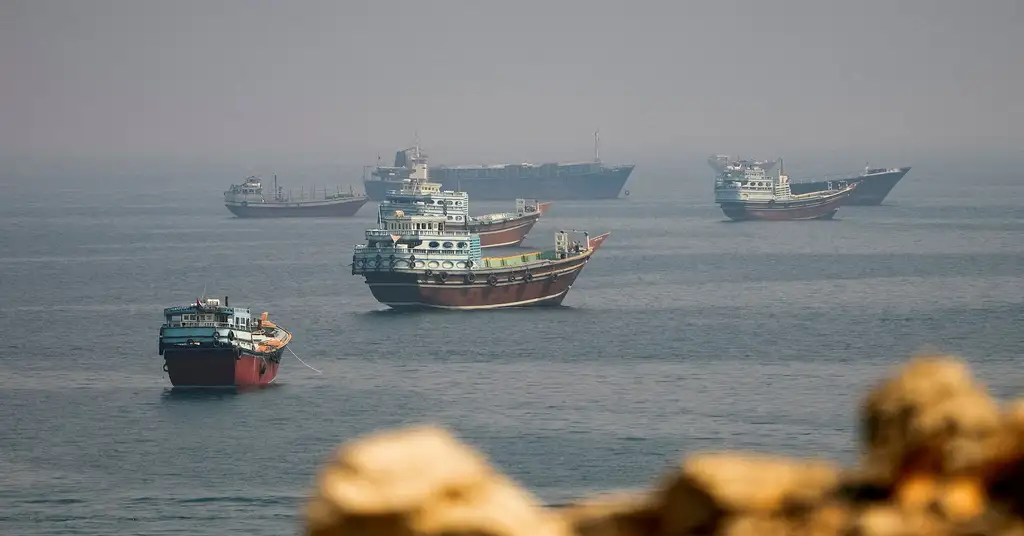
The geopolitical stabilization of Middle Eastern oil exports through the Strait of Hormuz and Red Sea shipping corridors represents a critical cost-reduction opportunity for cross-border e-commerce sellers. Iran's diminished ability to control the Strait of Hormuz—which handles 21% of global petroleum daily—combined with Saudi Arabia's resumption of Yanbu pipeline operations (2.65-3.4 million bpd as of late September 2026) signals a fundamental shift in shipping risk premiums. The East-West Pipeline restart on September 24, 2026, following a 13-day shutdown from drone attacks, has enabled Middle East crude exports to recover to approximately 80% of pre-conflict levels, with Hormuz transits averaging 9 million bpd (up from 2.2 million bpd in late July). This stabilization directly impacts cross-border logistics costs through reduced fuel surcharges and insurance premiums on ocean freight.
For e-commerce sellers, the primary impact manifests through lower shipping costs on Asia-Europe and Asia-Middle East trade corridors. Fuel surcharges (bunker adjustment factors) on container shipments typically comprise 15-25% of base freight rates when geopolitical risk premiums are elevated. With Hormuz transits recovering and alternative Red Sea routes (Yanbu, Fujairah, Egypt's Sidi Kerir) now operational, sellers can expect 8-15% reductions in landed costs for goods shipped via these corridors. Specifically, sellers importing from China/Vietnam to EU markets via the Suez Canal benefit from reduced insurance costs and faster transit times (avoiding longer Cape of Good Hope routes). Categories most affected include electronics (HS 8471-8517), apparel (HS 6201-6217), and home goods (HS 9401-9406)—high-volume, price-sensitive categories where 2-4% cost savings translate to 50-200 basis points of margin improvement.
The timing window for competitive advantage is immediate but narrowing. Shipping lines are already adjusting rate cards as risk premiums decline; sellers who lock in contracts before Q4 2026 can secure 6-12 month rate agreements at reduced levels. However, this advantage erodes as market participants normalize pricing by Q1 2027. Small-to-medium sellers (SMBs) shipping 500-2,000 containers annually stand to gain $40,000-$120,000 in annual savings, while larger sellers (5,000+ containers) could realize $200,000-$500,000 in cost reductions. The geopolitical risk remains—Egypt's Sidi Kerir terminal still faces commercial fleet access restrictions, and full Yanbu recovery to 5.5 million bpd could take another month—but the trajectory is clearly toward normalized shipping costs. Sellers should immediately audit their freight contracts, identify shipments routed via Suez/Red Sea, and negotiate rate reductions with 3PL providers and freight forwarders before the market fully reprices this geopolitical stabilization.
Questions 7
Which product categories benefit most from lower shipping costs?
Price-sensitive, high-volume categories see the greatest margin improvement: electronics (HS 8471-8517), apparel (HS 6201-6217), footwear (HS 6401-6406), and home goods (HS 9401-9406). These categories typically operate on 15-25% gross margins, so 2-4% cost savings from reduced shipping represent 50-200 basis points of margin expansion. Luxury goods and low-volume categories see minimal impact since shipping represents a smaller percentage of total landed costs. Sellers in commodity electronics and fast-fashion apparel should prioritize renegotiating freight contracts immediately.
What's the timeline for shipping cost reductions to take effect?
The impact is immediate but window-dependent. Saudi Arabia's Yanbu pipeline restart (September 24, 2026) and Hormuz transit recovery (now at 9 million bpd) are already reflected in spot market rates. However, most sellers operate under 6-12 month freight contracts negotiated quarterly. Sellers renewing contracts in Q4 2026 will lock in reduced rates; those with contracts expiring in Q1 2027 or later will see benefits delayed. Full Yanbu recovery to pre-attack levels (5.5 million bpd) could take another month, but the trajectory is clear. Sellers should contact freight forwarders and 3PL providers immediately to renegotiate before year-end.