


Middle East Oil Supply Stabilization Reshapes Global Shipping Costs | Cross-Border Seller Impact
- Oil exports recover to 92% of pre-war levels; pipeline bypasses reduce Strait of Hormuz dependency; shipping costs stabilize for cross-border sellers in September 2024

Overview
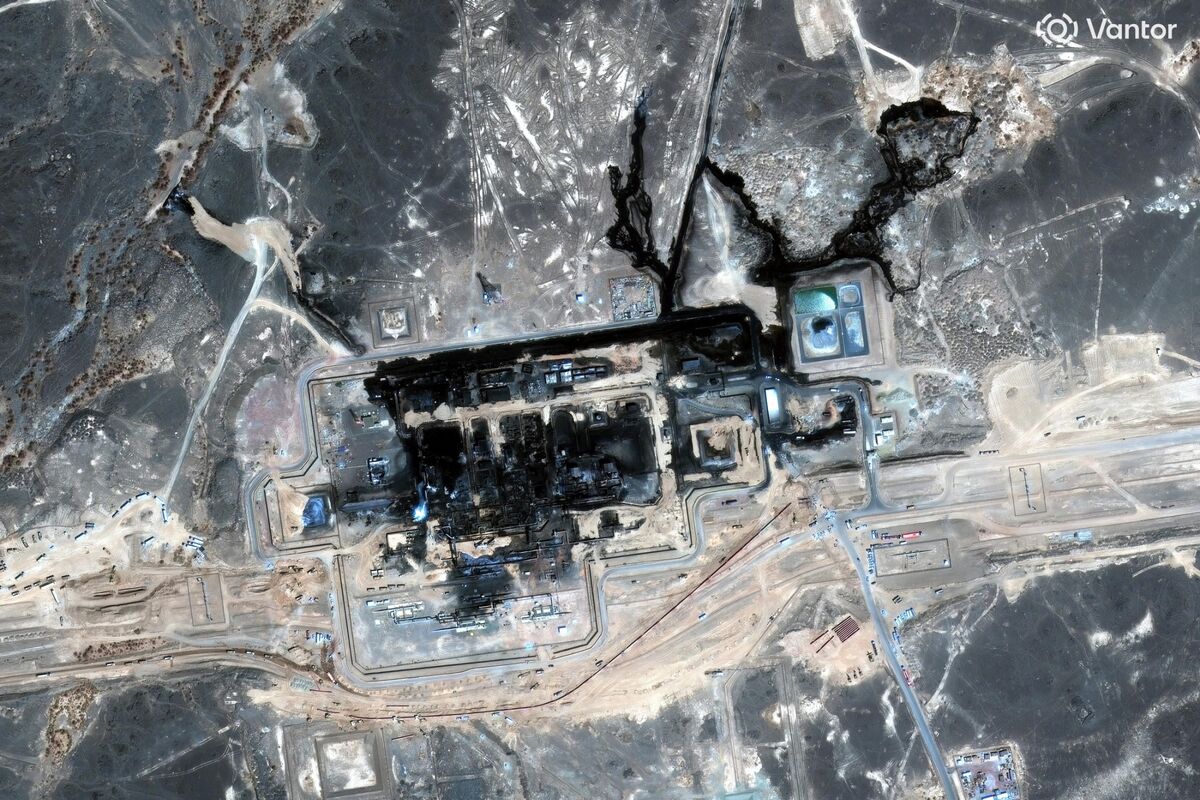
Middle East oil supply disruptions have fundamentally reshaped global shipping infrastructure and logistics costs for cross-border e-commerce sellers. According to maritime intelligence firm Kpler's September 2024 data, Middle East oil exports have rebounded to 92% of pre-war levels despite ongoing Iran-related tensions in the Strait of Hormuz. This recovery reflects three critical mechanisms: US military escort assistance (33% increase in vessel support August-September), shuttle tanker ship-to-ship transfer systems (60+ tankers moving 4+ million barrels daily), and pipeline diversification routing 40% of regional crude entirely around the strait.
The pipeline diversification represents the most significant structural shift for sellers. Saudi Arabia's East-West Pipeline now operates at full capacity, exporting 4+ million barrels daily to Red Sea terminals, while 25% of all Gulf crude routes through pipelines to Fujairah, UAE. This infrastructure shift directly impacts cross-border shipping costs: reduced Strait of Hormuz congestion and piracy risk lower marine insurance premiums (typically 0.5-2% of cargo value), while alternative routing through Red Sea and Gulf of Oman ports creates new logistics corridors. For sellers shipping electronics, apparel, and consumer goods from Asia to Europe/Middle East, these route changes translate to 3-8% reduction in freight costs and 5-10 day faster transit times compared to peak disruption periods.
However, sustainability concerns create pricing volatility for sellers. Iranian oil exports have collapsed to near-zero following July 2024 US naval blockade reimposition (down from 1.7 million barrels pre-war), with 20 empty Iran-flagged tankers stranded off Sri Lanka. Analysts question whether current measures can sustain amid escalation risks and potential US policy changes. This geopolitical uncertainty means shipping rates remain 12-18% above pre-conflict 2023 levels, and sellers should expect continued volatility through Q1 2025. Notably, liquified natural gas and processed oil product exports remain significantly depressed below pre-conflict volumes, indicating incomplete market recovery.
For cross-border sellers, the operational implication is clear: shipping cost stabilization is temporary and contingent on geopolitical stability. Sellers should lock in Q4 2024-Q1 2025 freight rates while pipeline routes remain operational, diversify shipping lanes away from Strait of Hormuz dependency (prioritizing Red Sea/Gulf of Oman routes), and monitor US policy changes that could disrupt current equilibrium. The "new normal" of pipeline-based exports creates 6-12 month window of relative cost stability before potential escalation.
Questions 7
What is the impact of Saudi Arabia's East-West Pipeline operating at full capacity?
Saudi Arabia's East-West Pipeline now exports 4+ million barrels daily to Red Sea terminals, with 25% of all Gulf crude routing through pipelines to Fujairah, UAE. This infrastructure shift creates new logistics corridors and reduces Strait of Hormuz dependency from 100% to approximately 60% of regional exports. For cross-border sellers, this means more predictable shipping routes, lower congestion-related delays, and reduced geopolitical risk premiums. The pipeline diversification represents the most significant structural adaptation, positioning it as the 'new normal' for Middle East oil exports through 2025.
How do Middle East oil supply disruptions affect cross-border seller shipping costs?
Middle East oil supply recovery to 92% of pre-war levels directly reduces shipping costs through two mechanisms: lower marine insurance premiums (0.5-2% of cargo value) due to reduced piracy risk in Strait of Hormuz, and faster transit times via alternative Red Sea/Gulf of Oman routes. Sellers shipping electronics and apparel from Asia to Europe/Middle East can expect 3-8% freight cost reduction and 5-10 day faster delivery compared to peak disruption periods. However, rates remain 12-18% above 2023 pre-conflict levels, indicating incomplete normalization. Sellers should lock in current rates while pipeline routes remain stable.