



Microsoft's $37.5B AI Spending Surge Signals Cloud Infrastructure Pressure for E-Commerce Sellers
- 66% capex increase outpaces Azure growth, raising cloud service costs and GPU supply constraints affecting seller operations through 2025

















Overview
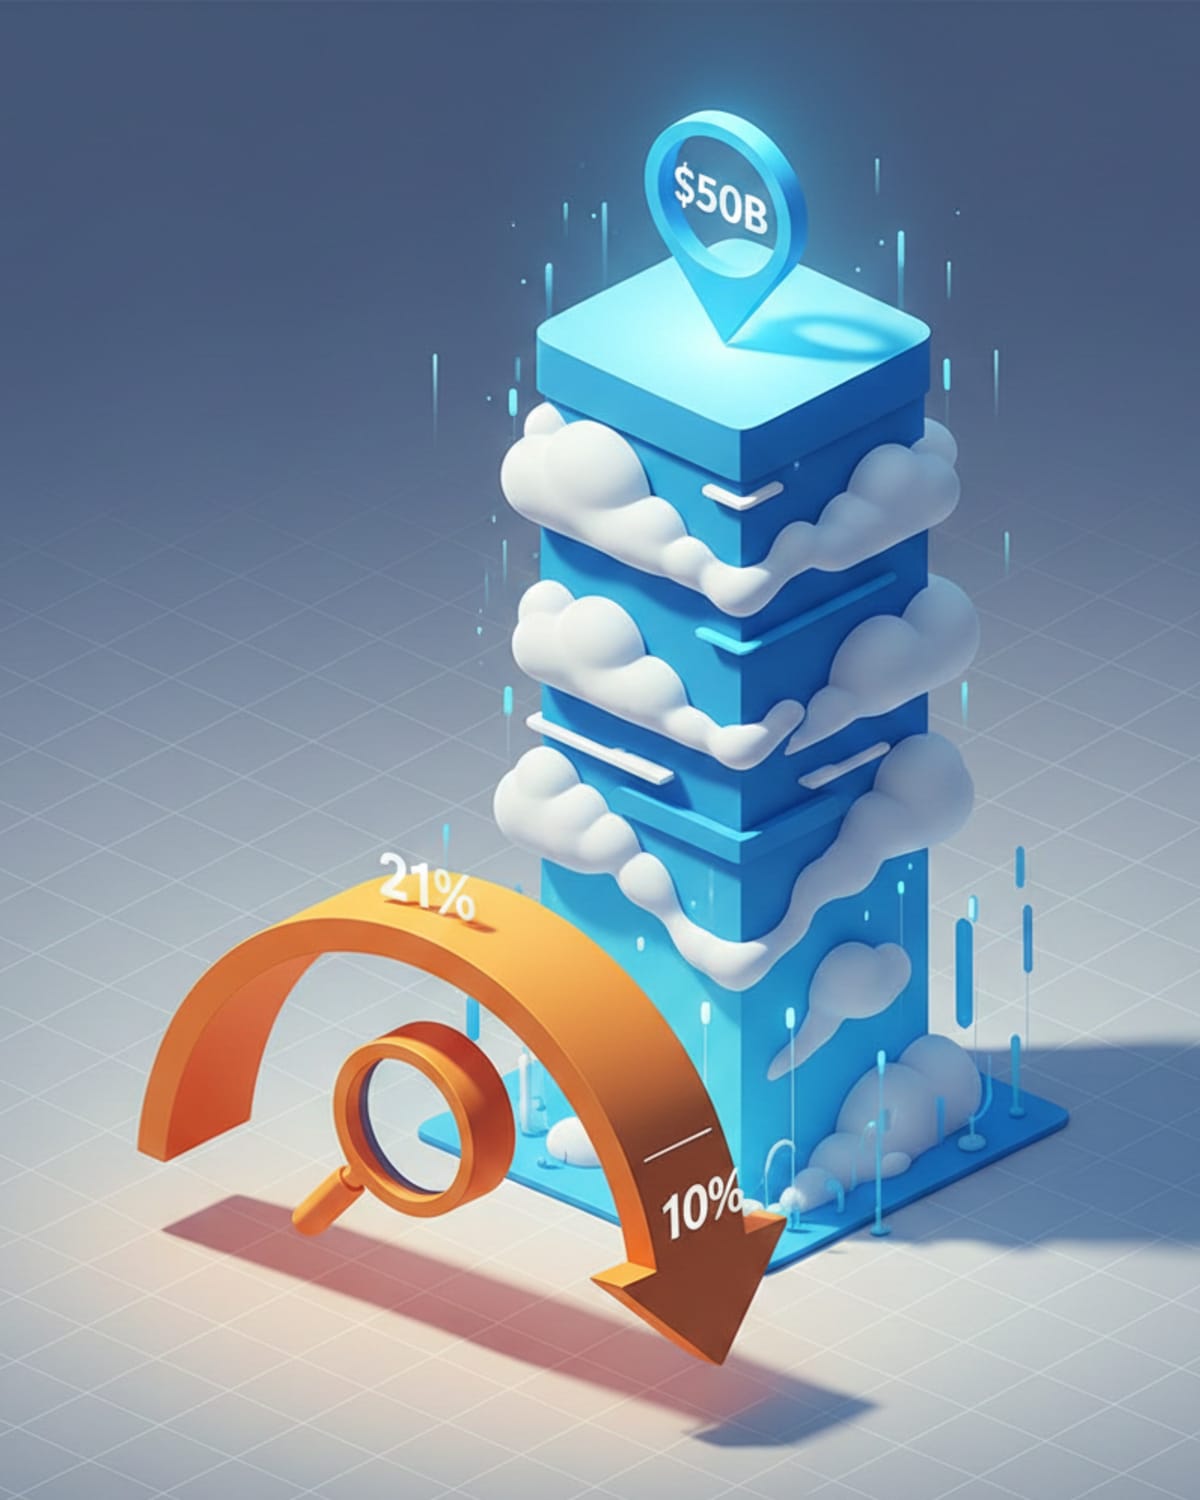
Microsoft's Q2 2025 earnings reveal a critical infrastructure investment paradox with direct implications for e-commerce sellers relying on cloud services. The company reported record $37.5 billion in artificial intelligence capital expenditure (66% year-over-year increase), with approximately two-thirds allocated to computing chips, yet Azure cloud revenue growth of only 38-39% barely exceeded analyst expectations of 36-38.8%. This disconnect between massive capex spending and modest revenue acceleration signals mounting pressure on cloud computing margins, as CFO Amy Hood warned that rising memory chip costs will increasingly compress margins throughout 2025.
For cross-border e-commerce sellers, this dynamic creates three operational risks. First, cloud service pricing pressure: Microsoft's $625 billion cloud backlog (45% dependent on OpenAI) and GPU supply constraints from Nvidia manufacturers force difficult resource allocation decisions. The company must choose between serving third-party cloud customers or reserving GPU capacity for internal Microsoft services, potentially limiting service availability and driving price increases for seller-dependent infrastructure. Second, competitive cloud market consolidation: Azure's 37-38% growth guidance for Q3 2025 (slightly below analyst expectations of 37%) reflects allocated capacity rather than maximum potential, indicating Microsoft is rationing resources. This contrasts with Amazon Web Services and Google Cloud, where investors perceive more favorable growth trajectories, potentially shifting competitive dynamics and pricing strategies across the cloud market. Third, infrastructure reliability concerns: Microsoft's margin compression (cost of revenues increased 19% while revenues grew only 17%) suggests the company may reduce investment in service reliability, feature development, and customer support—critical factors for sellers using Azure for backend operations, inventory management, analytics, and customer relationship management systems.
The broader context reveals industry-wide challenges in converting AI investments into sustainable revenue streams. Microsoft's situation mirrors challenges across hyperscalers, with investors now focused on capex efficiency rather than growth optics. For sellers, this means cloud service providers face pressure to demonstrate ROI, potentially leading to service consolidation, pricing restructuring, or reduced feature development. The $250 billion Azure commitment from OpenAI (following October 2024 restructuring) provides some revenue certainty, but OpenAI's newfound freedom to pursue alternative cloud partnerships reduces Microsoft's competitive moat. Additionally, competition from Google's Gemini and Anthropic's Claude autonomous agents poses risks to Microsoft's market position, potentially fragmenting cloud infrastructure investments across multiple providers.
E-commerce sellers should monitor three key indicators: (1) Azure pricing announcements in Q1-Q2 2025, as margin pressure typically translates to customer price increases within 60-90 days; (2) GPU availability metrics, as supply constraints may limit AI-powered seller tools (like M365 Copilot, which reached 15 million users at $30/month); (3) competitive cloud provider announcements, as AWS and Google Cloud may gain market share if they demonstrate superior capex-to-revenue ratios. Sellers heavily dependent on Microsoft cloud infrastructure should evaluate diversification strategies, including multi-cloud deployments or migration to alternative providers with stronger growth profiles.
Questions 8
How should sellers interpret Microsoft's Q3 2025 Azure growth guidance of 37-38%?
CFO Hood indicated this guidance represents allocated capacity rather than maximum potential growth, meaning Microsoft could grow faster if GPU supply permitted. This signals intentional resource rationing to preserve margins and manage costs. For sellers, this means: (1) Azure service availability may be constrained during peak demand periods; (2) new feature development may slow as resources are allocated to existing customers; (3) competitive pressure from AWS and Google Cloud will intensify as they capture growth Microsoft cannot serve. Sellers should treat 37-38% guidance as a ceiling, not a floor, and plan infrastructure accordingly.
What specific seller operations are most vulnerable to Microsoft's cloud infrastructure changes?
Sellers most vulnerable are those using Azure for: (1) real-time inventory management and order processing (compute-intensive); (2) machine learning-based demand forecasting (GPU-dependent); (3) customer analytics and CRM systems (storage-intensive); (4) cross-border logistics optimization (data transfer-heavy). These workloads face 8-15% cost increases if Azure pricing rises 5-12% and usage patterns remain constant. Sellers should audit current Azure spending by workload type by February 2025, prioritizing migration of non-critical AI workloads to alternative providers with stronger growth profiles and more stable pricing.