


Corporate Bitcoin Treasury Strategy Faces Valuation Pressure as Market Saturation and Copycat Competition Erode Premium Returns
- The "infinite money glitch" that powered MicroStrategy's Bitcoin accumulation model is breaking down as price volatility and competing corporate treasuries compress arbitrage opportunities for early movers





























































































































































Overview
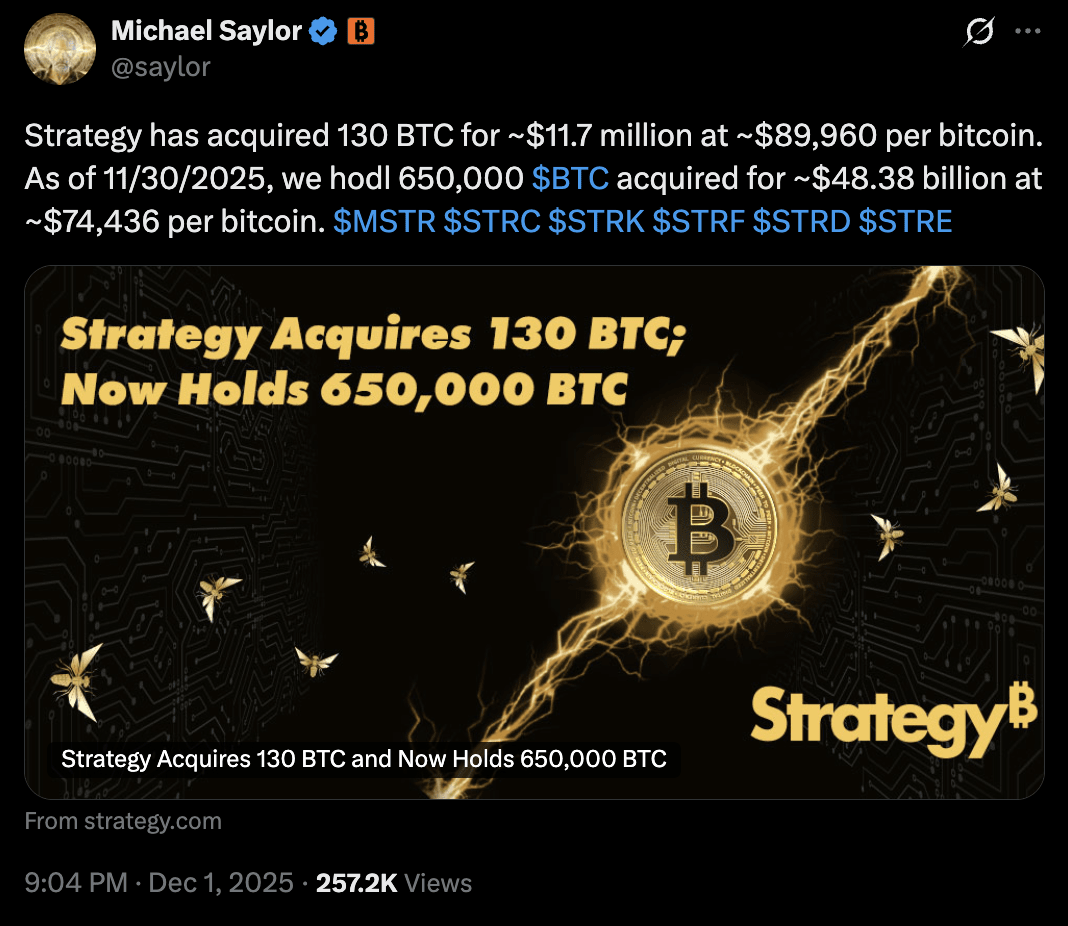
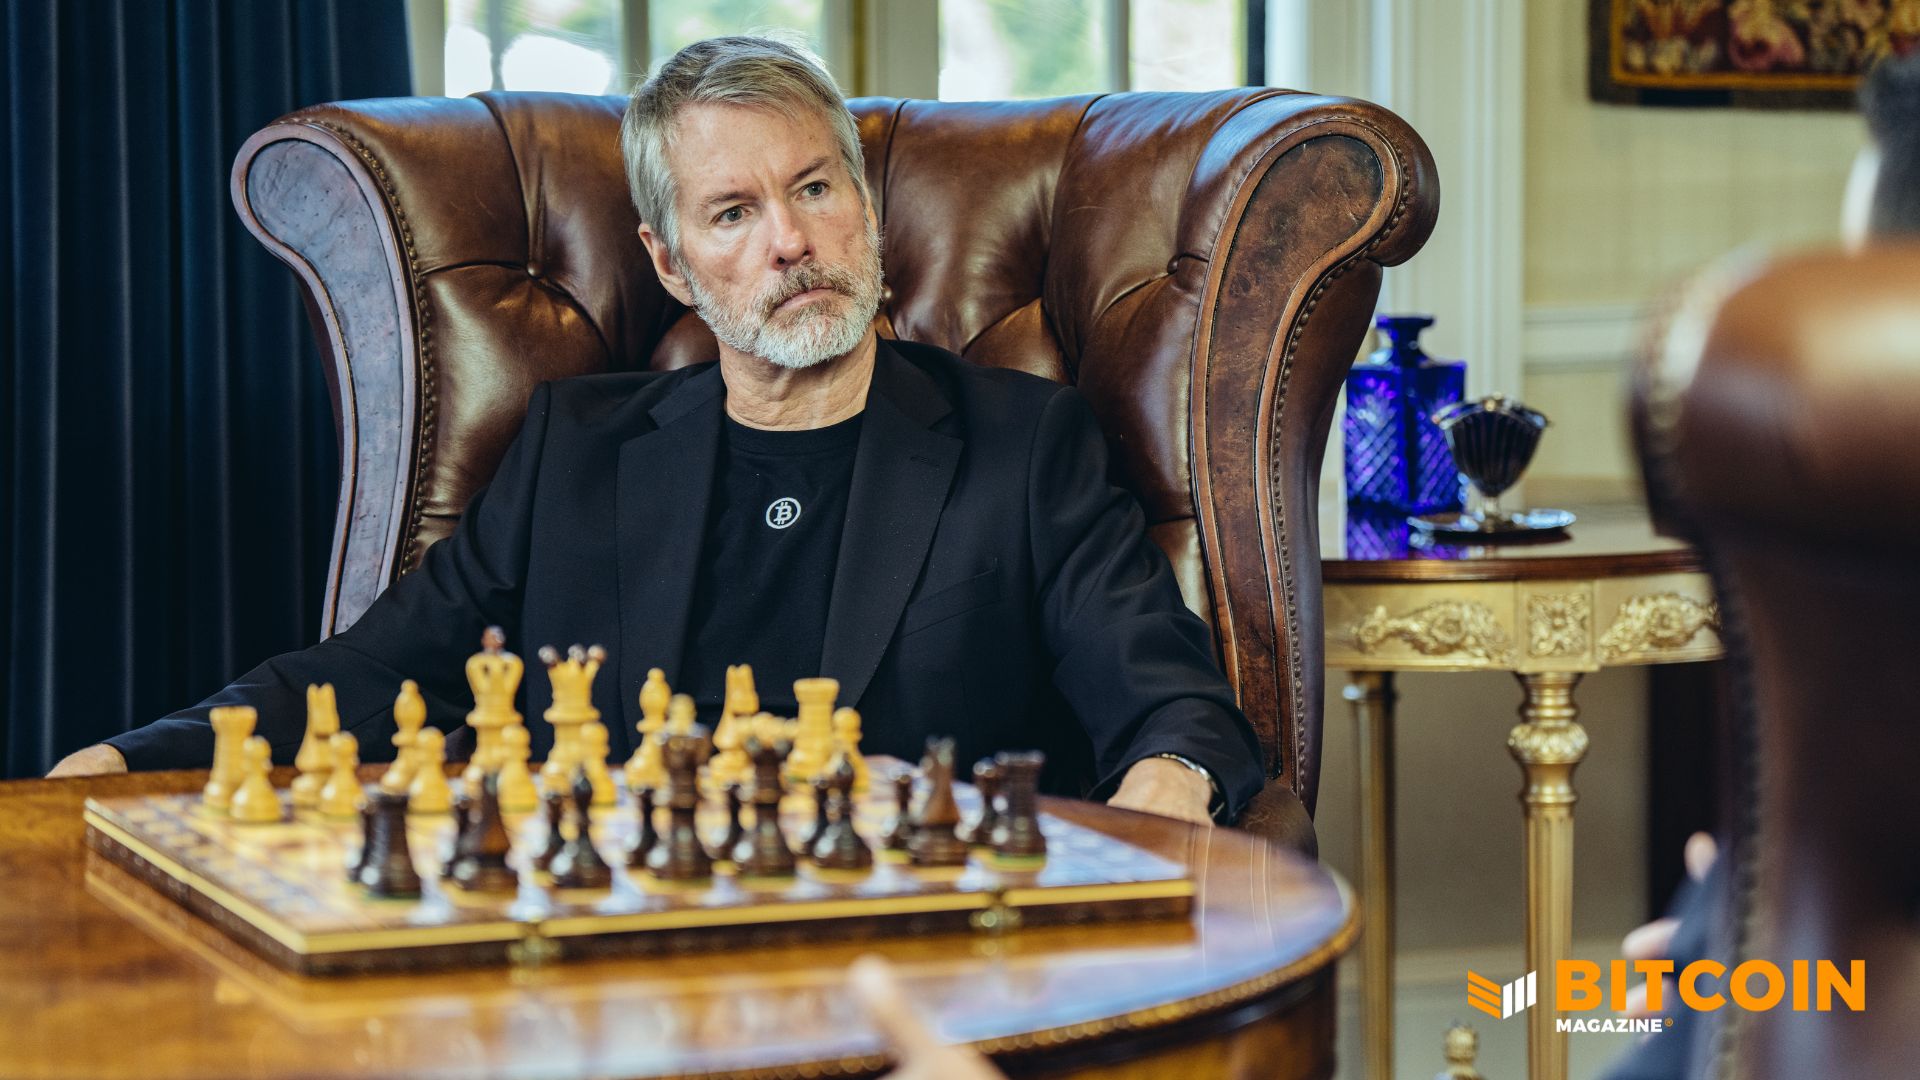
Michael Saylor's Bitcoin treasury strategy at MicroStrategy has fundamentally reshaped how corporations think about capital allocation and inflation hedging, but the model now faces critical stress as Bitcoin's price volatility and market saturation undermine the core thesis. The strategy's elegance was deceptively simple: raise capital at favorable terms, deploy it into Bitcoin, and benefit from the price appreciation that follows increased institutional buying pressure. With MicroStrategy holding 650,000 Bitcoin at an average cost basis of $74,000 per coin, the company's valuation premium depended entirely on Bitcoin appreciating beyond this threshold. However, with Bitcoin trading below $90,000—dangerously close to the break-even point—the narrative that sustained investor enthusiasm is fracturing.
What's particularly revealing is the speed at which this model has been replicated and commoditized. French entrepreneur Eric Larcheveque's new Bitcoin treasury company and numerous other imitators are now competing directly for the same capital and the same strategic positioning. This copycat competition is systematically eroding MicroStrategy's valuation premium, which was built on first-mover advantage and the perception of unique expertise. When a strategy becomes widely adopted, its arbitrage value collapses—and that's precisely what's happening in the corporate Bitcoin treasury space. The market is learning that there's nothing proprietary about buying Bitcoin with borrowed capital; the real risk lies in the execution and timing.
The underlying economic logic reveals why this model is now vulnerable. Corporate Bitcoin treasuries justified themselves as inflation hedges and alternatives to traditional capital reserves, positioning Bitcoin as a safer store of value than cash or bonds in a low-rate environment. But this narrative depends on sustained price appreciation and favorable financing conditions. As Bitcoin's price volatility increases and as more corporations compete for the same capital sources, the financing costs rise and the price appreciation becomes less certain. The "infinite money glitch"—the self-reinforcing cycle where buying pressure drives prices higher, attracting more capital, which drives prices higher still—is now malfunctioning. Market saturation means there are fewer new entrants to provide fresh buying pressure, and the existing players are increasingly indistinguishable from one another.
From a financial optimization perspective, this creates both risks and opportunities. For sellers and businesses exposed to corporate treasury dynamics, the compression of Bitcoin valuations signals a potential shift in how corporations will allocate capital going forward. If the premium returns from Bitcoin treasury strategies evaporate, corporations may redirect capital toward operational investments, supply chain financing, or working capital optimization—areas where fintech providers and payment platforms can capture value. Conversely, the volatility and uncertainty now surrounding corporate Bitcoin holdings may accelerate demand for FX hedging solutions and working capital financing products that help businesses stabilize cash flows independent of cryptocurrency exposure. The market is essentially repricing the risk of the Bitcoin treasury model, and that repricing will have cascading effects on corporate capital allocation decisions across multiple sectors.
Questions 5
What does the rise of competing Bitcoin treasury companies signal about the broader corporate capital allocation landscape?
It signals that the arbitrage opportunity in corporate Bitcoin treasuries is closing rapidly. When a strategy becomes widely replicated, its excess returns compress toward zero. For corporations and their financial partners, this suggests a shift away from speculative treasury strategies toward more fundamental capital allocation decisions—operational investments, supply chain financing, and working capital optimization. Fintech providers should expect increased demand for hedging solutions and working capital products as corporations seek to stabilize cash flows independent of cryptocurrency exposure.
Why is MicroStrategy's Bitcoin treasury strategy facing pressure now when it was so successful earlier?
The strategy's success depended on two factors: sustained Bitcoin price appreciation and first-mover advantage in corporate adoption. With Bitcoin trading near MicroStrategy's $74,000 average cost basis and numerous competitors now pursuing identical strategies, both conditions have deteriorated. The 'infinite money glitch'—where buying pressure drives prices higher—is breaking down as market saturation reduces new entrants and copycat competition commoditizes the approach. This means MicroStrategy's valuation premium, which was built on perceived uniqueness, is being systematically eroded.