



UK Political Accountability Crisis | Seller Trust & Compliance Implications
- Three-million-page DOJ document release exposes financial transparency gaps affecting cross-border seller confidence in government oversight and regulatory frameworks



Overview
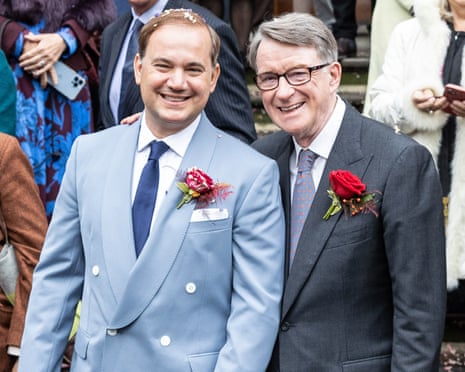
The release of over three million pages of Jeffrey Epstein files by the US Department of Justice represents a watershed moment in government transparency and financial accountability, with direct implications for cross-border e-commerce sellers operating under regulatory frameworks that depend on institutional trust. The documents reveal that convicted financier Jeffrey Epstein transferred £10,000 to Peter Mandelson's husband, Reinaldo Avila da Silva, in September 2009 for osteopathy course fees, with subsequent monthly payments of $2,000 beginning in April 2010. More significantly, the correspondence shows Mandelson—then serving as Business Secretary and de-facto Deputy Prime Minister—personally intervening to structure these transfers as loans to avoid gift-tax filing requirements, raising critical questions about how high-ranking government officials navigate financial disclosure obligations.
This transparency crisis directly impacts seller confidence in regulatory compliance frameworks. The Epstein files demonstrate that even senior government figures responsible for business regulation maintained undisclosed relationships with convicted offenders and structured financial arrangements to circumvent tax documentation. For cross-border sellers, this undermines confidence in the institutional oversight mechanisms they rely upon for fair competition and regulatory predictability. When government officials tasked with business oversight fail to disclose material relationships or structure transactions to avoid transparency requirements, sellers operating in multiple jurisdictions face increased uncertainty about which regulatory frameworks are genuinely enforced versus selectively applied. The three-million-page document release also signals that government financial transparency is reactive rather than proactive—requiring external pressure and congressional oversight to surface information that should have been disclosed during initial vetting processes.
The operational impact extends to seller risk assessment and compliance strategy. Sellers relying on government certifications, business licenses, or regulatory approvals from UK and US authorities now face questions about the integrity of those approval processes. The Mandelson case demonstrates that high-level officials can maintain undisclosed financial relationships for years (2009-2016 contact documented) without triggering disclosure mechanisms. For sellers managing cross-border compliance, this suggests that regulatory frameworks may contain significant blind spots regarding beneficial ownership, financial relationships, and conflict-of-interest disclosures. Additionally, the political fallout—Mandelson's removal as UK Ambassador to the US in September 2024 after 15 years of undisclosed contact—indicates that government accountability mechanisms operate on multi-year delays, creating extended periods where sellers may be operating under guidance from officials with undisclosed conflicts. The broader implication: sellers should assume that government regulatory frameworks contain information asymmetries and should implement independent compliance verification rather than relying solely on official certifications.
Questions 8
How does this case affect seller trust in government-issued business certifications?
The Epstein files demonstrate that government officials responsible for business oversight maintained undisclosed relationships with convicted offenders while issuing business guidance and regulatory approvals. For sellers, this indicates that government certifications and approvals may be issued by officials with undisclosed conflicts of interest that could affect the quality or impartiality of those certifications. The 15-year delay in surfacing the relationship suggests that sellers may be operating under certifications from officials whose conflicts weren't disclosed at the time of certification. Sellers should treat government certifications as one input among many rather than definitive proof of compliance, maintain independent verification of regulatory requirements, and monitor for retroactive changes in regulatory guidance that might result from disclosed official conflicts.
What are the broader implications for cross-border seller confidence in multi-jurisdiction regulatory frameworks?
The case demonstrates that regulatory frameworks in multiple jurisdictions (UK and US) can contain significant blind spots regarding official conflicts and undisclosed relationships, with accountability mechanisms operating on multi-year delays. For cross-border sellers, this indicates that regulatory predictability and consistency may be lower than assumed, as frameworks can change retroactively when undisclosed conflicts surface. The political fallout affecting a senior government official suggests that regulatory frameworks are vulnerable to sudden shifts when transparency crises occur. Sellers should: (1) Diversify regulatory guidance sources across jurisdictions, (2) Assume that current frameworks may contain information asymmetries, (3) Maintain compliance flexibility to adapt to retroactive regulatory changes, (4) Monitor political developments that might affect regulatory officials' credibility, (5) Build compliance buffers beyond minimum requirements to protect against sudden framework changes.