)


)
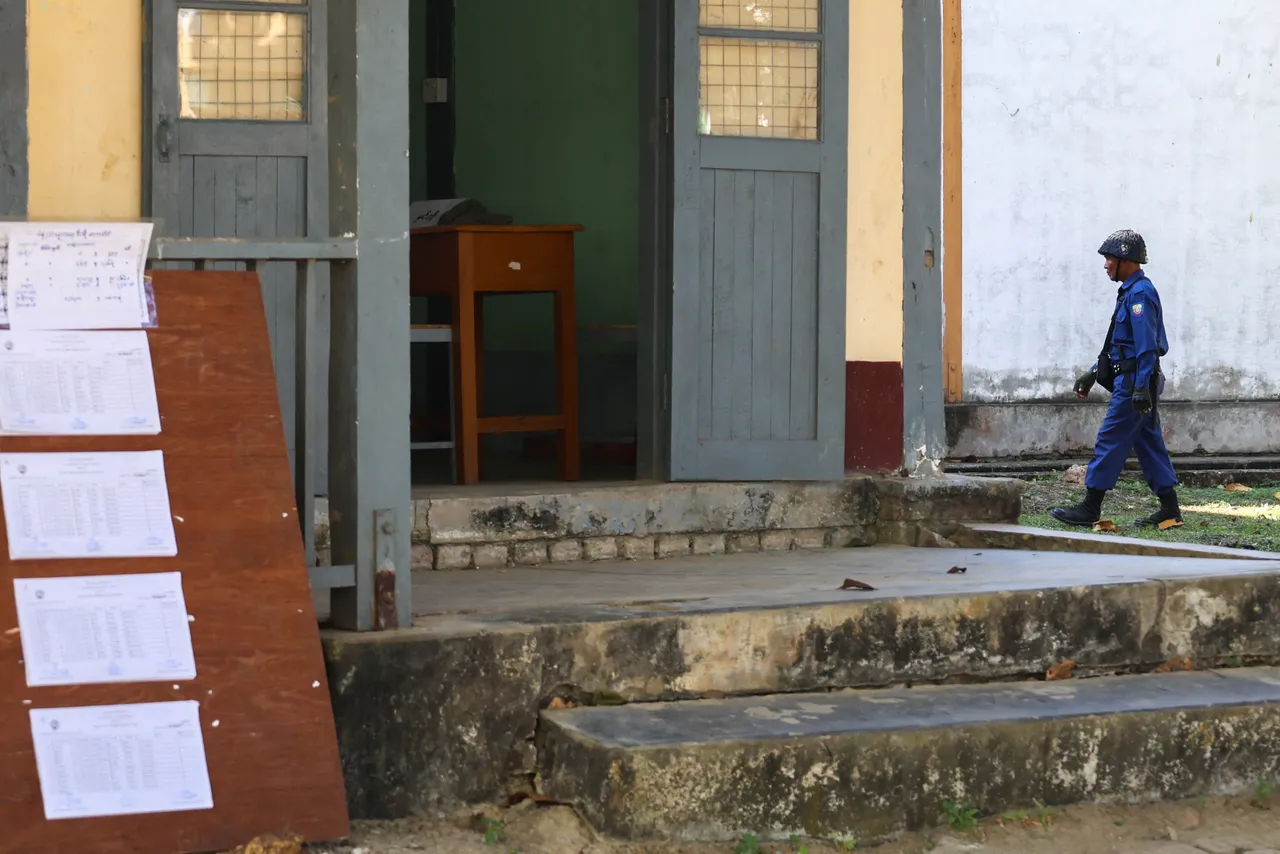
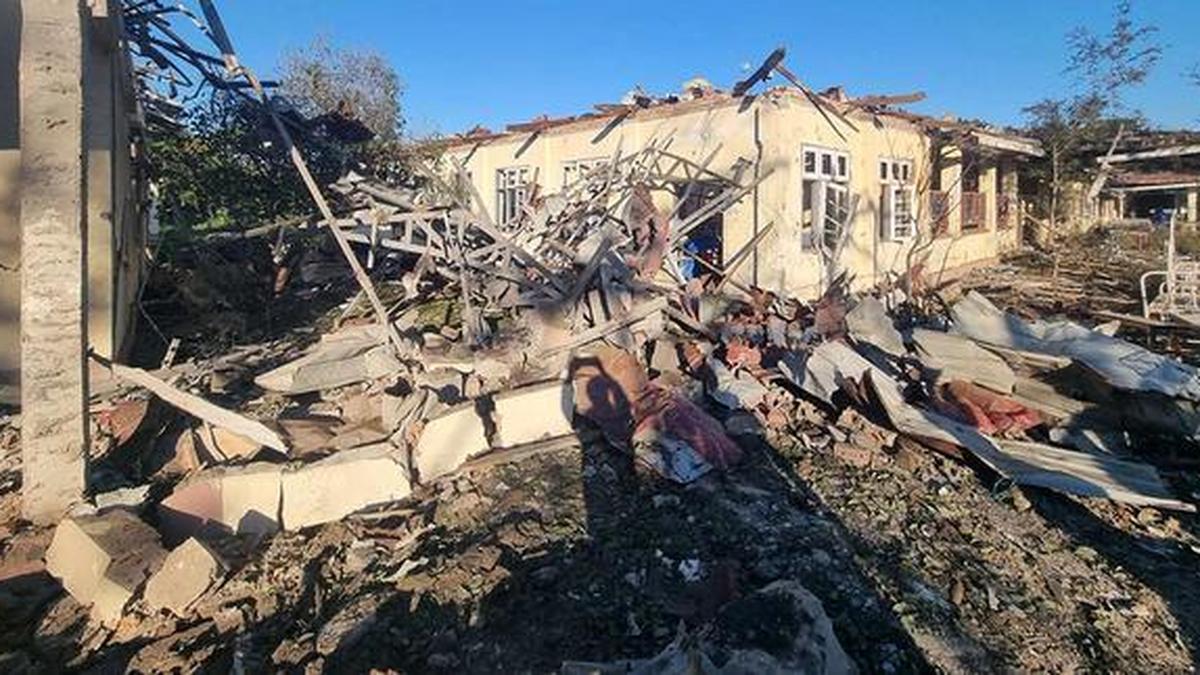
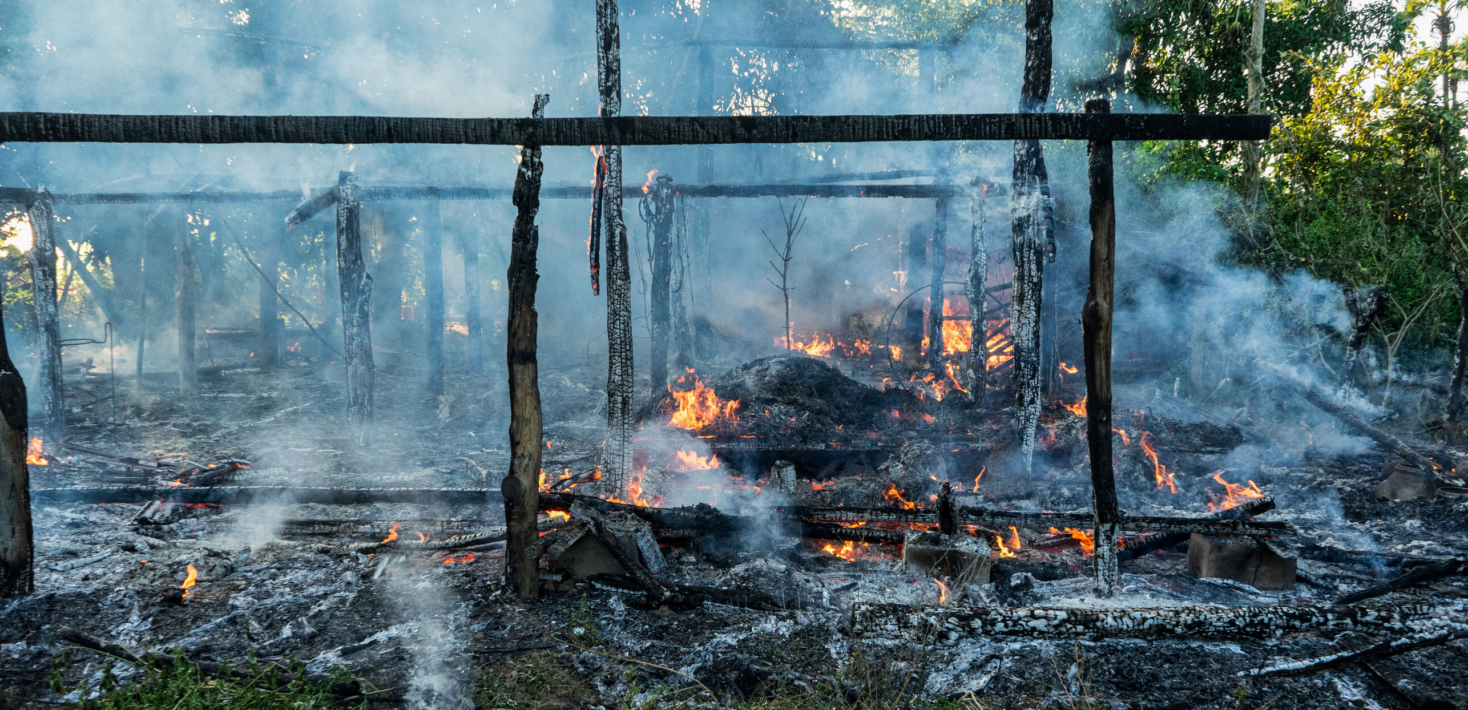
Myanmar's political and military crisis represents a critical supply chain disruption event for cross-border e-commerce sellers, particularly those sourcing from or shipping through Southeast Asia. The UN documented 170+ civilian deaths during December 2025-January 2026 military airstrikes coinciding with disputed elections, with 408 aerial attacks recorded across regions including manufacturing hubs in Bago, Magwe, Mandalay, and Sagaing. This escalation signals deepening instability that directly threatens e-commerce logistics infrastructure: Kyaukphyu port—Myanmar's primary deep-water facility handling regional container traffic—faces operational uncertainty due to Arakan Army control of Rakhine State's western seaboard. The military junta's conscription of 90,000+ draftees since early 2024 (targeting 240,000 total) has depleted manufacturing labor pools and disrupted production timelines for sellers relying on Myanmar-based suppliers.
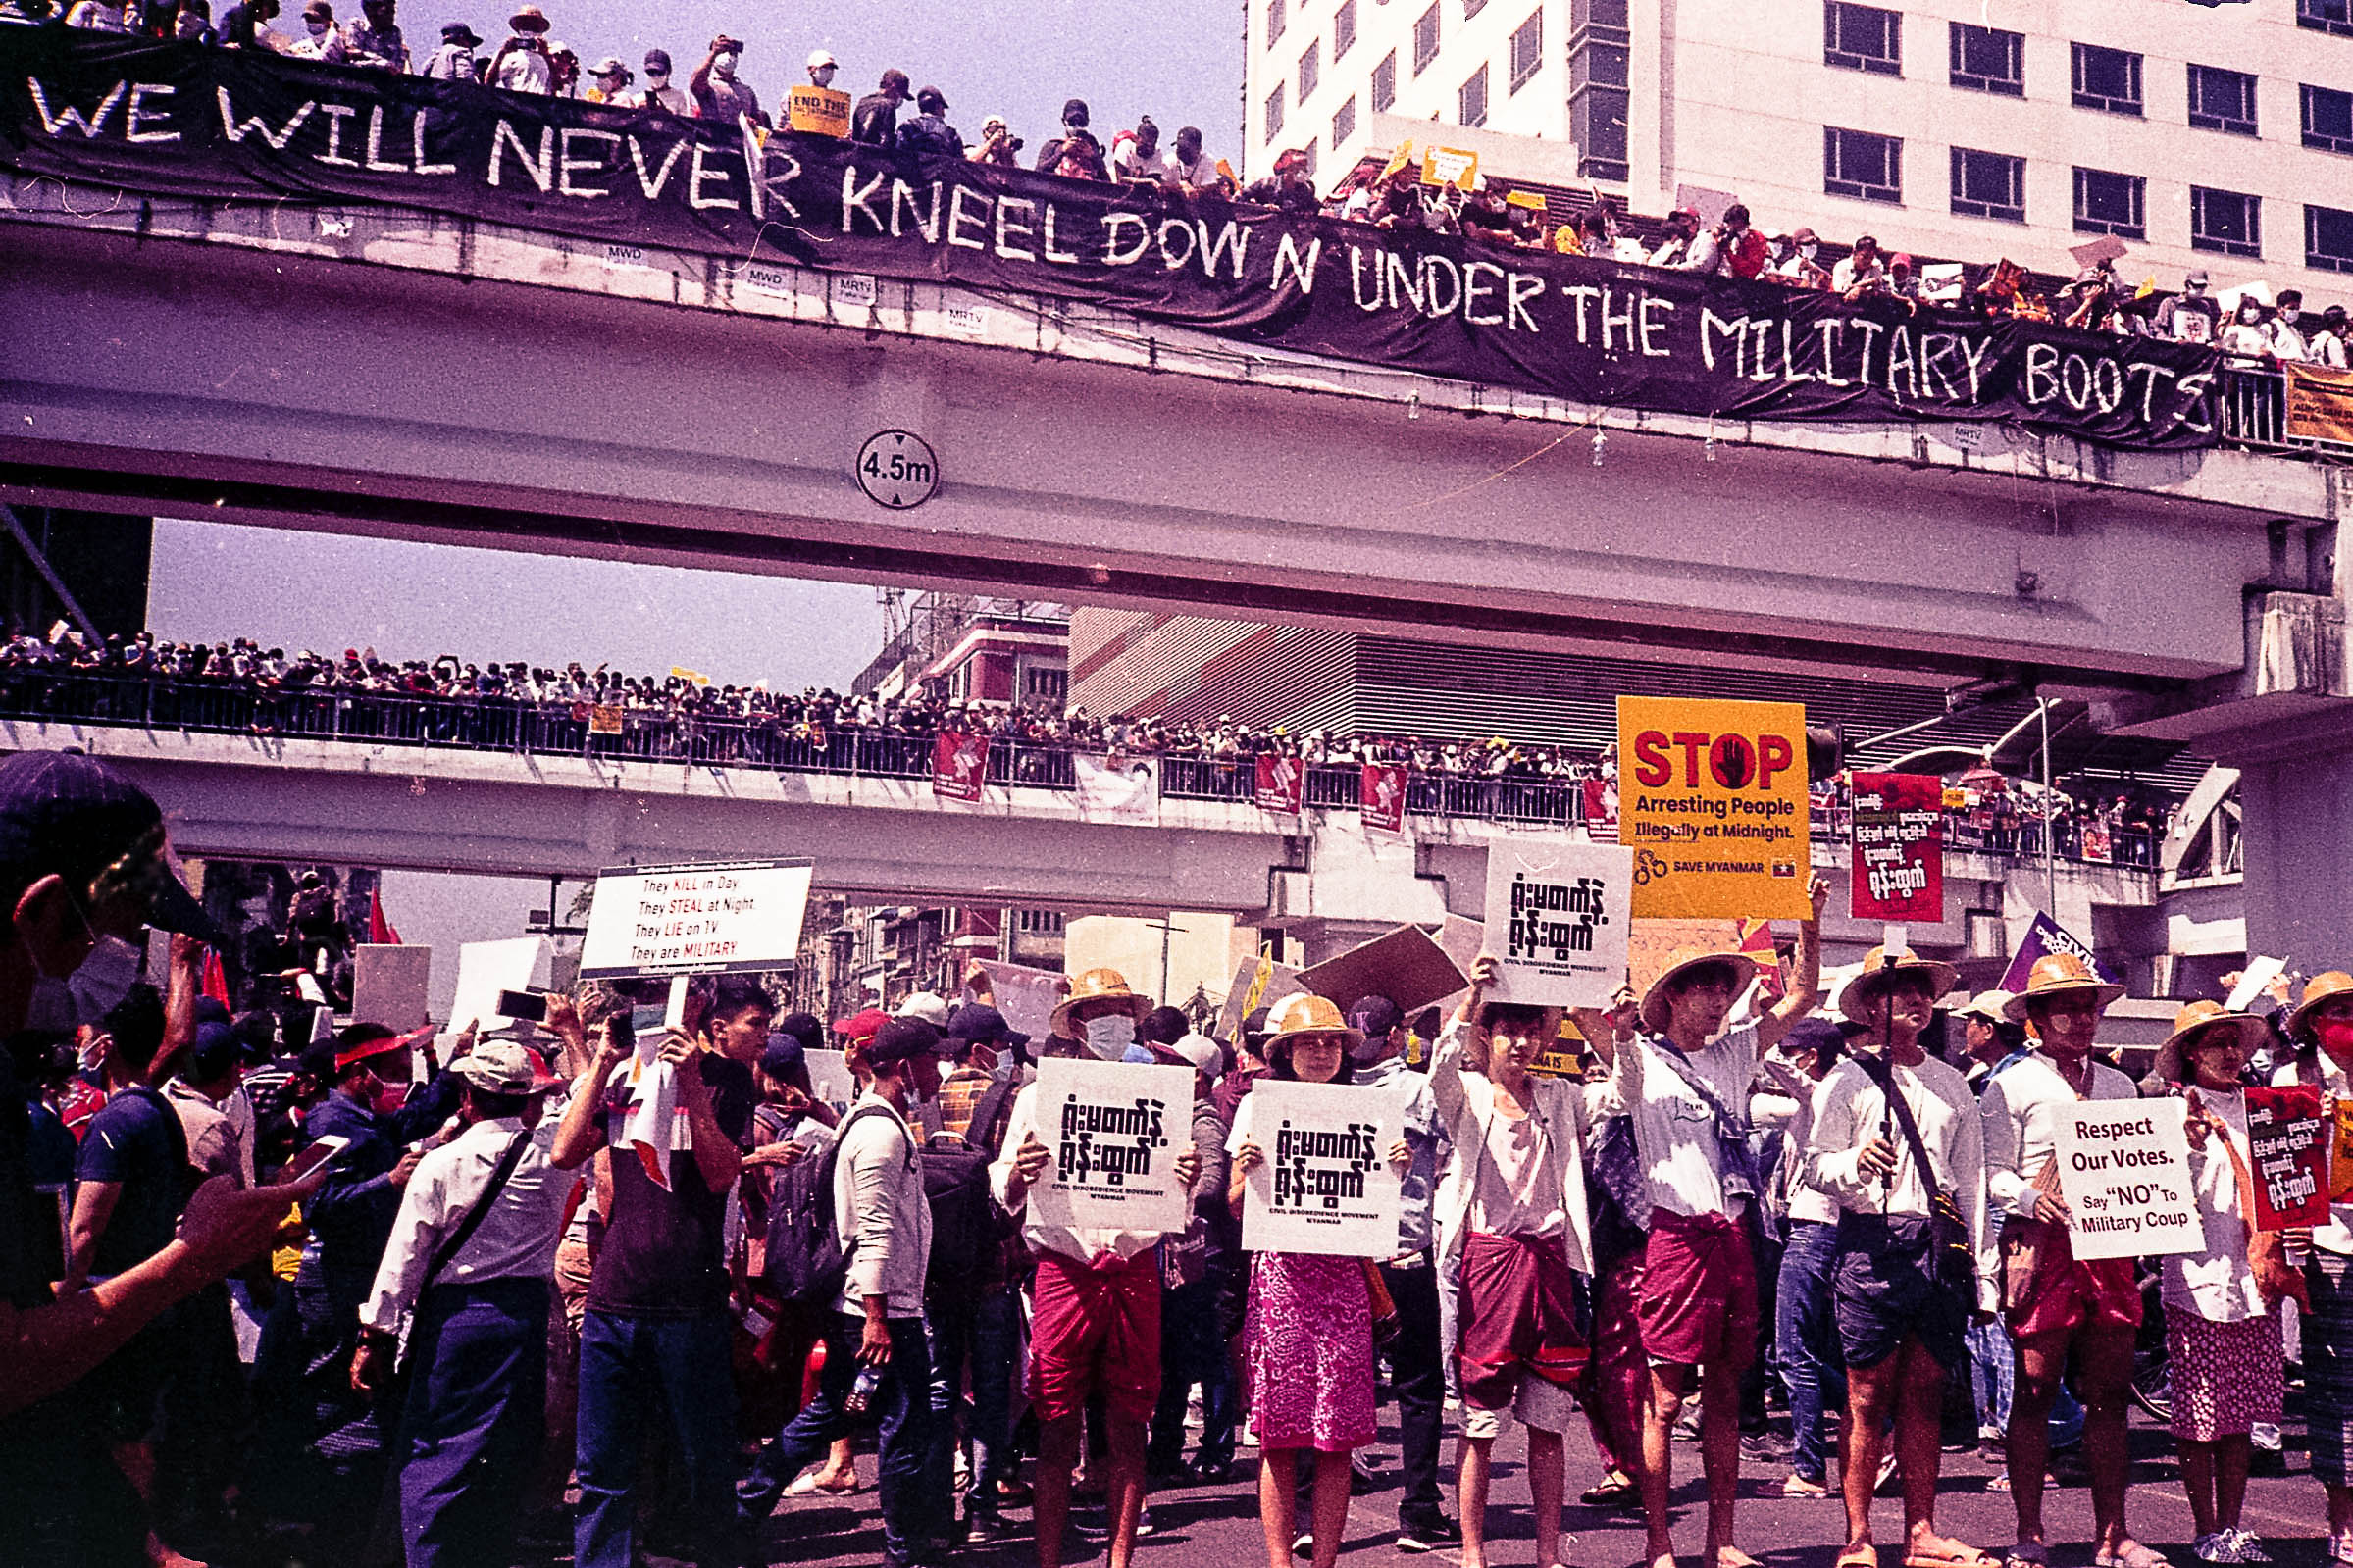
Supply Chain Impact: Sellers sourcing textiles, electronics components, or agricultural products from Myanmar face 40-60% increases in logistics costs due to route diversification around conflict zones. Communication blackouts documented by the UN prevent real-time supply chain visibility, creating inventory forecasting challenges. The military's control of only 263 of 330 townships means large geographic areas remain inaccessible for business operations, effectively fragmenting Myanmar's market into isolated urban enclaves. For sellers with 3PL operations or fulfillment centers in Myanmar, regulatory uncertainty compounds operational risk—the military junta's "staged election" (per UN characterization) signals continued authoritarian control with unpredictable policy changes affecting business licensing, tax compliance, and customs procedures.
Regional Spillover Effects: The conflict's trajectory toward a "tipping point in 2026" (per Asia Times analysis) threatens broader Southeast Asian stability. Ethnic minority forces controlling Rakhine State and Kachin regions may disrupt cross-border trade routes to Thailand, Laos, and China. Malaysia's new protectionist cooking oil ban (effective March 1st, 2026) reflects regional governments' inward focus during geopolitical uncertainty, signaling potential for additional trade restrictions affecting sellers' supply chain flexibility. Sellers should anticipate 3-6 month delays for Myanmar-sourced inventory, increased insurance premiums for regional shipments, and potential need to shift sourcing to alternative Southeast Asian suppliers (Vietnam, Thailand, Indonesia) at 15-25% cost premiums.
Myanmar's communication blackouts and conflict-driven logistics delays create severe inventory forecasting challenges. The UN documented severed communications preventing accurate casualty reporting; similar blackouts affect supply chain visibility. Sellers should increase safety stock by 30-40% for Myanmar-sourced products, extending lead times from typical 30-45 days to 60-90 days. Implement scenario planning: assume 25% of Myanmar suppliers become inaccessible; model 40-60% cost increases for alternative sourcing; plan for 3-6 month delays on critical inventory. Use demand forecasting software with conflict-risk adjustments; establish supplier redundancy across Vietnam, Thailand, and Indonesia; negotiate flexible payment terms allowing inventory adjustments. Monitor UN humanitarian reports and Asia Times conflict analysis for escalation signals indicating need for emergency sourcing pivots.
Myanmar's escalating conflict creates severe supply chain disruptions for sellers sourcing textiles, electronics, or agricultural products. The UN documented 408 military airstrikes across manufacturing regions (Bago, Magwe, Mandalay, Sagaing) during December 2025-January 2026, with 90,000+ conscripted troops depleting factory labor. Sellers face 40-60% logistics cost increases due to route diversification around conflict zones, 3-6 month inventory delays, and communication blackouts preventing real-time tracking. The military's control of only 263 of 330 townships fragments Myanmar's market, making supplier access unpredictable. Immediate action: diversify sourcing to Vietnam, Thailand, or Indonesia; increase safety stock by 30-40%; negotiate force majeure clauses with Myanmar suppliers.
Sellers diversifying from Myanmar to alternative Southeast Asian suppliers (Vietnam, Thailand, Indonesia) face 15-25% cost premiums due to higher labor rates and manufacturing overhead. However, these costs must be weighed against Myanmar supply chain risks: 40-60% logistics cost increases, 3-6 month delays, and regulatory uncertainty. Cost-benefit analysis: Myanmar sourcing at baseline cost + 40-60% logistics premium + 3-6 month working capital carrying costs typically exceeds alternative sourcing at 15-25% premium with reliable 30-45 day lead times. Sellers should: calculate total landed cost including financing costs for extended lead times; evaluate Vietnam for electronics/textiles (10-15% premium), Thailand for agricultural products (12-18% premium), Indonesia for consumer goods (15-20% premium); negotiate volume commitments for cost reductions; consider nearshoring to reduce logistics complexity.
Myanmar's conflict escalation and regional tensions (China Coast Guard patrols near Japan-held islands) increase insurance premiums and risk management costs for cross-border sellers. Sellers should expect: 15-20% increases in freight insurance for Southeast Asian shipments, 10-15% increases in political risk insurance for Myanmar operations, and potential policy exclusions for conflict-affected regions. The UN's documentation of 408 military airstrikes signals elevated risk for air freight routing through Myanmar airspace. Sellers should: audit current insurance policies for Myanmar/conflict zone exclusions; increase political risk coverage for regional operations; diversify shipping routes away from conflict zones; establish force majeure protocols with suppliers and customers; maintain 60-90 day cash reserves for unexpected disruptions; consider supply chain resilience consulting to identify vulnerabilities.
Asia Times analysis identifies 2026 as a 'tipping point' for Myanmar conflict, suggesting accelerating escalation through mid-2026. Sellers should implement contingency planning on three timelines: Immediate (0-30 days): audit Myanmar supplier relationships, evaluate Kyaukphyu port dependency, increase safety stock by 20%; Short-term (1-3 months): diversify sourcing to Vietnam/Thailand/Indonesia, establish backup 3PL providers, negotiate flexible supplier contracts; Medium-term (3-6 months): relocate fulfillment operations if Myanmar-based, implement supply chain visibility software, establish regional supplier redundancy. The military's conscription program (90,000+ troops) and planned offensives against ethnic forces suggest conflict intensification through Q2-Q3 2026. Sellers should monitor UN humanitarian reports monthly and Asia Times conflict analysis quarterly for escalation signals requiring emergency sourcing pivots.
Kyaukphyu is Myanmar's primary deep-water port handling regional container traffic for Southeast Asian cross-border commerce. The Arakan Army's control of Rakhine State's western seaboard threatens port access, creating uncertainty for sellers shipping through Myanmar. The conflict's trajectory toward escalation in 2026 signals potential port closures or operational delays. Sellers relying on Kyaukphyu for inbound inventory or outbound shipments should: evaluate alternative ports (Bangkok, Singapore, Ho Chi Minh City) with 5-7 day transit delays; increase freight insurance by 15-20%; establish backup 3PL providers in Thailand or Vietnam. Port disruptions typically add $500-1,500 per container in rerouting costs.
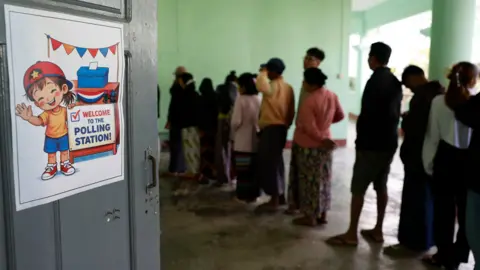
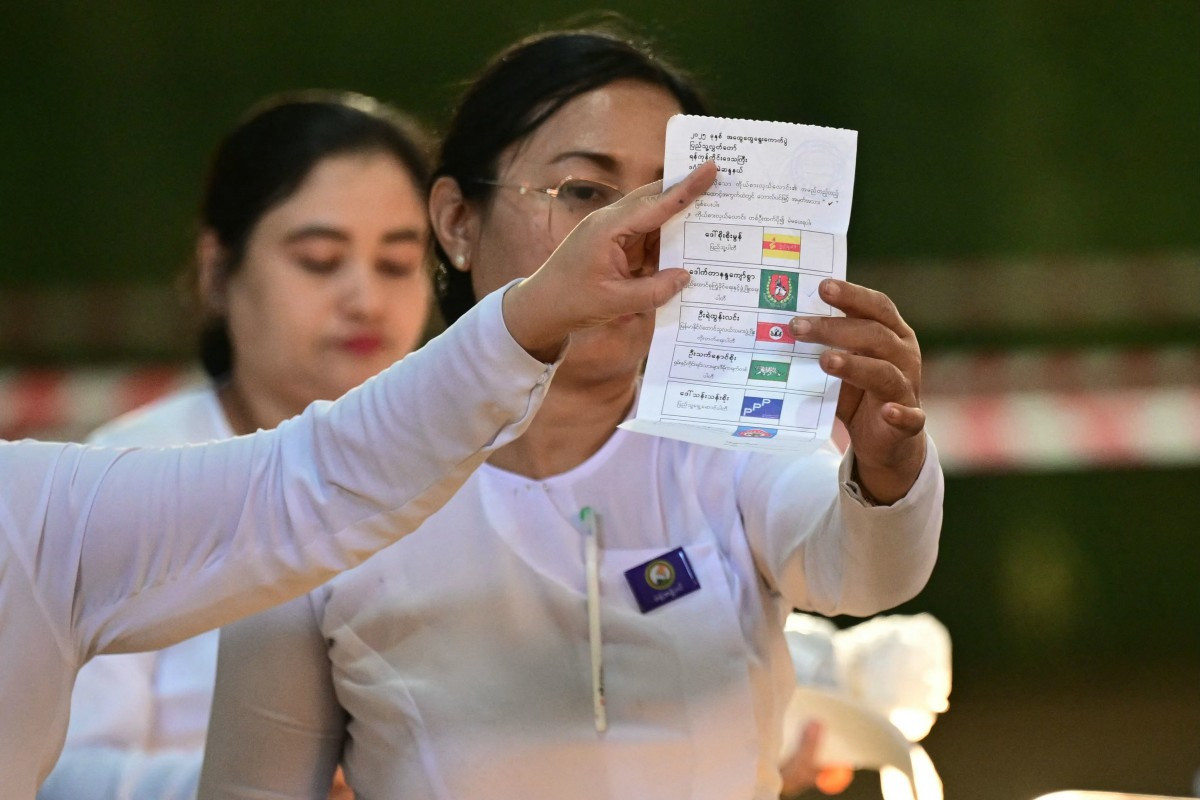
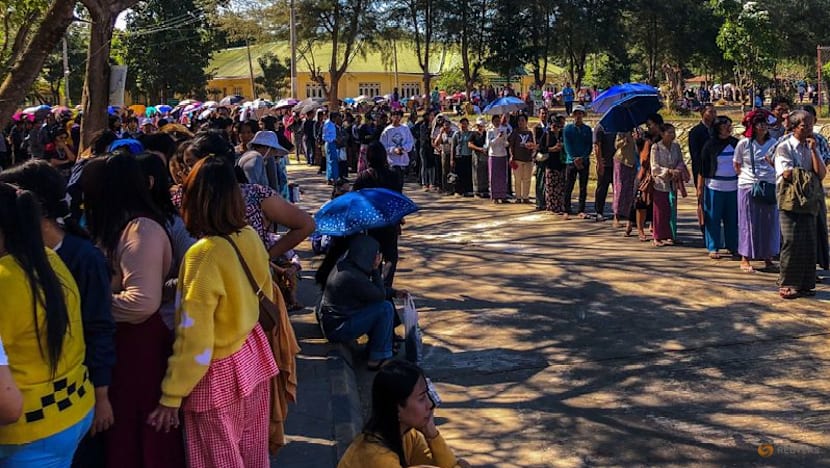
The UN characterized Myanmar's December 2025-January 2026 election as 'staged by the military,' signaling continued authoritarian control with unpredictable policy changes. The military junta's consolidation of power through proxy political parties (USDP) suggests regulatory uncertainty for foreign business operations. Sellers with Myanmar-based fulfillment centers or supplier relationships face risks including: sudden licensing requirement changes, tax compliance shifts, customs procedure modifications, and potential restrictions on foreign business activities. The military's documented pattern of 'political repression, mass arbitrary arrests, and surveillance' creates compliance risk. Sellers should: audit Myanmar business registrations for regulatory exposure; establish contingency plans for license revocation; consider relocating fulfillment operations to Thailand or Vietnam; maintain 60-90 day cash reserves for operational disruptions.
Malaysia implemented a ban on foreigners purchasing subsidized cooking oil effective March 1st, 2026, representing a protectionist measure reflecting regional governments' inward focus during geopolitical uncertainty. This signals potential for additional trade restrictions affecting sellers' supply chain flexibility in Southeast Asia. Sellers sourcing or distributing cooking oil products in Malaysia face: restricted access to subsidized inventory, pricing disadvantages versus local competitors, and potential customs complications. The ban reflects broader regional trend toward protectionism during Myanmar conflict escalation. Sellers should: evaluate alternative sourcing from Thailand or Indonesia; adjust pricing strategies for non-subsidized oil; monitor for similar restrictions in other Southeast Asian markets; diversify product sourcing across multiple countries to reduce single-market dependency.
Myanmar's communication blackouts and conflict-driven logistics delays create severe inventory forecasting challenges. The UN documented severed communications preventing accurate casualty reporting; similar blackouts affect supply chain visibility. Sellers should increase safety stock by 30-40% for Myanmar-sourced products, extending lead times from typical 30-45 days to 60-90 days. Implement scenario planning: assume 25% of Myanmar suppliers become inaccessible; model 40-60% cost increases for alternative sourcing; plan for 3-6 month delays on critical inventory. Use demand forecasting software with conflict-risk adjustments; establish supplier redundancy across Vietnam, Thailand, and Indonesia; negotiate flexible payment terms allowing inventory adjustments. Monitor UN humanitarian reports and Asia Times conflict analysis for escalation signals indicating need for emergency sourcing pivots.
Myanmar's escalating conflict creates severe supply chain disruptions for sellers sourcing textiles, electronics, or agricultural products. The UN documented 408 military airstrikes across manufacturing regions (Bago, Magwe, Mandalay, Sagaing) during December 2025-January 2026, with 90,000+ conscripted troops depleting factory labor. Sellers face 40-60% logistics cost increases due to route diversification around conflict zones, 3-6 month inventory delays, and communication blackouts preventing real-time tracking. The military's control of only 263 of 330 townships fragments Myanmar's market, making supplier access unpredictable. Immediate action: diversify sourcing to Vietnam, Thailand, or Indonesia; increase safety stock by 30-40%; negotiate force majeure clauses with Myanmar suppliers.
Sellers diversifying from Myanmar to alternative Southeast Asian suppliers (Vietnam, Thailand, Indonesia) face 15-25% cost premiums due to higher labor rates and manufacturing overhead. However, these costs must be weighed against Myanmar supply chain risks: 40-60% logistics cost increases, 3-6 month delays, and regulatory uncertainty. Cost-benefit analysis: Myanmar sourcing at baseline cost + 40-60% logistics premium + 3-6 month working capital carrying costs typically exceeds alternative sourcing at 15-25% premium with reliable 30-45 day lead times. Sellers should: calculate total landed cost including financing costs for extended lead times; evaluate Vietnam for electronics/textiles (10-15% premium), Thailand for agricultural products (12-18% premium), Indonesia for consumer goods (15-20% premium); negotiate volume commitments for cost reductions; consider nearshoring to reduce logistics complexity.
Myanmar's conflict escalation and regional tensions (China Coast Guard patrols near Japan-held islands) increase insurance premiums and risk management costs for cross-border sellers. Sellers should expect: 15-20% increases in freight insurance for Southeast Asian shipments, 10-15% increases in political risk insurance for Myanmar operations, and potential policy exclusions for conflict-affected regions. The UN's documentation of 408 military airstrikes signals elevated risk for air freight routing through Myanmar airspace. Sellers should: audit current insurance policies for Myanmar/conflict zone exclusions; increase political risk coverage for regional operations; diversify shipping routes away from conflict zones; establish force majeure protocols with suppliers and customers; maintain 60-90 day cash reserves for unexpected disruptions; consider supply chain resilience consulting to identify vulnerabilities.
Asia Times analysis identifies 2026 as a 'tipping point' for Myanmar conflict, suggesting accelerating escalation through mid-2026. Sellers should implement contingency planning on three timelines: Immediate (0-30 days): audit Myanmar supplier relationships, evaluate Kyaukphyu port dependency, increase safety stock by 20%; Short-term (1-3 months): diversify sourcing to Vietnam/Thailand/Indonesia, establish backup 3PL providers, negotiate flexible supplier contracts; Medium-term (3-6 months): relocate fulfillment operations if Myanmar-based, implement supply chain visibility software, establish regional supplier redundancy. The military's conscription program (90,000+ troops) and planned offensives against ethnic forces suggest conflict intensification through Q2-Q3 2026. Sellers should monitor UN humanitarian reports monthly and Asia Times conflict analysis quarterly for escalation signals requiring emergency sourcing pivots.
Kyaukphyu is Myanmar's primary deep-water port handling regional container traffic for Southeast Asian cross-border commerce. The Arakan Army's control of Rakhine State's western seaboard threatens port access, creating uncertainty for sellers shipping through Myanmar. The conflict's trajectory toward escalation in 2026 signals potential port closures or operational delays. Sellers relying on Kyaukphyu for inbound inventory or outbound shipments should: evaluate alternative ports (Bangkok, Singapore, Ho Chi Minh City) with 5-7 day transit delays; increase freight insurance by 15-20%; establish backup 3PL providers in Thailand or Vietnam. Port disruptions typically add $500-1,500 per container in rerouting costs.
The UN characterized Myanmar's December 2025-January 2026 election as 'staged by the military,' signaling continued authoritarian control with unpredictable policy changes. The military junta's consolidation of power through proxy political parties (USDP) suggests regulatory uncertainty for foreign business operations. Sellers with Myanmar-based fulfillment centers or supplier relationships face risks including: sudden licensing requirement changes, tax compliance shifts, customs procedure modifications, and potential restrictions on foreign business activities. The military's documented pattern of 'political repression, mass arbitrary arrests, and surveillance' creates compliance risk. Sellers should: audit Myanmar business registrations for regulatory exposure; establish contingency plans for license revocation; consider relocating fulfillment operations to Thailand or Vietnam; maintain 60-90 day cash reserves for operational disruptions.
Malaysia implemented a ban on foreigners purchasing subsidized cooking oil effective March 1st, 2026, representing a protectionist measure reflecting regional governments' inward focus during geopolitical uncertainty. This signals potential for additional trade restrictions affecting sellers' supply chain flexibility in Southeast Asia. Sellers sourcing or distributing cooking oil products in Malaysia face: restricted access to subsidized inventory, pricing disadvantages versus local competitors, and potential customs complications. The ban reflects broader regional trend toward protectionism during Myanmar conflict escalation. Sellers should: evaluate alternative sourcing from Thailand or Indonesia; adjust pricing strategies for non-subsidized oil; monitor for similar restrictions in other Southeast Asian markets; diversify product sourcing across multiple countries to reduce single-market dependency.
Myanmar's communication blackouts and conflict-driven logistics delays create severe inventory forecasting challenges. The UN documented severed communications preventing accurate casualty reporting; similar blackouts affect supply chain visibility. Sellers should increase safety stock by 30-40% for Myanmar-sourced products, extending lead times from typical 30-45 days to 60-90 days. Implement scenario planning: assume 25% of Myanmar suppliers become inaccessible; model 40-60% cost increases for alternative sourcing; plan for 3-6 month delays on critical inventory. Use demand forecasting software with conflict-risk adjustments; establish supplier redundancy across Vietnam, Thailand, and Indonesia; negotiate flexible payment terms allowing inventory adjustments. Monitor UN humanitarian reports and Asia Times conflict analysis for escalation signals indicating need for emergency sourcing pivots.
Myanmar's escalating conflict creates severe supply chain disruptions for sellers sourcing textiles, electronics, or agricultural products. The UN documented 408 military airstrikes across manufacturing regions (Bago, Magwe, Mandalay, Sagaing) during December 2025-January 2026, with 90,000+ conscripted troops depleting factory labor. Sellers face 40-60% logistics cost increases due to route diversification around conflict zones, 3-6 month inventory delays, and communication blackouts preventing real-time tracking. The military's control of only 263 of 330 townships fragments Myanmar's market, making supplier access unpredictable. Immediate action: diversify sourcing to Vietnam, Thailand, or Indonesia; increase safety stock by 30-40%; negotiate force majeure clauses with Myanmar suppliers.