


Global Market Volatility & Fed Policy Shift | Cross-Border Seller Payment & FX Optimization
- Precious metals crash 9.8-31.4% triggers USD strength, reshaping payment costs and FX arbitrage for international sellers













Overview
Market Volatility Creates Immediate Payment & Currency Optimization Opportunities for Cross-Border Sellers
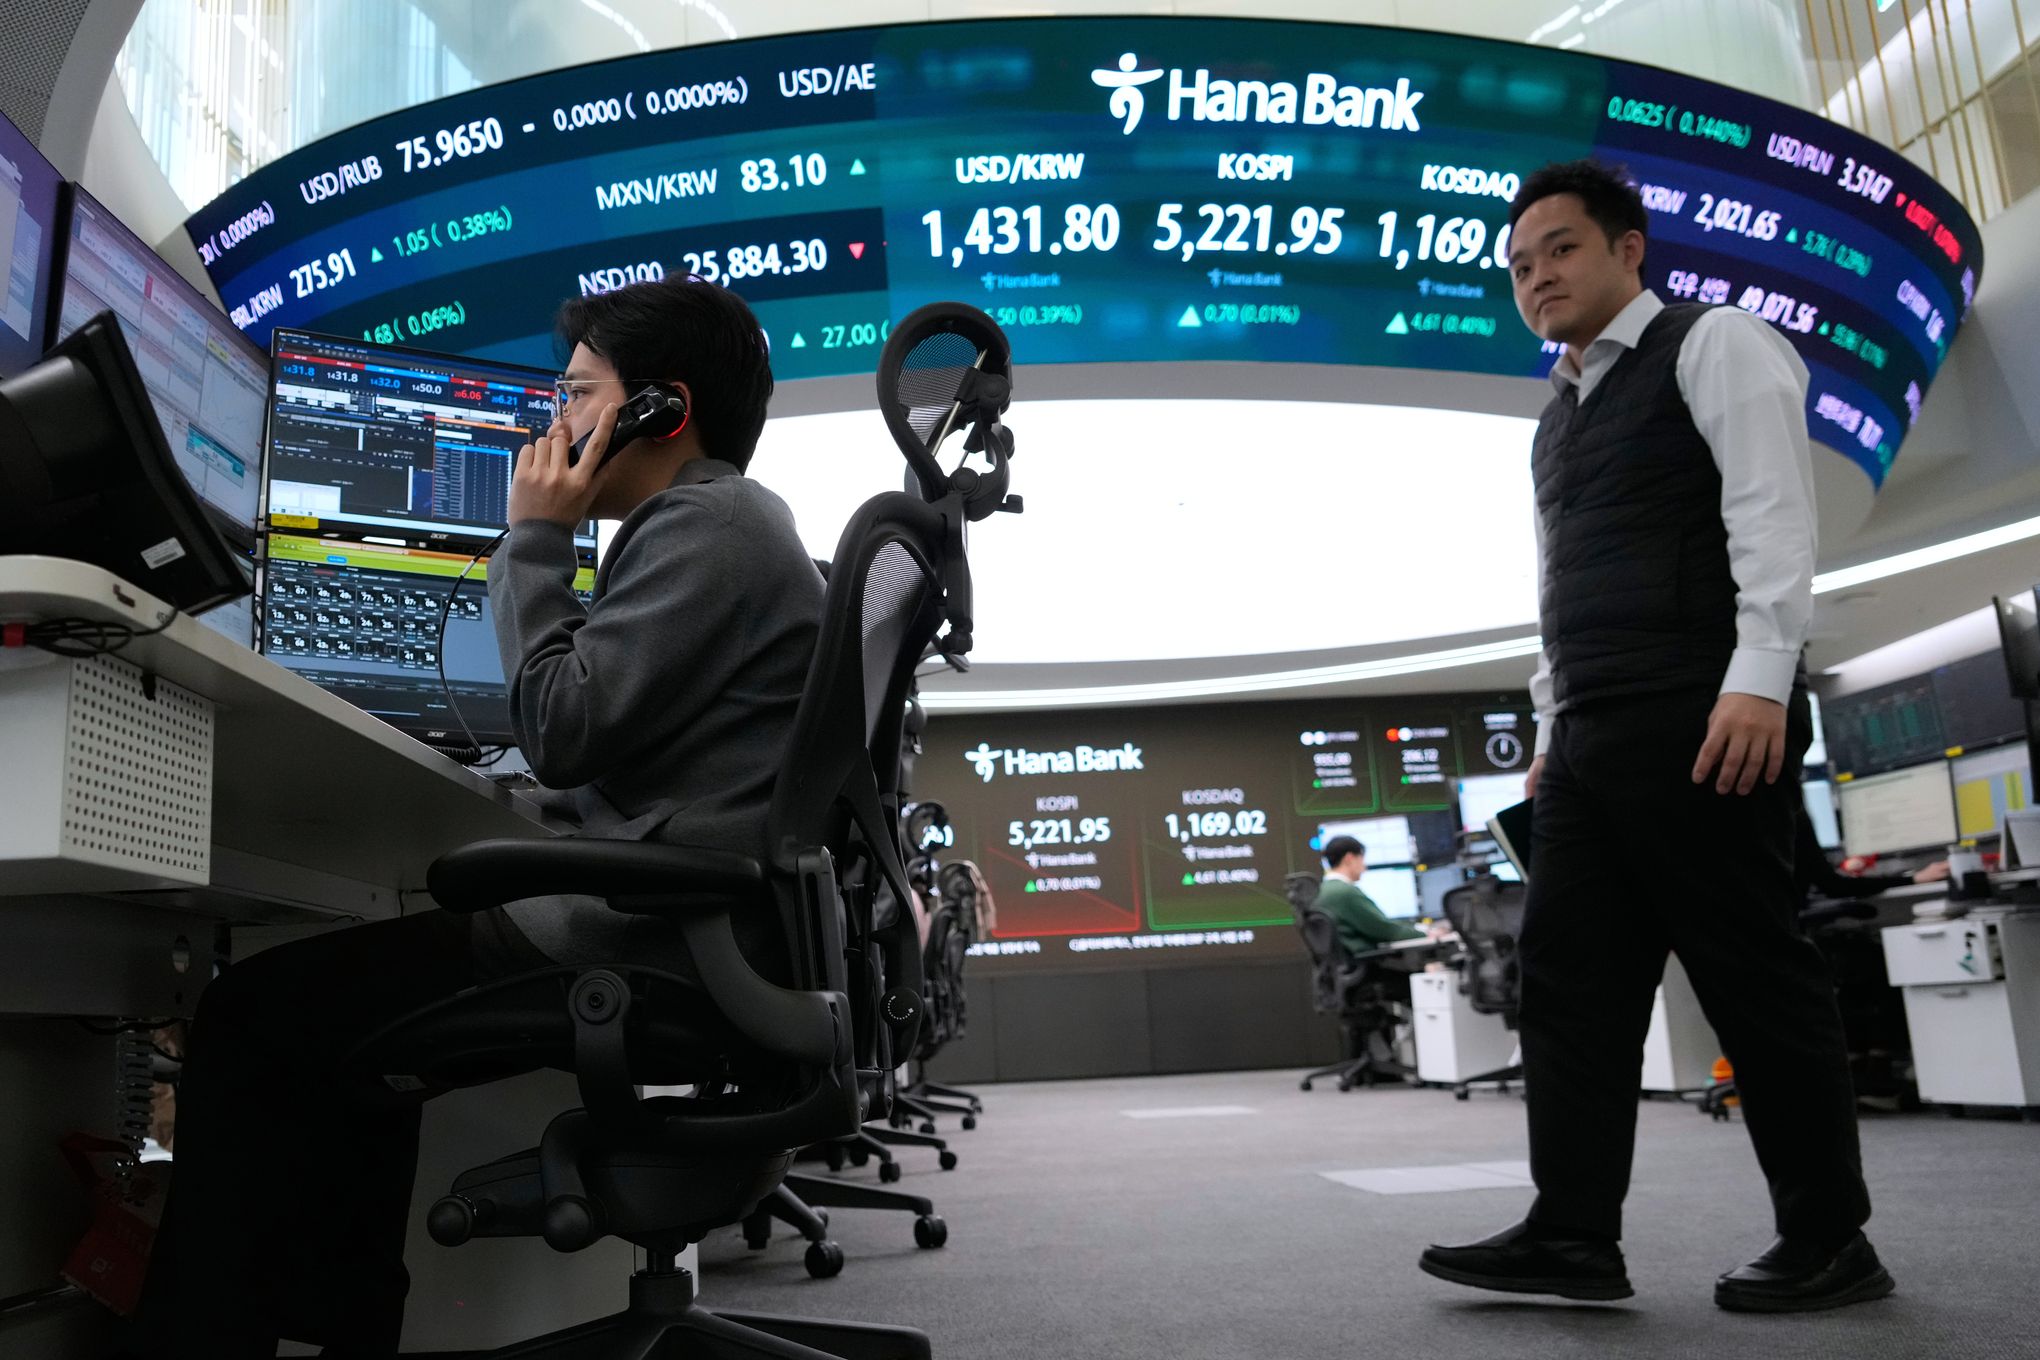
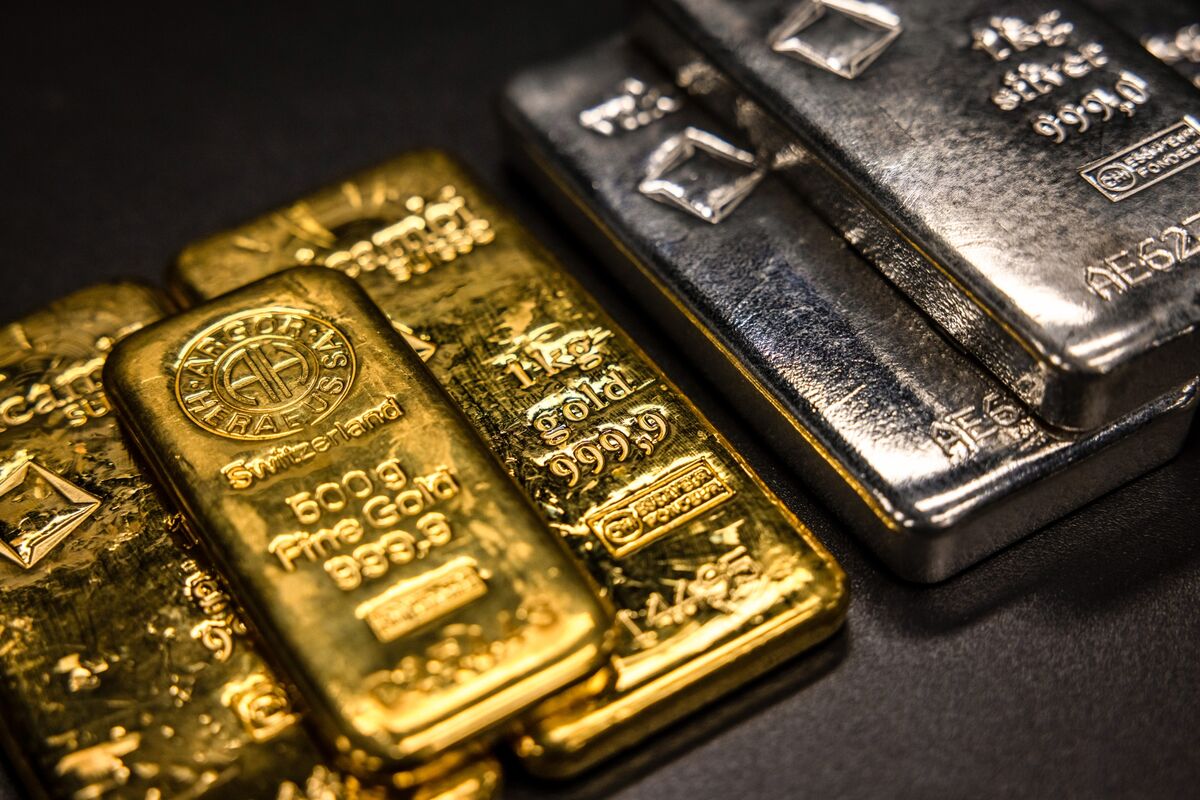
The global market downturn beginning January 30, 2026, presents a critical inflection point for cross-border e-commerce sellers managing international payments and currency exposure. Gold plummeted 9.8% on January 30 (worst day since 1983), with silver crashing 30% on the same day—its worst performance since 1980. By February 2, gold had lost approximately $900 from its $5,594.82 peak, while silver shed $33 from $121.64. This volatility, triggered by Kevin Warsh's Federal Reserve nomination and CME margin hikes, has strengthened the U.S. dollar index significantly, creating both immediate payment cost pressures and FX arbitrage opportunities.
Immediate Payment Cost Implications & Hedging Strategy Shifts
The dollar's strength following Warsh's nomination (which signals potential rate cuts and balance sheet tightening) directly impacts cross-border payment processing costs. Sellers invoicing in USD to international buyers now face reduced demand from overseas purchasers as dollar-priced goods become more expensive. Simultaneously, sellers with USD-denominated costs (inventory, shipping) benefit from favorable conversion rates when paying suppliers in weakening currencies (JPY at 154.77, EUR at 1.1858). The key financial optimization: sellers should immediately lock in forward contracts for Q1-Q2 2026 supplier payments in JPY, CNY, and INR at current favorable rates before potential Fed rate cuts weaken the dollar further. Hedging costs have likely decreased due to reduced volatility expectations post-correction, making 3-6 month forward contracts 15-25% cheaper than during the January peak.
Working Capital Unlock Through Invoice Financing & Inventory Liquidation
The market correction creates urgent working capital needs for sellers holding precious metals-related inventory (jewelry, collectibles, bullion products) that experienced 15-31% valuation declines. Sellers should immediately pursue invoice financing against USD-denominated receivables from international buyers—lenders are offering 2-3% better rates during risk-off periods as they seek stable dollar-denominated assets. Additionally, the CME margin hike feedback loop (forcing retail liquidations) creates wholesale buying opportunities for sellers with cash reserves to acquire inventory at 10-20% discounts from distressed sellers. Sellers can convert this inventory advantage into immediate cash flow by using supply chain financing products (PO financing, inventory loans) at 6-8% APR—significantly lower than the 12-15% rates typical during bull markets.
FX Arbitrage & Payment Route Optimization
The dollar strength creates specific arbitrage opportunities: sellers with EUR-denominated costs can now lock in 1.1858 rates (strengthened from 1.1853) while maintaining USD pricing for North American customers. For Asia-Pacific sellers, the JPY weakness (154.77 yen/USD) creates a 6-month window to refinance yen-denominated debt at lower effective costs. Payment method selection becomes critical—sellers should shift from traditional wire transfers (which lock in spot rates) to forward-dated payment solutions through providers like Wise, OFX, or Payoneer that offer 0.5-1.2% better rates than banks during volatile periods. Sellers shipping from China should accelerate CNY-to-USD conversions immediately, as the dollar strength window may close within 4-8 weeks if rate cut expectations materialize.
Questions 8
What FX arbitrage opportunities exist from the current market conditions?
Three specific opportunities: (1) EUR-denominated costs locked at 1.1858 while maintaining USD pricing for North American customers creates 1-2% margin expansion; (2) JPY weakness (154.77 yen/USD) creates a 6-month refinancing window for yen-denominated debt at lower effective costs; (3) CNY-to-USD conversions should accelerate immediately, as the dollar strength window may close within 4-8 weeks if rate cut expectations materialize. Sellers should execute these within 10-14 business days before market repricing. Forward contracts should be locked in before the Fed's May decision on Jerome Powell's successor.
Should I liquidate inventory affected by the precious metals crash?
Yes, but strategically. Sellers holding precious metals-related inventory (jewelry, collectibles, bullion products) experienced 15-31% valuation declines. Immediate liquidation through supply chain financing (PO financing, inventory loans at 6-8% APR) unlocks working capital faster than traditional sales. Alternatively, sellers with cash reserves should acquire distressed inventory at 10-20% discounts from forced sellers, then use inventory financing to convert to cash flow. The CME margin hike created a feedback loop forcing retail liquidations—this window typically closes within 2-4 weeks as prices stabilize.