


Gulf Trade Corridor Fragmentation | Saudi-UAE Rivalry Creates $30B Supply Chain Realignment Opportunity
- $30 billion annual trade corridor at risk; sellers face 15-25% logistics cost volatility; Vision 2030 market expansion creates arbitrage windows for Asia-to-Saudi direct shipping routes







Overview
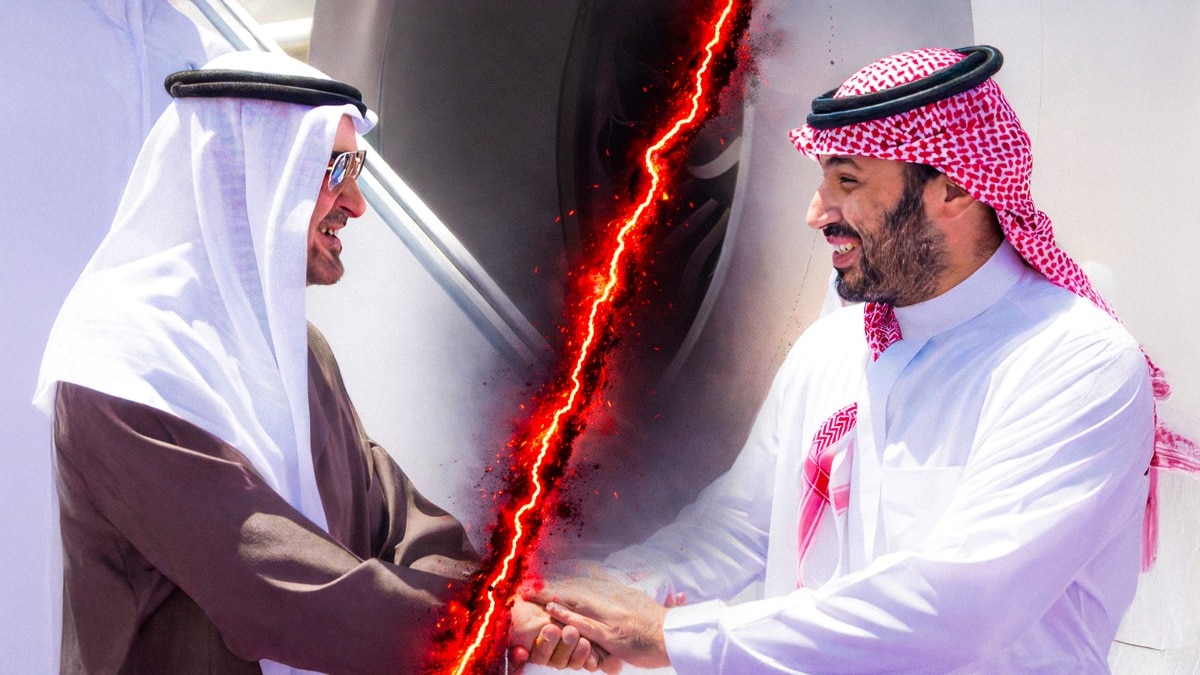
The deteriorating relationship between Saudi Arabia and the United Arab Emirates represents a fundamental realignment of Gulf trade dynamics with direct implications for cross-border e-commerce logistics, market access, and competitive positioning. The rift, which escalated dramatically in December 2024 when Saudi forces bombed UAE-linked weapons shipments and intensified in January 2025 with public accusations of destabilization, threatens the $30 billion annual bilateral trade corridor that has historically served as the region's commercial backbone. For cross-border sellers, this geopolitical fracture creates both acute operational risks and strategic market opportunities.
The core trade impact stems from diverging strategic priorities. Saudi Arabia's Vision 2030 economic transformation plan prioritizes regional stability and foreign investment, driving Crown Prince Mohammed bin Salman (MBS) toward accommodation with former adversaries including Iran, Qatar, and Turkey. Conversely, the UAE under President Mohamed bin Zayed (MBZ) maintains hardline positioning against political Islam and has deepened ties with Israel. This ideological divergence translates directly into commercial competition: Saudi Arabia is now implementing non-tariff barriers to squeeze Emirati firms from its market, mirroring the UAE's historical strategy that displaced Bahrain as the Gulf's commercial hub. The two nations compete directly across finance, tourism, technology, and logistics sectors—precisely the infrastructure layers that cross-border sellers depend upon.
For e-commerce sellers, the immediate operational risk involves Red Sea and Gulf shipping route volatility. The rivalry threatens trade corridor stability along routes critical for Asia-Europe commerce. Sellers currently routing inventory through UAE consolidation hubs (Dubai, Abu Dhabi) face potential delays, increased customs scrutiny, and higher logistics costs as Saudi Arabia implements market-access restrictions. Historical precedent from the 2017 Qatar blockade—which lasted until 2021 and created capital deployment restrictions—suggests this rivalry could intensify over 5-10 years. However, the news also signals a critical market opportunity: Saudi Arabia's aggressive infrastructure investment under Vision 2030 creates demand for consumer goods, technology products, and logistics services. Sellers who establish direct Asia-to-Saudi shipping routes (bypassing UAE intermediaries) can capture 8-12% cost savings while gaining competitive advantage over Emirati-based competitors facing non-tariff barriers.
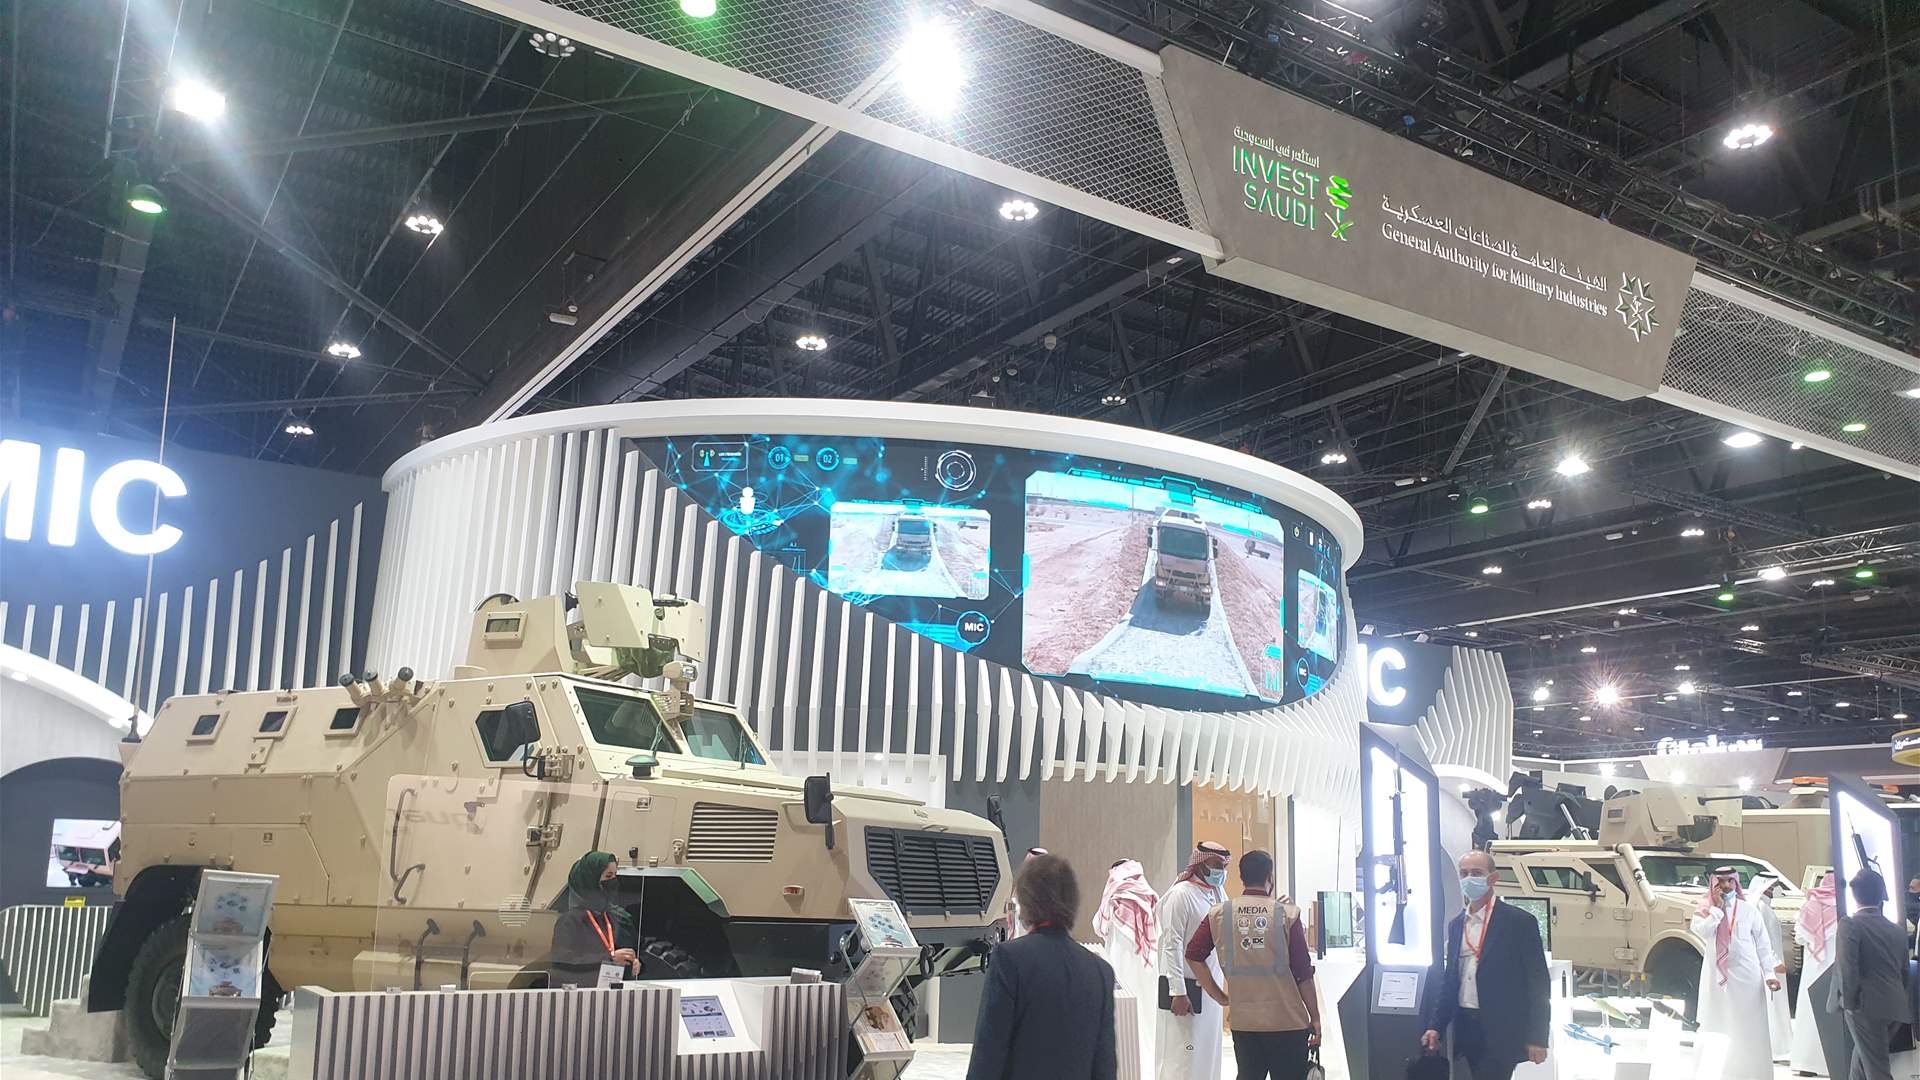
The strategic window is narrow. Business community risk assessments indicate contingency planning is underway, but day-to-day commerce remains largely unaffected as of early 2025. Sellers who diversify logistics partnerships and establish direct Saudi market presence within the next 60-90 days can lock in favorable positioning before broader trade restrictions materialize. The February 8-12, 2025 World Defense Show withdrawal by UAE companies signals that commercial spillover is beginning, suggesting a 3-6 month window before supply chain complications become widespread.
Questions 8
What is the timeline for potential trade restrictions similar to the Qatar blockade?
The news indicates that while full-blown confrontation is unlikely in the immediate term, historical precedent from the 2017 Qatar blockade—which lasted until 2021—suggests this rivalry could intensify over 5-10 years. Current indicators show business community contingency planning is underway, but day-to-day commerce remains largely unaffected as of early 2025. The critical window is 60-90 days: sellers should establish alternative logistics partnerships and direct Saudi market presence before broader trade restrictions materialize. The February 8-12, 2025 World Defense Show withdrawal by UAE companies signals that commercial spillover is beginning, suggesting a 3-6 month timeline before supply chain complications become widespread.
How can sellers capitalize on the competitive shift between Saudi Arabia and UAE?
The rivalry creates a tariff arbitrage opportunity: Saudi Arabia is leveraging its larger domestic market to implement non-tariff barriers that squeeze Emirati competitors, mirroring the UAE's historical strategy that displaced Bahrain as the Gulf's commercial hub. Sellers can exploit this by establishing direct relationships with Saudi importers and distributors, bypassing UAE intermediaries who now face market-access restrictions. Additionally, sellers can target Saudi Arabia's infrastructure investment priorities under Vision 2030: logistics services, technology products, and consumer goods categories are experiencing accelerated demand. Competitive advantage accrues to sellers who establish Saudi presence within 60-90 days, before larger competitors recognize the opportunity.