




West Bank Land Policy Escalation | Market Instability Impacts Cross-Border Trade
- Geopolitical tensions threaten Middle East e-commerce corridors; 700K+ Israeli settlers create consumer market volatility; Palestinian market access disruptions affect 3M+ population




















概览
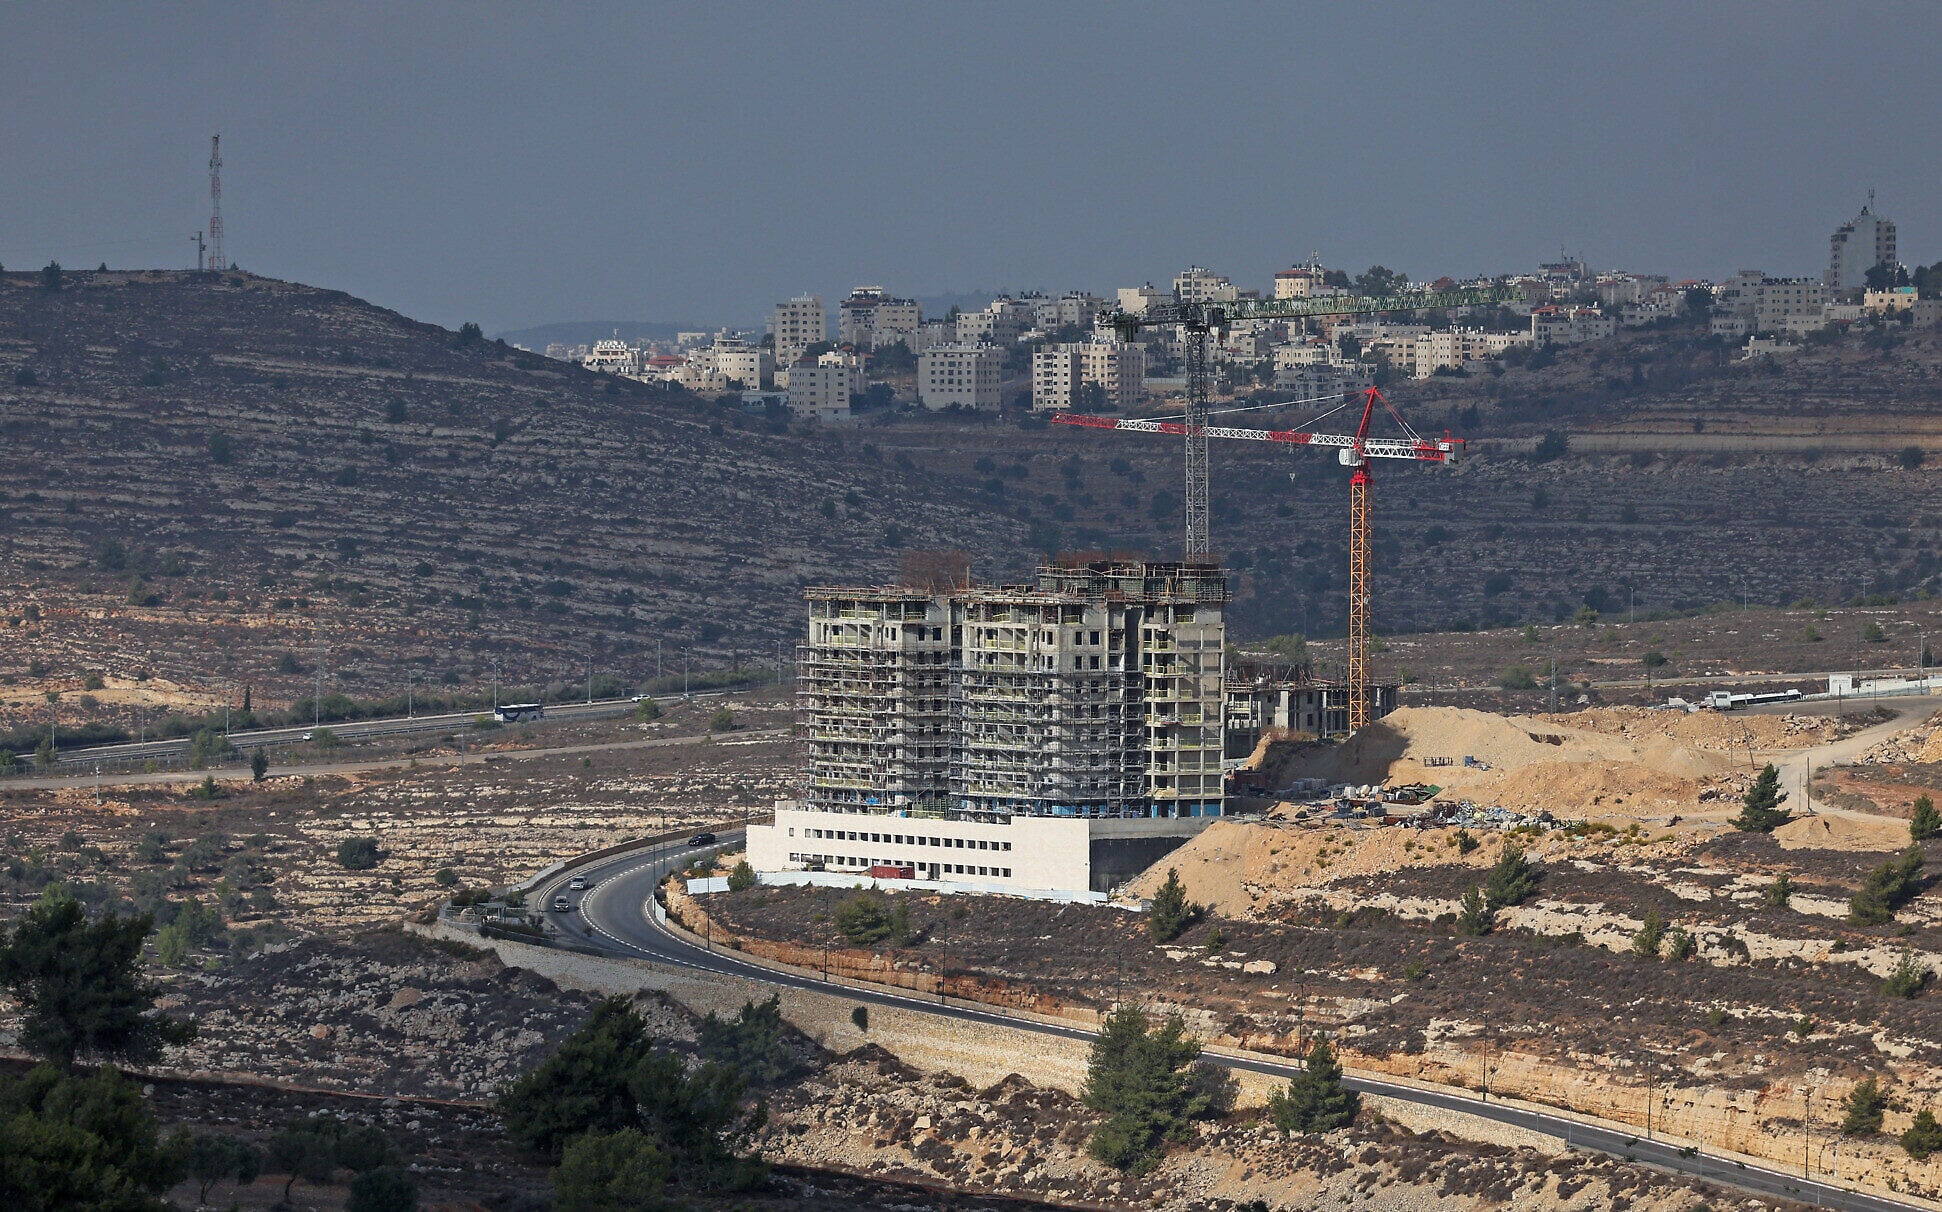
The Israeli government's February 15, 2026 approval of West Bank land registration represents a critical geopolitical escalation with direct implications for cross-border e-commerce operations in the Middle East region. The policy resumes land-title settlement procedures frozen since 1967, affecting Area C (60% of West Bank under Israeli military control) and potentially extending Israeli administrative control to 83% of the territory. This bureaucratic institutionalization of territorial control creates significant market access challenges for sellers targeting Palestinian consumers and disrupts supply chain stability across the Levant corridor.
For cross-border sellers, this escalation creates three immediate operational risks: First, market fragmentation and consumer purchasing power disruption across the Palestinian territories. The 3 million Palestinians in the West Bank face legal uncertainty, property seizures, and economic instability—directly reducing consumer spending capacity for imported goods. Sellers targeting Palestinian e-commerce markets (estimated $200-400M annual cross-border import value) should expect 15-25% demand contraction as households redirect resources toward legal defense and property documentation. Second, supply chain corridor instability through the region. The policy's implementation beginning in 2025 will increase bureaucratic friction, documentation requirements, and potential customs delays for goods transiting through Israeli-controlled logistics hubs serving Palestinian, Jordanian, and broader Levant markets. Sellers using Israeli ports (Ashdod, Haifa) for regional distribution should anticipate 10-15% processing delays and potential tariff complications. Third, reputational and compliance risks for sellers operating in both Israeli and Palestinian markets. International criticism from the EU, Germany, Jordan, and Qatar signals potential future sanctions or trade restrictions. Sellers maintaining dual-market operations face increasing pressure to choose market alignment, with potential ESG (Environmental, Social, Governance) implications affecting access to Western marketplaces and investor capital.
The policy's timing creates a critical decision window through Q2 2025. With registration procedures commencing in 2025 and international responses escalating, sellers should immediately audit their Middle East supply chain exposure. For sellers with Palestinian market focus, consider diversifying to alternative Levant markets (Jordan, Lebanon) or shifting inventory positioning to avoid customs complications. For sellers using Israeli logistics infrastructure, evaluate alternative Mediterranean ports (Cyprus, Greece) or Red Sea corridors. The 700,000 Israeli settlers represent a growing consumer base with increasing purchasing power, but geopolitical volatility creates unpredictable regulatory environments. Monitor UN Security Council actions and EU trade policy responses—potential sanctions could restrict Israeli market access within 6-12 months, making current market positioning decisions critical for long-term viability in the region.
問題 7
Which seller segments face the highest risk from this policy change?
Three segments face elevated risk: (1) Small/medium sellers (SMBs) with Palestinian market focus—limited resources to diversify quickly; (2) Sellers using Israeli logistics infrastructure for regional distribution—high exposure to customs delays; (3) Sellers with ESG-sensitive products or investor bases—reputational risk from operating in contested territories. Large sellers with diversified regional operations face lower risk but should still audit exposure. Sellers in consumer electronics, apparel, and home goods categories face higher risk than commodity sellers due to greater Palestinian consumer demand sensitivity.
What is the timeline for implementation and when should sellers make repositioning decisions?
The policy was approved February 15, 2026, with registration procedures commencing in 2025. This creates a critical decision window through Q2 2025—sellers must audit and reposition supply chains before bureaucratic complications intensify. International responses are escalating rapidly (EU, Germany, Jordan, Qatar all condemning the policy), suggesting potential sanctions could emerge within 6-12 months. Sellers should treat Q2 2025 as a hard deadline for supply chain diversification decisions. Delay increases risk of being caught in customs complications or potential trade restrictions.