

EPA Right-to-Repair Ruling Opens $2B+ Aftermarket Opportunity | Agricultural Equipment & Parts Sellers
- February 2026 guidance eliminates manufacturer repair monopolies, enabling independent service networks and aftermarket parts sales for diesel equipment; fertilizer tariff analysis reveals $6.9B cost burden creating alternative supplier opportunities



概览
The EPA's February 2, 2026 right-to-repair guidance represents a watershed regulatory moment with profound implications for agricultural equipment aftermarket sellers and compliance service providers. By explicitly permitting farmers to access diagnostic tools, software, and temporary emission system overrides on non-road diesel engines (including DEF systems, selective catalytic reduction, and inducement systems), the EPA has dismantled manufacturer-imposed software locks that previously created exclusive dealer networks. This regulatory shift eliminates a critical compliance barrier that protected OEM repair monopolies, opening an estimated $2B+ aftermarket opportunity for independent repair shops, parts suppliers, and diagnostic tool providers.
The compliance opportunity is immediate and substantial. Manufacturers like John Deere (which prompted this guidance through a June 2025 request) previously used Clean Air Act provisions as a legal shield to restrict third-party repairs. The EPA's clarification—that temporary emission overrides for repair purposes do NOT violate the Clean Air Act—removes this legal justification entirely. For sellers, this creates three distinct market opportunities: (1) Diagnostic tool and software access services for independent mechanics and farmers, (2) Aftermarket parts distribution for diesel engine components previously locked behind dealer networks, and (3) Compliance documentation and certification services to help independent repair shops demonstrate proper emission system restoration.
Parallel market dynamics in fertilizer inputs reveal tariff-driven pricing distortions that create alternative supplier opportunities. Texas A&M research quantifies that countervailing duties on Moroccan and Russian phosphate (imposed since 2021) added $6.9 billion in costs to U.S. producers across 2021-2025—far exceeding the impact of market concentration between Mosaic and Nutrien. This tariff burden incentivizes sellers to: (1) source alternative fertilizer products from non-tariffed suppliers, (2) develop domestic substitutes or blended products, and (3) provide tariff-impact analysis services to agricultural buyers. Equipment cost inflation of 45% (per USDA Secretary Rollins) combined with repair cost monopolies created a perfect storm—the right-to-repair guidance directly addresses the repair cost component, while tariff policy remains the primary lever for input cost relief.
Regulatory enforcement intensity is LOW for right-to-repair compliance, creating a fast-track opportunity window.** The guidance explicitly states it "does not weaken emission standards or change existing law"—it merely clarifies existing Clean Air Act provisions. This means sellers entering the independent repair ecosystem face minimal new compliance burden. Farmers and mechanics can immediately begin accessing repair tools without triggering EPA enforcement actions, provided equipment returns to full compliance. The market elimination rate is ZERO for compliant sellers—the guidance protects rather than penalizes independent repair providers. However, sellers must understand that temporary emission overrides are permitted ONLY for repair purposes, and equipment must return to full compliance afterward. Sellers offering diagnostic services or repair documentation must clearly communicate this compliance requirement to avoid liability exposure.
問題 8
What does the EPA's February 2026 right-to-repair guidance permit farmers to do with their equipment?
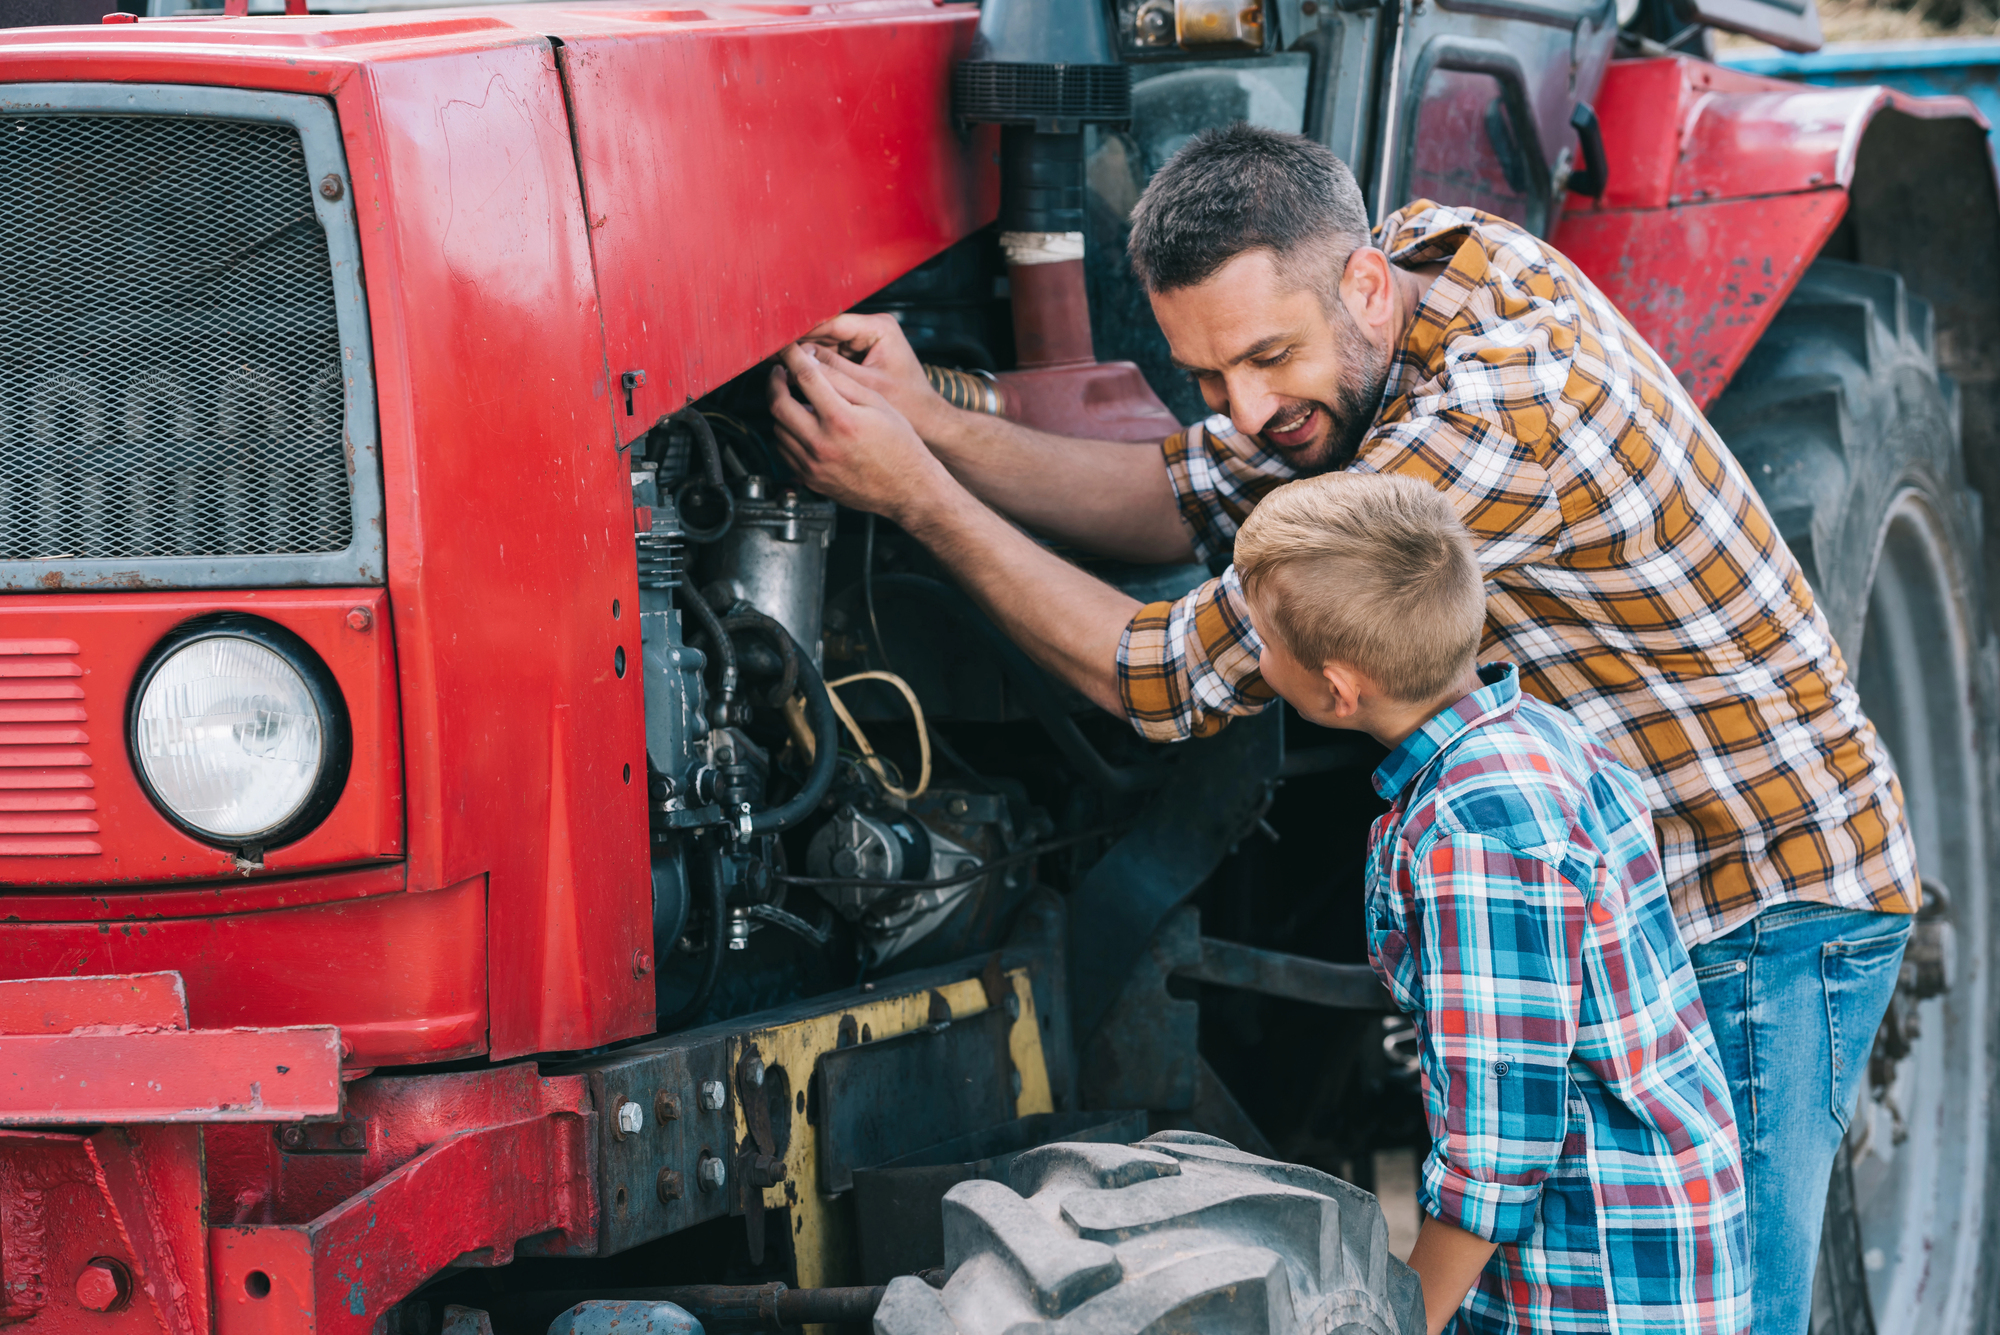
The EPA guidance explicitly permits farmers and independent repair shops to access diagnostic tools, software, and temporarily override emission control systems (including DEF systems and selective catalytic reduction) for repair purposes on non-road diesel engines. Critically, the guidance states that the Clean Air Act does NOT prohibit these actions, provided the equipment returns to full compliance after repairs are completed. This eliminates the legal justification manufacturers previously used to restrict repairs exclusively to authorized dealers. Farmers can now perform field repairs or use local mechanics without traveling to dealer networks, reducing downtime during critical planting and harvest seasons.
How does this guidance eliminate manufacturer repair monopolies and create seller opportunities?
Manufacturers like John Deere previously used Clean Air Act compliance as a legal shield to justify proprietary software locks and diagnostic tool restrictions, forcing farmers into exclusive dealer networks. The EPA's clarification removes this legal justification entirely—manufacturers can no longer claim Clean Air Act violations justify repair restrictions. This opens three immediate seller opportunities: (1) diagnostic tool and software access services for independent mechanics, (2) aftermarket parts distribution for diesel engine components, and (3) compliance documentation services. The estimated aftermarket opportunity exceeds $2B, as farmers shift from dealer-dependent repairs to independent service networks. Sellers entering this space face minimal compliance burden since the guidance clarifies existing law rather than creating new requirements.