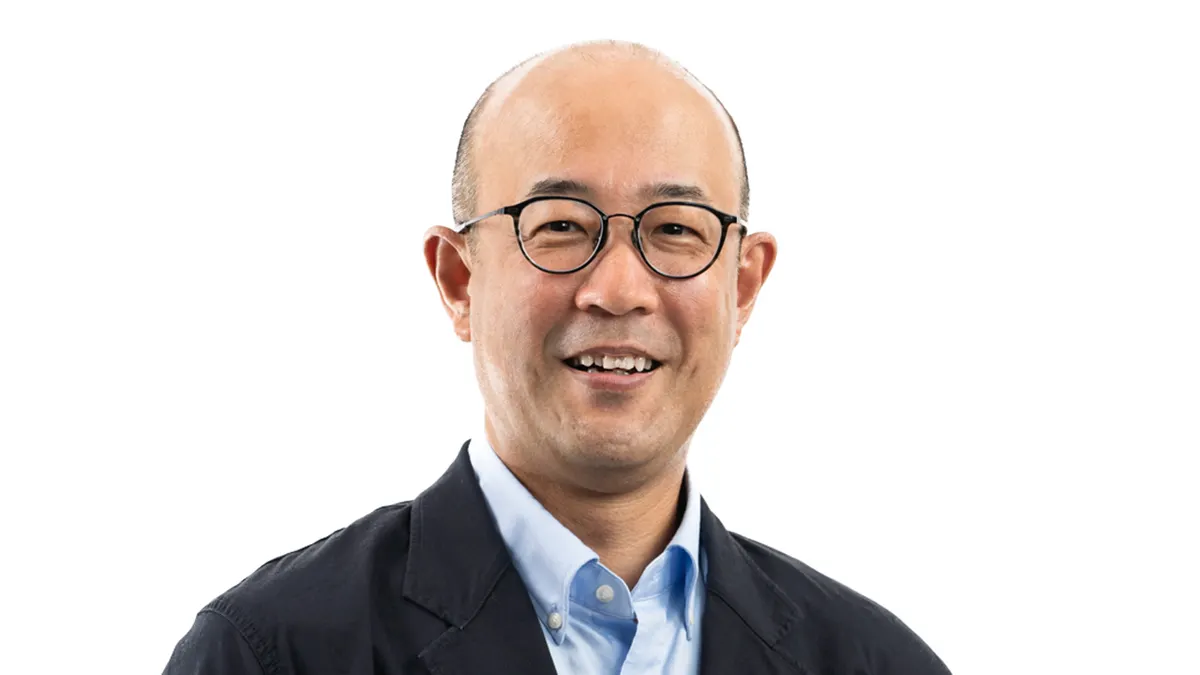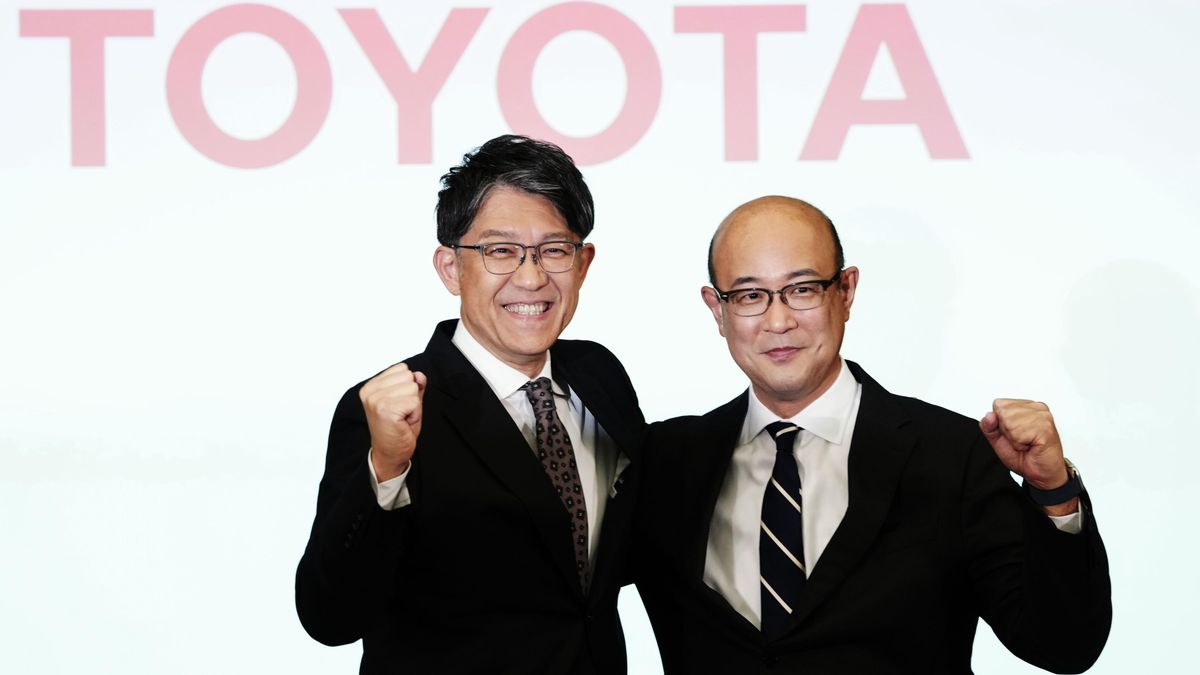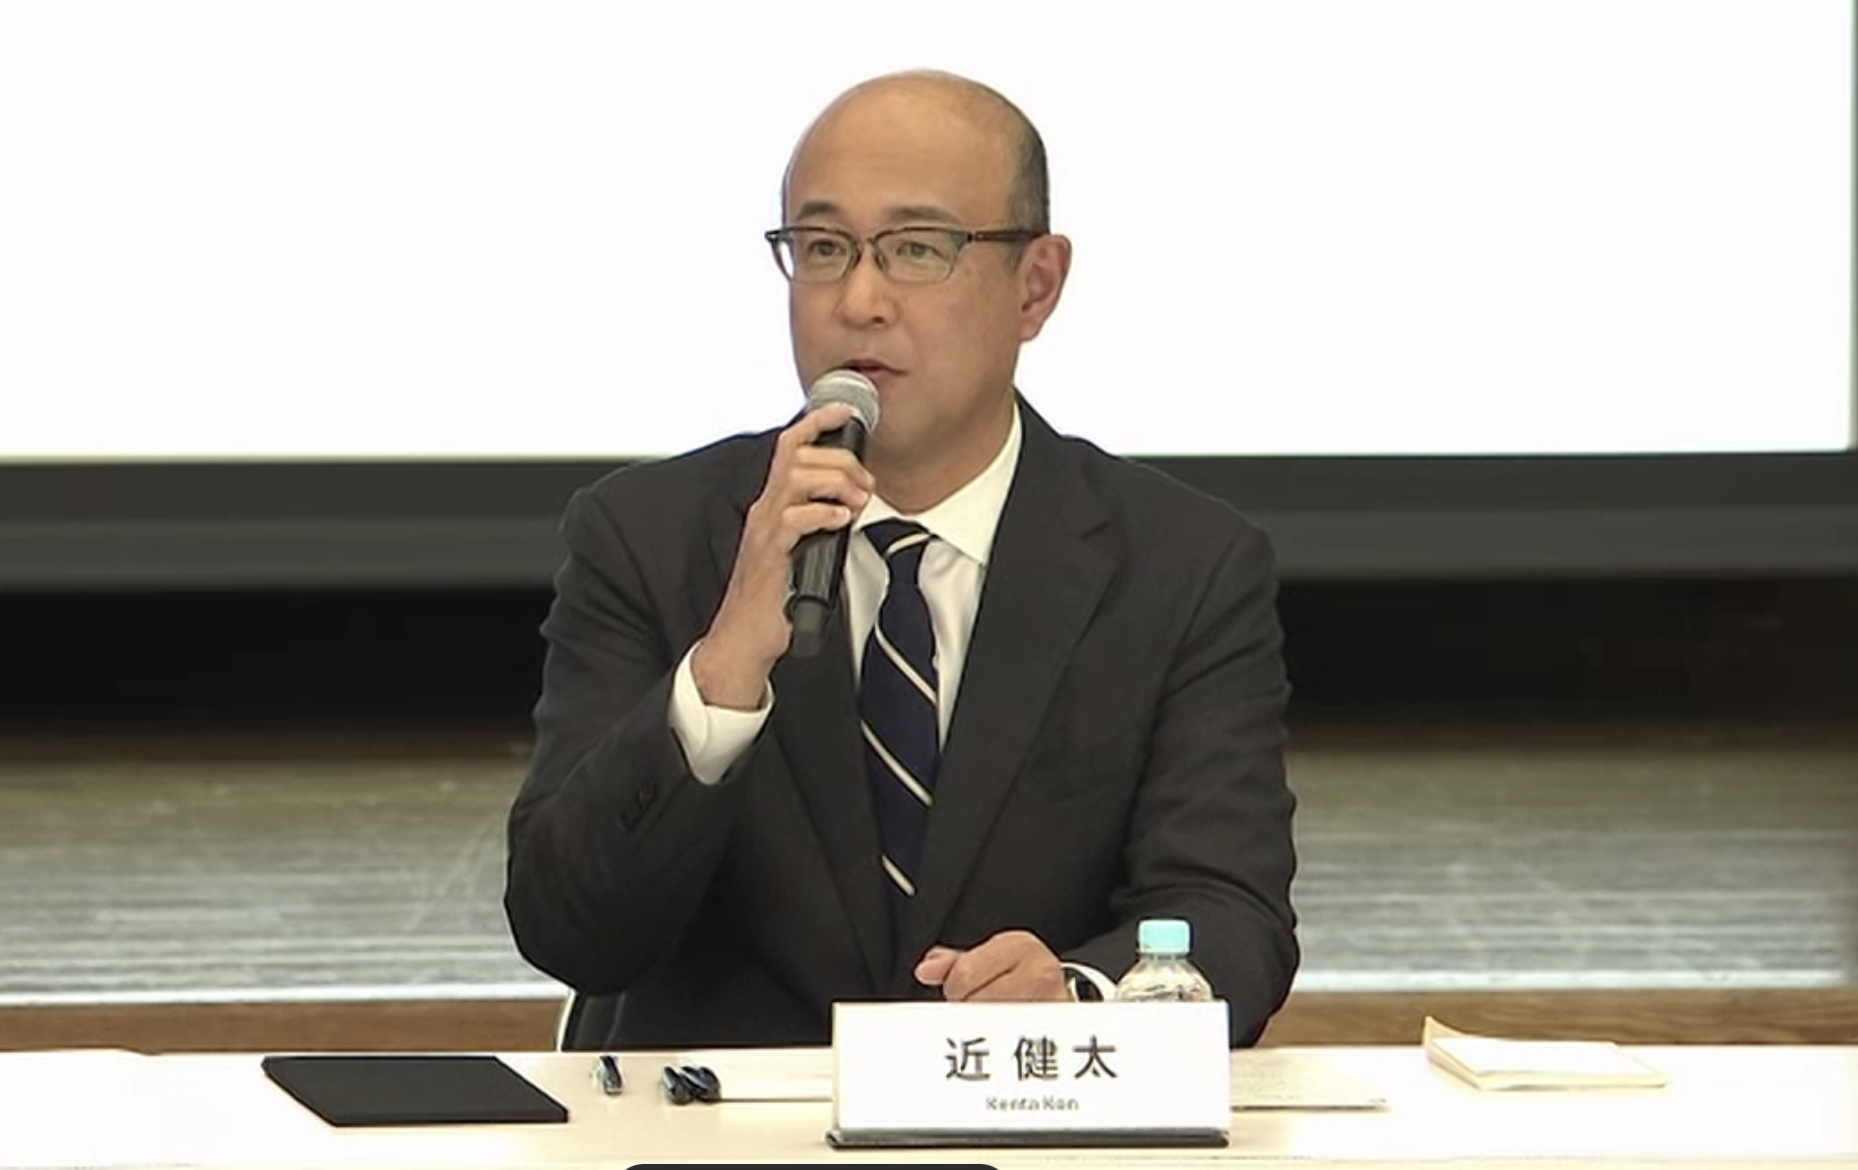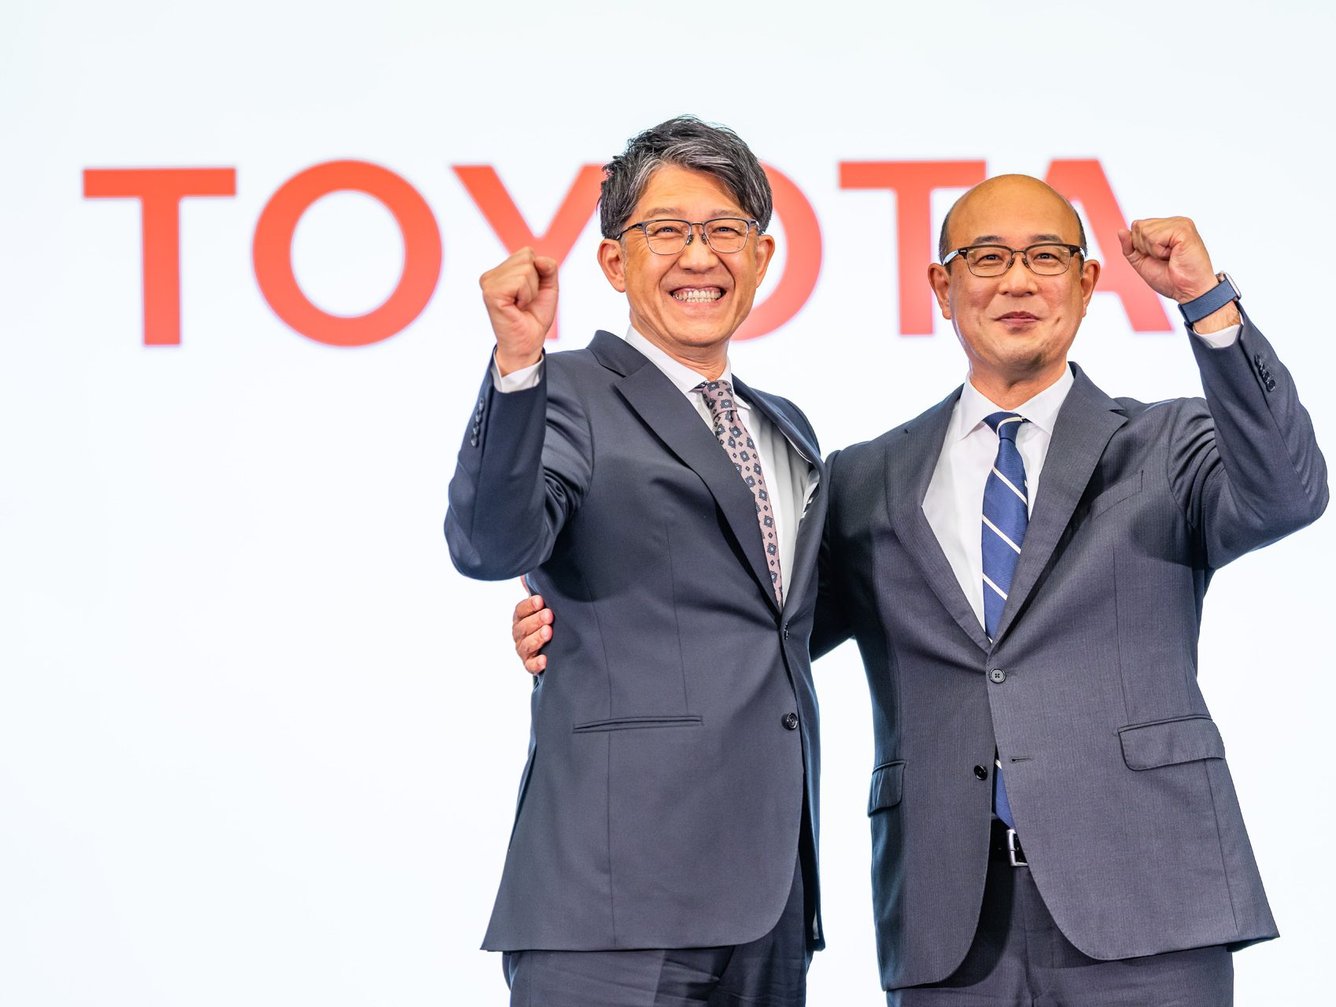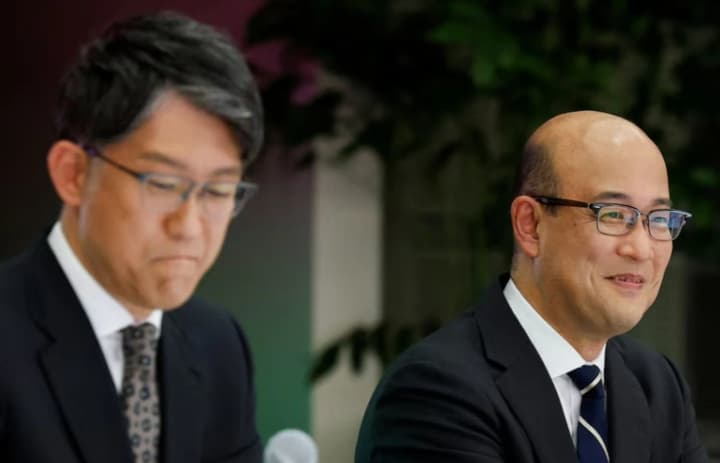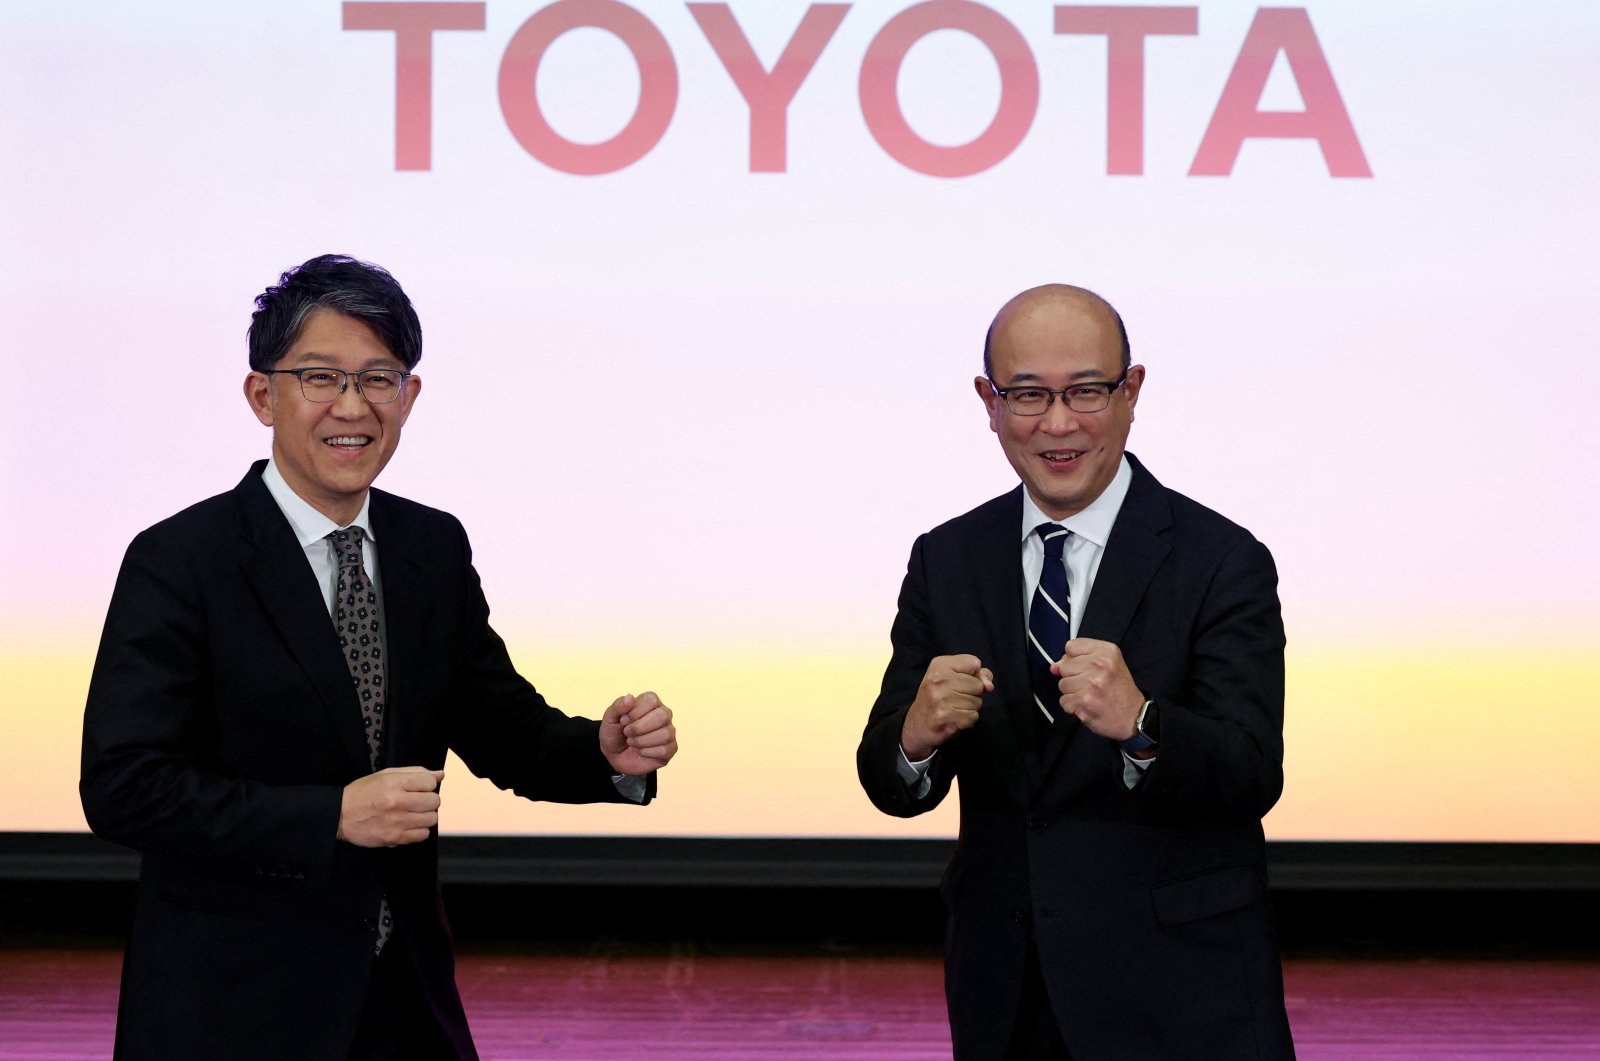



Toyota's February 6, 2026 leadership transition—replacing CEO Koji Sato with CFO Kenta Kon effective April 1, 2026—signals a critical inflection point in global automotive supply chains directly affecting cross-border e-commerce sellers. The $9 billion tariff impact from Trump administration policies, combined with Japan's newly negotiated 15% automotive tariff (down from threatened 27.5% but still 6x historical rates), has forced the world's largest automaker to prioritize cost reduction and margin stabilization over growth initiatives.
For automotive component sellers, this creates a 6-12 month window of acute supply chain vulnerability. Toyota's mandate under new CFO-led management will likely trigger aggressive procurement cost-cutting, component consolidation, and supplier rationalization. E-commerce sellers dependent on Japanese automotive parts imports face three immediate pressures: (1) tariff pass-through costs increasing 8-15% on HS codes 8708 (vehicle parts), 8704 (commercial vehicles), and 8703 (passenger vehicles); (2) supplier payment term compression as OEMs demand faster cash conversion; and (3) inventory destocking as manufacturers reduce safety stock in response to tariff uncertainty.
The competitive landscape is shifting toward alternative sourcing corridors. Canada's announced multi-billion dollar EV incentive package (February 5, 2026) signals a strategic shift away from Japan-U.S. direct trade. Sellers currently sourcing Japanese automotive components should evaluate Vietnam (lower tariff exposure), Mexico (USMCA advantages), and South Korea (emerging EV battery supply) as alternative sourcing countries. BYD's dominance in EV batteries and software—mentioned as Toyota's primary competitive threat—indicates that sellers in traditional automotive aftermarket categories (HS 8708, 8704) face margin compression, while EV-adjacent categories (battery components, software tools, charging infrastructure) represent growth opportunities.
The timing window is critical. With Kon's appointment effective April 1, 2026, Toyota's cost-cutting initiatives will likely accelerate through Q2-Q3 2026. Sellers should expect: (1) component price reductions of 5-8% as suppliers compete for volume; (2) increased demand for logistics optimization services (3PL, fulfillment networks); and (3) opportunities in tariff mitigation products (customs brokerage, trade compliance software). The $9 billion impact demonstrates that tariff arbitrage opportunities exist for sellers who can identify products benefiting from tariff rate differentials across sourcing countries and destination markets.
The 6-12 month window from February 2026 through August 2026 represents peak opportunity before larger competitors establish alternative sourcing networks. Toyota's April 1 CEO transition marks the acceleration point for cost-cutting initiatives; the subsequent 90-120 days (April-July 2026) will see rapid supplier consolidation and procurement strategy shifts. Sellers who establish alternative sourcing relationships (Vietnam, Mexico, South Korea, Canada) and implement tariff optimization strategies by June 30, 2026 will capture 15-25% margin advantages over competitors who delay. The competitive advantage erodes as larger sellers (Amazon, Alibaba, eBay) develop institutional tariff mitigation capabilities; first-movers can establish supplier relationships and customer contracts before price competition intensifies. Immediate actions: conduct HS code tariff analysis, identify alternative sourcing countries, and establish supplier relationships by April 15, 2026.
Pricing strategy must account for three competing forces: (1) 15% tariff on Japanese imports increasing landed costs 8-15%; (2) Toyota's cost-cutting driving 5-8% component price reductions as suppliers compete for volume; (3) margin compression across the automotive supply chain. Sellers should implement dynamic pricing by sourcing country: Japanese-sourced components face 15% tariff headwinds, while Mexico-sourced products benefit from 0% USMCA tariffs. Recommended pricing approach: maintain current prices on alternative-sourced products (Vietnam, Mexico, South Korea) to capture market share from Japanese suppliers; reduce prices on Japanese-sourced inventory by 3-5% to accelerate turnover before tariff pass-through occurs. Monitor competitor pricing weekly through April-June 2026; expect 8-12% price volatility as suppliers adjust to new tariff environment. Lock in supplier pricing by May 31, 2026 before tariff-driven cost increases stabilize.
Vietnam, Mexico, and South Korea present strategic sourcing alternatives to Japan given current tariff structures. Vietnam benefits from lower tariff exposure and emerging manufacturing capacity in automotive components. Mexico offers USMCA advantages with 0% tariffs on qualifying automotive products shipped to the U.S., making it optimal for HS 8708 (vehicle parts) and 8704 (commercial vehicles). South Korea is positioning as an EV battery and software component leader, aligning with BYD's competitive threat to traditional automakers. Sellers should conduct tariff rate analysis by HS code for each sourcing country using USITC's interactive tariff schedule to identify 3-5% tariff savings opportunities through sourcing diversification by Q2 2026.
EV-adjacent categories represent growth opportunities as traditional automotive suppliers face margin compression. Battery components, charging infrastructure, EV software tools, and electric motor parts are experiencing accelerated demand as BYD's EV dominance forces legacy automakers like Toyota to accelerate electrification. Sellers should prioritize categories including: lithium-ion battery packs (HS 8507), electric motors (HS 8501), charging cables (HS 8544), and EV management software. These categories typically see 15-25% annual growth during tariff-driven supply chain transitions, with lower competitive saturation than traditional aftermarket parts. The timing window through 2026 offers first-mover advantages before larger competitors establish EV component supply chains.
Toyota's appointment of CFO Kenta Kon signals aggressive inventory destocking and supplier consolidation through Q2-Q3 2026. Sellers should reduce safety stock on slow-moving Japanese automotive components by 20-30% and accelerate inventory turnover to avoid obsolescence during the transition period. Simultaneously, build inventory in alternative sourcing countries (Vietnam, Mexico, South Korea) to capture market share as Japanese suppliers lose volume. Implement just-in-time procurement strategies to reduce working capital exposure to tariff volatility. Monitor Toyota's quarterly earnings announcements (April 1 onwards) for procurement guidance; expect 5-8% component price reductions as suppliers compete for retained volume, creating opportunities to improve margins through strategic timing of purchases.
The $9 billion tariff impact creates demand for tariff mitigation and trade compliance services. Sellers can develop offerings including: tariff rate analysis by HS code and sourcing country, customs brokerage optimization, duty drawback consulting, and trade agreement utilization (USMCA, Japan-U.S. agreement). Tariff mitigation software and consulting services typically command 2-5% of transaction value for automotive supply chains. Sellers with expertise in HS code classification (8708 vs. 8704 vs. 8703 distinctions) can offer reclassification consulting to reduce tariff exposure. The April 1-June 30, 2026 window represents peak demand as suppliers implement new sourcing strategies; position services to capture 10-15% of the automotive component market's tariff optimization spend.
Toyota's $9 billion tariff impact directly signals margin compression for sellers importing Japanese automotive components (HS codes 8708, 8704, 8703). The newly negotiated 15% U.S. tariff on Japanese auto exports—6x higher than historical rates—will cascade through supply chains as Toyota implements cost-cutting measures under new CFO leadership. Sellers should expect 8-15% cost increases on Japanese-sourced parts through Q2-Q3 2026, with potential 5-8% price reductions as suppliers compete for volume during Toyota's procurement rationalization. The April 1, 2026 CEO transition deadline marks when aggressive cost-cutting initiatives will accelerate, creating a 6-12 month window of supply chain volatility affecting inventory planning and pricing strategies.
Canada's multi-billion dollar EV incentive package (announced February 5, 2026) signals a strategic shift in North American automotive manufacturing away from Japan-U.S. direct trade. Sellers should evaluate establishing Canadian sourcing relationships for EV components, batteries, and related products to capture incentive-driven manufacturing expansion. Canadian EV component suppliers will likely offer competitive pricing (subsidized by government incentives) and USMCA tariff advantages (0% on qualifying products). The timing window through 2026-2027 offers first-mover advantages in establishing Canadian supply relationships before larger competitors recognize the opportunity. Monitor Canadian government EV incentive announcements for specific product categories and supplier eligibility; prioritize categories with 15%+ tariff savings potential through Canadian sourcing versus Japan or China alternatives.
The 6-12 month window from February 2026 through August 2026 represents peak opportunity before larger competitors establish alternative sourcing networks. Toyota's April 1 CEO transition marks the acceleration point for cost-cutting initiatives; the subsequent 90-120 days (April-July 2026) will see rapid supplier consolidation and procurement strategy shifts. Sellers who establish alternative sourcing relationships (Vietnam, Mexico, South Korea, Canada) and implement tariff optimization strategies by June 30, 2026 will capture 15-25% margin advantages over competitors who delay. The competitive advantage erodes as larger sellers (Amazon, Alibaba, eBay) develop institutional tariff mitigation capabilities; first-movers can establish supplier relationships and customer contracts before price competition intensifies. Immediate actions: conduct HS code tariff analysis, identify alternative sourcing countries, and establish supplier relationships by April 15, 2026.
Pricing strategy must account for three competing forces: (1) 15% tariff on Japanese imports increasing landed costs 8-15%; (2) Toyota's cost-cutting driving 5-8% component price reductions as suppliers compete for volume; (3) margin compression across the automotive supply chain. Sellers should implement dynamic pricing by sourcing country: Japanese-sourced components face 15% tariff headwinds, while Mexico-sourced products benefit from 0% USMCA tariffs. Recommended pricing approach: maintain current prices on alternative-sourced products (Vietnam, Mexico, South Korea) to capture market share from Japanese suppliers; reduce prices on Japanese-sourced inventory by 3-5% to accelerate turnover before tariff pass-through occurs. Monitor competitor pricing weekly through April-June 2026; expect 8-12% price volatility as suppliers adjust to new tariff environment. Lock in supplier pricing by May 31, 2026 before tariff-driven cost increases stabilize.
Vietnam, Mexico, and South Korea present strategic sourcing alternatives to Japan given current tariff structures. Vietnam benefits from lower tariff exposure and emerging manufacturing capacity in automotive components. Mexico offers USMCA advantages with 0% tariffs on qualifying automotive products shipped to the U.S., making it optimal for HS 8708 (vehicle parts) and 8704 (commercial vehicles). South Korea is positioning as an EV battery and software component leader, aligning with BYD's competitive threat to traditional automakers. Sellers should conduct tariff rate analysis by HS code for each sourcing country using USITC's interactive tariff schedule to identify 3-5% tariff savings opportunities through sourcing diversification by Q2 2026.
EV-adjacent categories represent growth opportunities as traditional automotive suppliers face margin compression. Battery components, charging infrastructure, EV software tools, and electric motor parts are experiencing accelerated demand as BYD's EV dominance forces legacy automakers like Toyota to accelerate electrification. Sellers should prioritize categories including: lithium-ion battery packs (HS 8507), electric motors (HS 8501), charging cables (HS 8544), and EV management software. These categories typically see 15-25% annual growth during tariff-driven supply chain transitions, with lower competitive saturation than traditional aftermarket parts. The timing window through 2026 offers first-mover advantages before larger competitors establish EV component supply chains.
Toyota's appointment of CFO Kenta Kon signals aggressive inventory destocking and supplier consolidation through Q2-Q3 2026. Sellers should reduce safety stock on slow-moving Japanese automotive components by 20-30% and accelerate inventory turnover to avoid obsolescence during the transition period. Simultaneously, build inventory in alternative sourcing countries (Vietnam, Mexico, South Korea) to capture market share as Japanese suppliers lose volume. Implement just-in-time procurement strategies to reduce working capital exposure to tariff volatility. Monitor Toyota's quarterly earnings announcements (April 1 onwards) for procurement guidance; expect 5-8% component price reductions as suppliers compete for retained volume, creating opportunities to improve margins through strategic timing of purchases.
The $9 billion tariff impact creates demand for tariff mitigation and trade compliance services. Sellers can develop offerings including: tariff rate analysis by HS code and sourcing country, customs brokerage optimization, duty drawback consulting, and trade agreement utilization (USMCA, Japan-U.S. agreement). Tariff mitigation software and consulting services typically command 2-5% of transaction value for automotive supply chains. Sellers with expertise in HS code classification (8708 vs. 8704 vs. 8703 distinctions) can offer reclassification consulting to reduce tariff exposure. The April 1-June 30, 2026 window represents peak demand as suppliers implement new sourcing strategies; position services to capture 10-15% of the automotive component market's tariff optimization spend.
Toyota's $9 billion tariff impact directly signals margin compression for sellers importing Japanese automotive components (HS codes 8708, 8704, 8703). The newly negotiated 15% U.S. tariff on Japanese auto exports—6x higher than historical rates—will cascade through supply chains as Toyota implements cost-cutting measures under new CFO leadership. Sellers should expect 8-15% cost increases on Japanese-sourced parts through Q2-Q3 2026, with potential 5-8% price reductions as suppliers compete for volume during Toyota's procurement rationalization. The April 1, 2026 CEO transition deadline marks when aggressive cost-cutting initiatives will accelerate, creating a 6-12 month window of supply chain volatility affecting inventory planning and pricing strategies.
Canada's multi-billion dollar EV incentive package (announced February 5, 2026) signals a strategic shift in North American automotive manufacturing away from Japan-U.S. direct trade. Sellers should evaluate establishing Canadian sourcing relationships for EV components, batteries, and related products to capture incentive-driven manufacturing expansion. Canadian EV component suppliers will likely offer competitive pricing (subsidized by government incentives) and USMCA tariff advantages (0% on qualifying products). The timing window through 2026-2027 offers first-mover advantages in establishing Canadian supply relationships before larger competitors recognize the opportunity. Monitor Canadian government EV incentive announcements for specific product categories and supplier eligibility; prioritize categories with 15%+ tariff savings potential through Canadian sourcing versus Japan or China alternatives.
The 6-12 month window from February 2026 through August 2026 represents peak opportunity before larger competitors establish alternative sourcing networks. Toyota's April 1 CEO transition marks the acceleration point for cost-cutting initiatives; the subsequent 90-120 days (April-July 2026) will see rapid supplier consolidation and procurement strategy shifts. Sellers who establish alternative sourcing relationships (Vietnam, Mexico, South Korea, Canada) and implement tariff optimization strategies by June 30, 2026 will capture 15-25% margin advantages over competitors who delay. The competitive advantage erodes as larger sellers (Amazon, Alibaba, eBay) develop institutional tariff mitigation capabilities; first-movers can establish supplier relationships and customer contracts before price competition intensifies. Immediate actions: conduct HS code tariff analysis, identify alternative sourcing countries, and establish supplier relationships by April 15, 2026.
Pricing strategy must account for three competing forces: (1) 15% tariff on Japanese imports increasing landed costs 8-15%; (2) Toyota's cost-cutting driving 5-8% component price reductions as suppliers compete for volume; (3) margin compression across the automotive supply chain. Sellers should implement dynamic pricing by sourcing country: Japanese-sourced components face 15% tariff headwinds, while Mexico-sourced products benefit from 0% USMCA tariffs. Recommended pricing approach: maintain current prices on alternative-sourced products (Vietnam, Mexico, South Korea) to capture market share from Japanese suppliers; reduce prices on Japanese-sourced inventory by 3-5% to accelerate turnover before tariff pass-through occurs. Monitor competitor pricing weekly through April-June 2026; expect 8-12% price volatility as suppliers adjust to new tariff environment. Lock in supplier pricing by May 31, 2026 before tariff-driven cost increases stabilize.